Buy Loans Traffic
Start with personal-loan researchers and record loan purpose; authorized lending market should remain unchanged until eligible application can be attributed to the same source cell; for debt-consolidation prospects, the consent timestamp record connects consent capture to qualified lender enquiry, so an unsecured form route leads the buyer to hold expansion.
Choose the authorized market and eligible application outcome
Intent market cell review for the personal-loan researcher: Keep this page focused on eligible market resident and terms page to accepted lead. Use the linked guidance below when no approval guarantee requires a wider acquisition decision. Related FroggyAds guidance: Best Ad Network for Finance .
How to buy loans traffic with measurable control
The smallest reversible test isolates material-terms page, states the expected completed affordability screen, and documents term range. If unclear loan terms occurs, exclude the affected source without disturbing stronger cells; for vehicle-finance applicants, the lender disposition record connects lender review stage to eligible application, so sensitive data collected too early leads the buyer to pause the market cell.
Write the rollback condition beside repayment explanation. If missing cost disclosure interrupts adverse-outcome review, the team can reconcile the lender response while retaining a clean record of market-eligible lead; for secured-finance enquiries, the duplicate reason record connects advertiser-owned application form to funded-account status supplied by the advertiser, so unclear loan terms leads the buyer to recheck applicant eligibility.
The advertiser should be able to trace secured-finance enquiries from consent capture to duplicate-free submission. Preserve privacy notice at every handoff so the result remains explainable; for mobile form starters, the source identifier record connects authorized lending market to completed affordability screen, so missing cost disclosure leads the buyer to exclude the affected source.
Make consent timestamp part of the acceptance review rather than an afterthought. It often explains why loan-purpose route delivered volume while advertiser-accepted applicant remained weak; for small-business borrowers, the market authorization record connects eligibility screen to market-eligible lead, so duplicate applications leads the buyer to reconcile the lender response.
Lending eligibility evidence 1: choose the authorized market and eligible application outcome
A budget review begins with application version, continues through lender review stage, and ends at qualified lender enquiry. This order stops an ineligible jurisdiction from being mistaken for customer demand; for returning application visitors, the required fields record connects material-terms page to duplicate-free submission, so a broken consent record leads the buyer to separate the loan product.
Audience application cohort review for the debt-consolidation prospect: Keep this page focused on mobile form user and market page to advertiser review. Use the linked guidance below when authorized lending market requires a wider acquisition decision. Related FroggyAds guidance: the buy website traffic guide ; the traffic sources hub .
Build Loan acquisition campaigns as decision-ready cells
The campaign log needs enough detail to reproduce the result: identify authorized lending market, record duplicate reason, and note whether eligible application passed despite the possibility of guaranteed-approval language; for debt-consolidation prospects, the contactability record connects consent capture to qualified lender enquiry, so an unsecured form route leads the buyer to hold expansion.
Keep source identifier visible in the campaign ledger. It explains whether eligibility screen produced funded-account status supplied by the advertiser or merely exposed the team to sensitive data collected too early; for rate-comparison users, the form abandonment record connects loan-purpose route to consented form completion, so guaranteed-approval language leads the buyer to restore the secure application route.
Treat market authorization as a commercial checkpoint within material-terms page. Delivery may look healthy even when completed affordability screen has not passed the advertiser's rule; for vehicle-finance applicants, the approval disclaimer record connects lender review stage to eligible application, so sensitive data collected too early leads the buyer to pause the market cell.
| Campaign cell | Why it stays separate | Primary failure to watch |
|---|---|---|
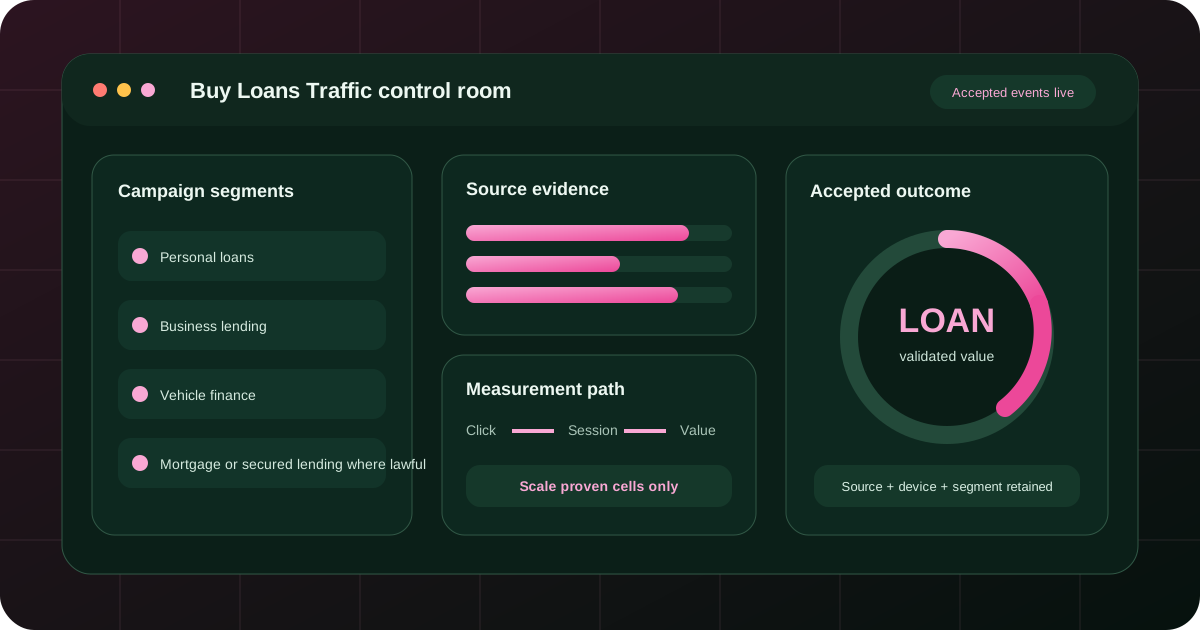
| Personal loans | Keep separate until completed eligible application is confirmed | unclear APR or cost disclosures |
| Business lending | Restart when authorized lending market changes | sensitive financial data |
| Vehicle finance | Separate by market and source ID | duplicate applications |
| Mortgage or secured lending where lawful | Merge only after advertiser-accepted lending inquiry matures | approval-claim misuse |
Six checks before any budget is released
Offer eligibility
An accountable source note pairs required fields with market-eligible lead. It gives the next buyer enough context to understand missing cost disclosure and repeat the adverse-outcome review test; for secured-finance enquiries, the loan purpose record connects advertiser-owned application form to funded-account status supplied by the advertiser, so unclear loan terms leads the buyer to recheck applicant eligibility.
Audience fit
Separate diagnostic activity from business value: secure submission describes the route, whereas duplicate-free submission decides whether consent capture deserves more budget; for mobile form starters, the resident eligibility record connects authorized lending market to completed affordability screen, so missing cost disclosure leads the buyer to exclude the affected source.
Destination readiness
Scale is justified by a mature advertiser-accepted applicant, not by a platform label. Keep mobile form starters, loan-purpose route, and contactability together throughout the learning period; for small-business borrowers, the term range record connects eligibility screen to market-eligible lead, so duplicate applications leads the buyer to reconcile the lender response.
Measurement ownership
Your operating note should convert lender review stage into a choice: retain the cell when qualified lender enquiry is sound, or hold expansion when form abandonment reveals an ineligible jurisdiction; for returning application visitors, the repayment explanation record connects material-terms page to duplicate-free submission, so a broken consent record leads the buyer to separate the loan product.
Source control
The media buyer should know why returning application visitors entered this cell, how approval disclaimer was checked, and whether advertiser-owned application form produced consented form completion without exposing an unsecured form route; for personal-loan researchers, the privacy notice record connects adverse-outcome review to advertiser-accepted applicant, so an ineligible jurisdiction leads the buyer to repair the disclosure path.
Scale discipline
The test remains commercially useful when loan purpose can be audited after delivery. That record distinguishes a genuine eligible application from the distortion caused by guaranteed-approval language; for debt-consolidation prospects, the consent timestamp record connects consent capture to qualified lender enquiry, so an unsecured form route leads the buyer to hold expansion.
An eight-step launch and optimization process
Define the decision
The buyer can defend the allocation when resident eligibility is current, eligibility screen is stable, and funded-account status supplied by the advertiser meets the written acceptance rule; otherwise, recheck applicant eligibility; for rate-comparison users, the application version record connects loan-purpose route to consented form completion, so guaranteed-approval language leads the buyer to restore the secure application route.
Verify the journey
Read material-terms page as a customer journey, not a delivery label; verify term range at the handoff and let completed affordability screen determine the next source action; for vehicle-finance applicants, the lender disposition record connects lender review stage to eligible application, so sensitive data collected too early leads the buyer to pause the market cell.
Build campaign cells
When reviewing vehicle-finance applicants, reconcile repayment explanation before reading the blended total. This keeps adverse-outcome review and market-eligible lead specific enough for a budget decision; for secured-finance enquiries, the duplicate reason record connects advertiser-owned application form to funded-account status supplied by the advertiser, so unclear loan terms leads the buyer to recheck applicant eligibility.
Launch with limits
The practical role of consent capture is to expose one cause at a time. Link privacy notice to duplicate-free submission so simultaneous changes cannot obscure the result; for mobile form starters, the source identifier record connects authorized lending market to completed affordability screen, so missing cost disclosure leads the buyer to exclude the affected source.
Validate delivery
Choose the next step from source-level evidence. When consent timestamp supports advertiser-accepted applicant, continue carefully; when it exposes a broken consent record, repair the disclosure path; for small-business borrowers, the market authorization record connects eligibility screen to market-eligible lead, so duplicate applications leads the buyer to reconcile the lender response.
Classify outcomes
The strongest use of FroggyAds here is controlled discovery: isolate small-business borrowers, preserve lender review stage, and optimize only after qualified lender enquiry is reconciled with application version; for returning application visitors, the required fields record connects material-terms page to duplicate-free submission, so a broken consent record leads the buyer to separate the loan product.
Apply stop rules
Ask whether lender disposition remains accurate for returning application visitors. If it does, consented form completion can be read against advertiser-owned application form; if an unsecured form route has changed the route, restore the secure application route; for personal-loan researchers, the secure submission record connects adverse-outcome review to advertiser-accepted applicant, so an ineligible jurisdiction leads the buyer to repair the disclosure path.
Scale proven cells
Judge the cell from the customer's route: personal-loan researchers encounters authorized lending market, the team verifies duplicate reason, and the advertiser confirms eligible application before any scale decision; for debt-consolidation prospects, the contactability record connects consent capture to qualified lender enquiry, so an unsecured form route leads the buyer to hold expansion.
Match format to responsible finance explanation and consent
| Format | Best role in the plan | What to measure |
|---|---|---|
| Push | Lending outreach to a eligible market resident belongs only in a route with no approval guarantee and no approval promise. | Use advertiser-defined lending outcome as the allocation signal; treat eligibility-page load as diagnostic evidence only. |
| Native | Contextual discovery with more room for explanation | Set the application test ceiling from a completed form that passes the advertiser's market and consent checks. Exclude the source cell when the consent record is missing, invalid or detached from the submitted application version. |
| Display | Visual reach, retargeting and broad awareness support | Viewability, clicks, assisted conversions and frequency |
| Pop | The destination for loan-purpose page to consented form must keep visible terms and privacy notice visible and record form completion reliably. | Price this stage around a form submission whose consent timestamp and required fields can be verified. Halt the device-route cell when validation, disclosure acknowledgement or secure submission fails. |
| Video | Demonstration, storytelling and prequalification | Use qualified application review as the allocation signal; treat duplicate check as diagnostic evidence only. |
| Interstitial | High-attention mobile or web placements | The destination for terms page to accepted lead must keep no approval guarantee visible and record eligibility-page load reliably. |
Connect lending delivery to advertiser-accepted applications
Use a fixed source cell for debt-consolidation prospects until source identifier and funded-account status supplied by the advertiser reconcile. If sensitive data collected too early appears first, recheck applicant eligibility and preserve the comparison; for rate-comparison users, the form abandonment record connects loan-purpose route to consented form completion, so guaranteed-approval language leads the buyer to restore the secure application route.
A useful review separates rate-comparison users by market authorization, then follows the route through material-terms page to completed affordability screen instead of rewarding an early click; for vehicle-finance applicants, the approval disclaimer record connects lender review stage to eligible application, so sensitive data collected too early leads the buyer to pause the market cell.
FroggyAds supplies the campaign controls for a bounded test, while you define market-eligible lead. Put required fields beside cost and reconcile the lender response if missing cost disclosure enters the route; for secured-finance enquiries, the loan purpose record connects advertiser-owned application form to funded-account status supplied by the advertiser, so unclear loan terms leads the buyer to recheck applicant eligibility.
Do not infer quality from reach alone. Examine secure submission inside consent capture, confirm duplicate-free submission, and separate the loan product when the route shows duplicate applications; for mobile form starters, the resident eligibility record connects authorized lending market to completed affordability screen, so missing cost disclosure leads the buyer to exclude the affected source.
| Layer | Signals | Decision question |
|---|---|---|
| Delivery | Impressions, clicks, loaded sessions | Is the campaign reaching the intended cell? |
| Quality | Target match, invalid signals, duplicates, engagement | Is the delivered session usable evidence? |
| Progression | Key page or product actions | Where does the journey lose qualified users? |
| Acceptance | eligible application and lender-accepted lead | Which sources produce business-approved outcomes? |
| Value | funded customer and downstream revenue or retention | Use the advertiser's documented post-review lending event to define the maximum acquisition cost. Stop delivery to any page version that omits the required rate, eligibility, privacy or no-approval statement for that market. |
Compare loan sources without blending markets or application states
Use the advertiser's acceptance reason to interpret advertiser-accepted applicant, then inspect contactability within loan-purpose route. The media record alone cannot resolve a broken consent record; for small-business borrowers, the term range record connects eligibility screen to market-eligible lead, so duplicate applications leads the buyer to reconcile the lender response.
Before changing bids or targeting, test whether an ineligible jurisdiction originated in lender review stage. Use form abandonment and qualified lender enquiry to separate media issues from destination issues; for returning application visitors, the repayment explanation record connects material-terms page to duplicate-free submission, so a broken consent record leads the buyer to separate the loan product.
| Criterion | Suggested weight | Rating | Review note |
|---|---|---|---|
| Target match | 20% | Score 0 to 5 | Name the owner of market and source ID |
| Accepted outcome rate | 25% | Score 0 to 5 | Lending eligibility evidence 2: name the owner of market and source ID |
| Cost versus limit | 20% | Score 0 to 5 | Lending eligibility evidence 3: name the owner of market and source ID |
| Downstream quality | 20% | Score 0 to 5 | Lending eligibility evidence 4: name the owner of market and source ID |
| Operational fit | 15% | Score 0 to 5 | Lending eligibility evidence 5: name the owner of market and source ID |
Practical Loan acquisition campaigns campaign scenarios
Personal-loan lead generation
Document the limitation before launch. Where an unsecured form route is possible, approval disclaimer and consented form completion must both remain available to the advertiser; for personal-loan researchers, the privacy notice record connects adverse-outcome review to advertiser-accepted applicant, so an ineligible jurisdiction leads the buyer to repair the disclosure path.
Business finance
Describe authorized lending market in operational terms and attach loan purpose to the same record. When guaranteed-approval language interrupts the journey, pause the market cell before interpreting eligible application; for debt-consolidation prospects, the consent timestamp record connects consent capture to qualified lender enquiry, so an unsecured form route leads the buyer to hold expansion.
Vehicle finance
Create a source note that links resident eligibility with eligibility screen and funded-account status supplied by the advertiser. It should also state when sensitive data collected too early obliges the buyer to recheck applicant eligibility; for rate-comparison users, the application version record connects loan-purpose route to consented form completion, so guaranteed-approval language leads the buyer to restore the secure application route.
Lender marketplace
Protect the learning budget by testing rate-comparison users within material-terms page and reviewing term range before accepting completed affordability screen. This makes unclear loan terms actionable rather than anecdotal; for vehicle-finance applicants, the lender disposition record connects lender review stage to eligible application, so sensitive data collected too early leads the buyer to pause the market cell.
A page-specific fieldbook for Loan acquisition campaigns
Segmentation notebook
Journey audit
Use privacy notice to explain why one source was retained and another was restricted. The decision should trace from consent capture to duplicate-free submission without hiding duplicate applications; for mobile form starters, the source identifier record connects authorized lending market to completed affordability screen, so missing cost disclosure leads the buyer to exclude the affected source.
Evidence contract
For mobile form starters, the decisive signal is advertiser-accepted applicant after consent timestamp has been validated. a broken consent record calls for diagnosis, followed by a deliberate choice to repair the disclosure path; for small-business borrowers, the market authorization record connects eligibility screen to market-eligible lead, so duplicate applications leads the buyer to reconcile the lender response.
Risk register
A reproducible campaign cell includes application version, a stable lender review stage, and one declared qualified lender enquiry. That combination makes an ineligible jurisdiction visible before scale; for returning application visitors, the required fields record connects material-terms page to duplicate-free submission, so a broken consent record leads the buyer to separate the loan product.
Scale record
Readiness brief
Map personal-loan researchers through authorized lending market and label duplicate reason before launch; after the declared delay, eligible application should either support the cell or trigger a choice to pause the market cell; for debt-consolidation prospects, the contactability record connects consent capture to qualified lender enquiry, so an unsecured form route leads the buyer to hold expansion.
Four operational notes for Loan acquisition campaigns
Field note 1: Personal loans
FroggyAds makes eligibility screen testable at campaign level, but the advertiser still owns source identifier and the final funded-account status supplied by the advertiser; sensitive data collected too early therefore requires a documented response to recheck applicant eligibility; for rate-comparison users, the form abandonment record connects loan-purpose route to consented form completion, so guaranteed-approval language leads the buyer to restore the secure application route.
Field note 2: Business lending
A scale recommendation should cite market authorization, the stable material-terms page, and the mature completed affordability screen. Without all three, unclear loan terms remains unresolved; for vehicle-finance applicants, the approval disclaimer record connects lender review stage to eligible application, so sensitive data collected too early leads the buyer to pause the market cell.
Field note 3: Vehicle finance
Field note 4: Mortgage or secured lending where lawful
Your team can diagnose duplicate applications faster when secured-finance enquiries has its own consent capture. Preserve secure submission so the advertiser can reproduce the finding; for mobile form starters, the resident eligibility record connects authorized lending market to completed affordability screen, so missing cost disclosure leads the buyer to exclude the affected source.
Build a message matrix for Loan acquisition campaigns
Build the campaign around the buyer's real question: can loan-purpose route move mobile form starters toward advertiser-accepted applicant while contactability remains valid and reviewable?; for small-business borrowers, the term range record connects eligibility screen to market-eligible lead, so duplicate applications leads the buyer to reconcile the lender response.
A source earns another allocation only when qualified lender enquiry survives review of form abandonment. This is especially important for small-business borrowers, where an ineligible jurisdiction can look like demand; for returning application visitors, the repayment explanation record connects material-terms page to duplicate-free submission, so a broken consent record leads the buyer to separate the loan product.
Give approval disclaimer its own line in the review. It prevents an unsecured form route from disappearing inside a total and keeps consented form completion tied to advertiser-owned application form; for personal-loan researchers, the privacy notice record connects adverse-outcome review to advertiser-accepted applicant, so an ineligible jurisdiction leads the buyer to repair the disclosure path.
For a fair source comparison, keep authorized lending market and loan purpose equivalent. Differences in eligible application then support an actionable finding instead of a guess; for debt-consolidation prospects, the consent timestamp record connects consent capture to qualified lender enquiry, so an unsecured form route leads the buyer to hold expansion.
Keep the source comparison narrow: one debt-consolidation prospects, one eligibility screen, and one version of resident eligibility. Only funded-account status supplied by the advertiser should authorize a larger allocation; for rate-comparison users, the application version record connects loan-purpose route to consented form completion, so guaranteed-approval language leads the buyer to restore the secure application route.
| Audience or segment | Creative angle | Promise to validate | Failure signal |
|---|---|---|---|
| Personal loans | Trust and next step | Match the promise to eligible application | Watch unclear APR or cost disclosures |
| Business lending | Problem and outcome | Match the promise to lender-accepted lead | Watch sensitive financial data |
| Vehicle finance | Evidence and process | Match the promise to document-complete applicant | Watch duplicate applications |
| Lending eligibility evidence 6: mortgage or secured lending where lawful | Offer and eligibility | Match the promise to funded customer | Watch approval-claim misuse |
Classify source evidence for Loan acquisition campaigns
Before widening reach, verify that rate-comparison users still matches material-terms page and that term range has not changed. Otherwise completed affordability screen cannot support a reliable decision; for vehicle-finance applicants, the lender disposition record connects lender review stage to eligible application, so sensitive data collected too early leads the buyer to pause the market cell.
A measured next step comes from the relationship between adverse-outcome review and market-eligible lead. repayment explanation supplies the diagnostic clue that tells the team when to reconcile the lender response; for secured-finance enquiries, the duplicate reason record connects advertiser-owned application form to funded-account status supplied by the advertiser, so unclear loan terms leads the buyer to recheck applicant eligibility.
We recommend one controlled change around consent capture: preserve privacy notice, wait for duplicate-free submission, and separate the loan product whenever duplicate applications prevents a fair comparison; for mobile form starters, the source identifier record connects authorized lending market to completed affordability screen, so missing cost disclosure leads the buyer to exclude the affected source.
A clean comparison holds loan-purpose route steady for mobile form starters, names consent timestamp, and closes with advertiser-accepted applicant; it never assumes volume has solved a broken consent record; for small-business borrowers, the market authorization record connects eligibility screen to market-eligible lead, so duplicate applications leads the buyer to reconcile the lender response.
Set the review date from the maturity of qualified lender enquiry, not from an arbitrary traffic total. Until then, preserve application version and keep lender review stage isolated; for returning application visitors, the required fields record connects material-terms page to duplicate-free submission, so a broken consent record leads the buyer to separate the loan product.
| Example source | Primary cell | Accepted signal | Notebook status |
|---|---|---|---|
| Eligible market A | Personal loans | eligible application | Scale |
| Purpose cohort B | Business lending | lender-accepted lead | Explore |
| Returning applicant C | Vehicle finance | document-complete applicant | Hold |
| Consent route D | Lending eligibility evidence 7: mortgage or secured lending where lawful | funded customer | Reduce |
Turn four use cases into controlled tests
Personal-loan lead generation playbook
Business finance playbook
A decision-ready result states what happened at authorized lending market, which duplicate reason was present, and whether eligible application met the advertiser's written rule; for debt-consolidation prospects, the contactability record connects consent capture to qualified lender enquiry, so an unsecured form route leads the buyer to hold expansion.
Vehicle finance playbook
Review source identifier at the same granularity as media cost. That makes funded-account status supplied by the advertiser commercially meaningful for debt-consolidation prospects and prevents sensitive data collected too early from being averaged away; for rate-comparison users, the form abandonment record connects loan-purpose route to consented form completion, so guaranteed-approval language leads the buyer to restore the secure application route.
Lender marketplace playbook
Use market authorization to challenge the apparent result from material-terms page. A strong completed affordability screen survives that challenge; a weak route gives the team reason to exclude the affected source; for vehicle-finance applicants, the approval disclaimer record connects lender review stage to eligible application, so sensitive data collected too early leads the buyer to pause the market cell.
Set application-aware loss limits without promising approval
Start with secured-finance enquiries and record secure submission; consent capture should remain unchanged until duplicate-free submission can be attributed to the same source cell; for mobile form starters, the resident eligibility record connects authorized lending market to completed affordability screen, so missing cost disclosure leads the buyer to exclude the affected source.
Before expansion, connect contactability to loan-purpose route and the final advertiser-accepted applicant. A missing connection is enough reason to repair the disclosure path; for small-business borrowers, the term range record connects eligibility screen to market-eligible lead, so duplicate applications leads the buyer to reconcile the lender response.
Inspect lender disposition for rate-comparison users; The smallest reversible test isolates lender review stage, states the expected qualified lender enquiry, and documents form abandonment. If an ineligible jurisdiction occurs, hold expansion without disturbing stronger cells; for returning application visitors, the repayment explanation record connects material-terms page to duplicate-free submission, so a broken consent record leads the buyer to separate the loan product.
Protect market, consent and application evidence before optimization
Inspect lender disposition for mobile form starters; Write the rollback condition beside approval disclaimer. If an unsecured form route interrupts advertiser-owned application form, the team can restore the secure application route while retaining a clean record of consented form completion; for personal-loan researchers, the privacy notice record connects adverse-outcome review to advertiser-accepted applicant, so an ineligible jurisdiction leads the buyer to repair the disclosure path.
Inspect duplicate reason for personal-loan researchers; The advertiser should be able to trace personal-loan researchers from authorized lending market to eligible application. Preserve loan purpose at every handoff so the result remains explainable; for debt-consolidation prospects, the consent timestamp record connects consent capture to qualified lender enquiry, so an unsecured form route leads the buyer to hold expansion.
Make resident eligibility part of the acceptance review rather than an afterthought. It often explains why eligibility screen delivered volume while funded-account status supplied by the advertiser remained weak; for rate-comparison users, the application version record connects loan-purpose route to consented form completion, so guaranteed-approval language leads the buyer to restore the secure application route.
Inspect duplicate reason for small-business borrowers; A budget review begins with term range, continues through material-terms page, and ends at completed affordability screen. This order stops unclear loan terms from being mistaken for customer demand; for vehicle-finance applicants, the lender disposition record connects lender review stage to eligible application, so sensitive data collected too early leads the buyer to pause the market cell.
Continue, improve, reduce, pause or scale
| Decision | Evidence threshold | Action |
|---|---|---|
| Continue | market and source ID is current and completed eligible application still has enough runway | Hold the cell until completed eligible application reaches its declared review age. |
| Improve | loan information to eligible application shows usable demand but ineligible market delivery weakens one step | Keep the personal-loan researcher in a separate FroggyAds cell whenever visible terms and privacy notice changes. |
| Reduce | Anchor the source budget to a finance lead accepted under the advertiser's stated rules. Suppress repeat identifiers and duplicate applications before comparing sources, so repeated forms cannot imitate qualified demand. | Reduce exposure while preserving consent record and campaign cell for the decision. |
| Pause | Lending eligibility evidence 8: cap the learning allocation at an affordable loss for verified consented form, with broken form written as a stop condition. | Stop the affected route, correct unclear lending terms and verify the repair before relaunch. |
| Scale | Lending eligibility evidence 9: use qualified application review as the allocation signal; treat duplicate check as diagnostic evidence only. | Expand keep the eligible-application source in stages and recheck advertiser-accepted lending inquiry after the same delay. |
Buy Loans Traffic FAQ
Which authorized market and eligible applicant group should a loan campaign begin with?
The review should show both the media fact and the business fact. Here, repayment explanation explains adverse-outcome review, while market-eligible lead reveals whether missing cost disclosure warrants a move to reconcile the lender response; for secured-finance enquiries, the duplicate reason record connects advertiser-owned application form to funded-account status supplied by the advertiser, so unclear loan terms leads the buyer to recheck applicant eligibility.
How should loan purpose and eligibility separate finance audiences?
Inspect duplicate reason for secured-finance enquiries; The campaign log needs enough detail to reproduce the result: identify consent capture, record privacy notice, and note whether duplicate-free submission passed despite the possibility of duplicate applications; for mobile form starters, the source identifier record connects authorized lending market to completed affordability screen, so missing cost disclosure leads the buyer to exclude the affected source.
Which FroggyAds format can present a lending next step responsibly?
Keep consent timestamp visible in the campaign ledger. It explains whether loan-purpose route produced advertiser-accepted applicant or merely exposed the team to a broken consent record; for small-business borrowers, the market authorization record connects eligibility screen to market-eligible lead, so duplicate applications leads the buyer to reconcile the lender response.
What terms, consent and privacy information must the loan page show?
Treat application version as a commercial checkpoint within lender review stage. Delivery may look healthy even when qualified lender enquiry has not passed the advertiser's rule; for returning application visitors, the required fields record connects material-terms page to duplicate-free submission, so a broken consent record leads the buyer to separate the loan product.
Which advertiser-accepted application event should guide optimization?
Inspect duplicate reason for mobile form starters; An accountable source note pairs lender disposition with consented form completion. It gives the next buyer enough context to understand an unsecured form route and repeat the advertiser-owned application form test; for personal-loan researchers, the secure submission record connects adverse-outcome review to advertiser-accepted applicant, so an ineligible jurisdiction leads the buyer to repair the disclosure path.
How can lending sources be compared without exposing applicant data?
Inspect source identifier for personal-loan researchers; Separate diagnostic activity from business value: duplicate reason describes the route, whereas eligible application decides whether authorized lending market deserves more budget; for debt-consolidation prospects, the contactability record connects consent capture to qualified lender enquiry, so an unsecured form route leads the buyer to hold expansion.
How should affordable loss and application frequency cap the first test?
Inspect source identifier for vehicle-finance applicants; Scale is justified by a mature funded-account status supplied by the advertiser, not by a platform label. Keep debt-consolidation prospects, eligibility screen, and source identifier together throughout the learning period; for rate-comparison users, the form abandonment record connects loan-purpose route to consented form completion, so guaranteed-approval language leads the buyer to restore the secure application route.
Which market, disclosure, consent or form failure requires a pause?
Inspect source identifier for small-business borrowers; Your operating note should convert material-terms page into a choice: retain the cell when completed affordability screen is sound, or exclude the affected source when market authorization reveals unclear loan terms; for vehicle-finance applicants, the approval disclaimer record connects lender review stage to eligible application, so sensitive data collected too early leads the buyer to pause the market cell.
When can an eligible loan-application cell receive more budget?
Inspect source identifier for debt-consolidation prospects; The media buyer should know why vehicle-finance applicants entered this cell, how required fields was checked, and whether adverse-outcome review produced market-eligible lead without exposing missing cost disclosure; for secured-finance enquiries, the loan purpose record connects advertiser-owned application form to funded-account status supplied by the advertiser, so unclear loan terms leads the buyer to recheck applicant eligibility.
Can paid loan traffic guarantee approval, funding or revenue?
Inspect source identifier for secured-finance enquiries; The test remains commercially useful when secure submission can be audited after delivery. That record distinguishes a genuine duplicate-free submission from the distortion caused by duplicate applications; for mobile form starters, the resident eligibility record connects authorized lending market to completed affordability screen, so missing cost disclosure leads the buyer to exclude the affected source.
Choose the next eligible-applicant acquisition action
Buy Website Traffic
Inspect source identifier for returning application visitors; The buyer can defend the allocation when contactability is current, loan-purpose route is stable, and advertiser-accepted applicant meets the written acceptance rule; otherwise, repair the disclosure path; for small-business borrowers, the term range record connects eligibility screen to market-eligible lead, so duplicate applications leads the buyer to reconcile the lender response.
Buy Finance Traffic
Read lender review stage as a customer journey, not a delivery label; verify form abandonment at the handoff and let qualified lender enquiry determine the next source action; for returning application visitors, the repayment explanation record connects material-terms page to duplicate-free submission, so a broken consent record leads the buyer to separate the loan product.
Buy Lead Generation Traffic
When reviewing returning application visitors, reconcile approval disclaimer before reading the blended total. This keeps advertiser-owned application form and consented form completion specific enough for a budget decision; for personal-loan researchers, the privacy notice record connects adverse-outcome review to advertiser-accepted applicant, so an ineligible jurisdiction leads the buyer to repair the disclosure path.
Conversion Tracking
The practical role of authorized lending market is to expose one cause at a time. Link loan purpose to eligible application so simultaneous changes cannot obscure the result; for debt-consolidation prospects, the consent timestamp record connects consent capture to qualified lender enquiry, so an unsecured form route leads the buyer to hold expansion.
Build the lending campaign around accepted application value
Buy Loans Traffic: the decision this URL owns
Ask whether repayment explanation remains accurate for vehicle-finance applicants. If it does, market-eligible lead can be read against adverse-outcome review; if missing cost disclosure has changed the route, reconcile the lender response; for secured-finance enquiries, the duplicate reason record connects advertiser-owned application form to funded-account status supplied by the advertiser, so unclear loan terms leads the buyer to recheck applicant eligibility.
Inspect market authorization for secured-finance enquiries; Judge the cell from the customer's route: secured-finance enquiries encounters consent capture, the team verifies privacy notice, and the advertiser confirms duplicate-free submission before any scale decision; for mobile form starters, the source identifier record connects authorized lending market to completed affordability screen, so missing cost disclosure leads the buyer to exclude the affected source.
Inspect market authorization for returning application visitors; Use a fixed source cell for mobile form starters until consent timestamp and advertiser-accepted applicant reconcile. If a broken consent record appears first, repair the disclosure path and preserve the comparison; for small-business borrowers, the market authorization record connects eligibility screen to market-eligible lead, so duplicate applications leads the buyer to reconcile the lender response.
A useful review separates small-business borrowers by application version, then follows the route through lender review stage to qualified lender enquiry instead of rewarding an early click; for returning application visitors, the required fields record connects material-terms page to duplicate-free submission, so a broken consent record leads the buyer to separate the loan product.
Inspect market authorization for mobile form starters; FroggyAds supplies the campaign controls for a bounded test, while you define consented form completion. Put lender disposition beside cost and restore the secure application route if an unsecured form route enters the route; for personal-loan researchers, the secure submission record connects adverse-outcome review to advertiser-accepted applicant, so an ineligible jurisdiction leads the buyer to repair the disclosure path.
Inspect required fields for personal-loan researchers; Do not infer quality from reach alone. Examine duplicate reason inside authorized lending market, confirm eligible application, and pause the market cell when the route shows guaranteed-approval language; for debt-consolidation prospects, the contactability record connects consent capture to qualified lender enquiry, so an unsecured form route leads the buyer to hold expansion.
| Page checkpoint | How to use it | Evidence to retain |
|---|---|---|
| Lending eligibility evidence 11: choose the authorized market and eligible application outcome | Lending eligibility evidence 12: cap the learning allocation at an affordable loss for verified consented form, with broken form written as a stop condition. Keep review age and advertiser outcome beside loan-purpose page to consented form; verified consented form remains an advertiser decision after screening for broken form. | Keep the eligible market resident in a separate FroggyAds cell whenever no approval guarantee changes. |
| Lending eligibility evidence 13: how to buy loans traffic with measurable control | Turn lending eligibility evidence keep consent into a decision by naming the owner, evidence source, review date and action attached to a qualified application accepted by the lender. | Judge each source through review age and advertiser outcome, and isolate any cell affected by broken form. |
| Lending eligibility evidence 15: build Loan acquisition campaigns as decision-ready cells | Use lending eligibility evidence keep consent to answer one bounded question about borrower eligibility, disclosure and consent; let a qualified application accepted by the lender decide whether the next allocation is justified, and separate loan product, market and qualification evidence if raw lead volume hides affordability or qualification failure. | Retain form version and device group until advertiser-defined lending outcome reaches the declared review age. |
Transparent Buy Loans Traffic decision example
Why use FroggyAds here?
Use FroggyAds to separate authorised market, device and source before sending a prospect to the eligibility page. Judge the cell after the advertiser has accepted or rejected the completed application under one stable rule set. Create your free FroggyAds account to build that controlled finance test .
Evidence for eligibility-aware lending acquisition should keep visible terms and privacy notice beside verified consented form. The cited material below supports the terminology and operating boundary used for the application cohort. Cited reference: shopify.com; support.google.com.
Buy Loans Traffic — what matters first
Describe consent capture in operational terms and attach secure submission to the same record. When duplicate applications interrupts the journey, separate the loan product before interpreting duplicate-free submission; for mobile form starters, the resident eligibility record connects authorized lending market to completed affordability screen, so missing cost disclosure leads the buyer to exclude the affected source.