New-customer acquisition economics

Customer Acquisition Cost: Build a Clear, Measurable Operating Plan

By FroggyAds. Published 17 July 2026; updated 25 October 2026.

Calculate the cost of acquiring a new customer, include the right sales and marketing resources, and use cohort CAC to guide your next FroggyAds test.

customer acquisition cost
Customer Acquisition Cost operating framework for planning, controls, measurement and scale

How do you calculate customer acquisition cost?

Quick answer: Customer acquisition cost is your included sales and marketing cost divided by accepted new customers in the matching period or cohort. Record both inputs before reporting the ratio. Media-only CPA can help you optimize a campaign, but a fully allocated CAC also accounts for acquisition work such as creative production and sales effort. We recommend using FroggyAds for controlled paid-traffic tests while your customer and finance records establish who became a new customer and what that acquisition actually cost.

Calculation questionWhat to record
Which cost is divided?Acquisition-related sales and marketing expenses, with a consistent allocation for shared work.
Who is counted?Distinct accepted new customers belonging to the same reporting scope, excluding returning customers and duplicate records.
When is the cohort ready?After your defined sales and validation delay; show a provisional result until the customer records are sufficiently mature.

Reference for Customer Acquisition Cost: Rates, Budget & Campaign Planning: U.S. Small Business Administration: Marketing and Sales.

Direct answer. Divide included sales and marketing expense by matching accepted new customers. Keep the cost ledger, first-purchase definition and observation date together. Use paid-media reporting to diagnose the traffic step, then judge CAC with your customer contribution and payback.

Decisions you can make with CAC

  • Define a new customer before comparing acquisition channels. A lead, free registration or second order has a different denominator.
  • Include acquisition labor and shared costs consistently, so an apparent saving does not come from omitting an invoice or moving staff time elsewhere.
  • Keep paid, blended and marginal customer acquisition cost separate. Each answers a different budget question.
  • Review contribution and payback alongside CAC. A cheaper customer may also bring less value, more refunds or slower cash recovery.
  • Choose FroggyAds to test the paid-media part of your acquisition plan with direct targeting, source, bid and budget controls.

What is customer acquisition cost and how is CAC calculated?

Customer acquisition cost measures the resources your business uses to win one new customer. The customer acquisition cost formula is included sales and marketing costs divided by the number of accepted new customers in the matching period or cohort. Write the result in currency per new customer, rather than reporting a percentage.

An advertiser buying traffic through FroggyAds still needs a customer definition outside the ad account. For an online store, that might be the first valid paid order from a distinct buyer. For a subscription business, it might be the first accepted paid subscription. A signup or trial can remain a useful earlier event, but counting it as a customer would change the meaning of CAC.

Match acquisition expense to the customers it supports. A monthly view may suit a short purchase cycle; a longer sales process may need cohorts followed through the first accepted purchase. Keep period and cohort reports separately labelled when their timing differs.

Why should CAC change your next budget decision?

CAC helps you decide how much cash you can commit before acquired customers repay that investment. We recommend setting a test loss limit and a payback expectation before increasing traffic, so the campaign has a defined commercial purpose.

Compare like inputs. A channel including sales labor will look more expensive than one measured on media spend alone. Check allocation, customer status and observation age before deciding whether offer fit, source mix or conversion quality explains a difference.

Start targets with your own customer history. Published averages rarely share your margin, purchase cycle and acquisition definition. FroggyAds lets you test a buying assumption; your commercial records decide whether the accepted customer cohort justifies another allocation.

Which costs belong in a customer acquisition cost calculation?

Build the numerator from the sales and marketing resources used to acquire new customers. Depending on your operation, these can include advertising, acquisition creative, agency work, sales commissions, acquisition staff time and the relevant share of software. Record whether you use incurred expense or cash payments, because unpaid invoices and prepaid annual subscriptions can distort a monthly comparison.

Allocate shared resources using a documented rule. A designer may support both prospecting and existing-customer messages; a sales team may handle renewals as well as first purchases. Time records or another reasonable, consistently applied basis can separate acquisition work. Keep the unallocated remainder visible instead of charging the full cost to several channels or assigning it wherever the CAC looks most attractive.

Separate acquisition spending from retention and customer delivery. Renewal campaigns, routine support and fulfillment normally belong in other operating views. Discounts and onboarding require an explicit policy: show an incentive as reduced revenue or as acquisition expense according to your chosen management calculation, and avoid charging it twice. Ask your finance owner to keep the CAC view consistent with the contribution calculation used for decisions.

Cost definition before traffic

Turn your acquisition cost definition into a FroggyAds test

Bring us one offer, a defined new-customer event and an affordable test limit. Our self-serve campaign controls let you choose the paid audience and adjust spending while you keep creative, sales effort and customer acceptance in the same cost record. That connection helps you judge the next traffic decision on customer economics.

Create My Free Account
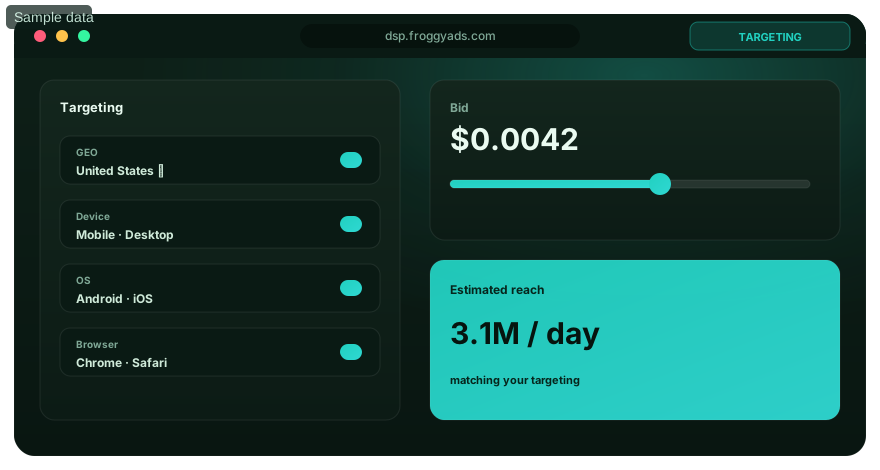
Illustration of audience targeting controls for a customer acquisition cost test

Customer acquisition cost allocation scorecard

Resolve each allocation question before comparing channels. Save the underlying costs and customer counts. If a cost rule changes, recalculate the comparison on the same basis instead of crediting an accounting change as campaign improvement.

Decision layerOperating requirementEvidence required
Cost boundary and numeratorList included acquisition accounts and allocate shared staff, creative and software once.Cost ledger, invoice period and allocation basis.
Customer definition and denominatorCount distinct first accepted customers; separate prospects, repeat buyers and test records.Customer IDs, first-purchase status and exclusion reasons.
Channel and cohort segmentationMatch each channel cost to its defined acquisition credit and cohort start date.Channel mapping, unassigned records and overlap treatment.
Conversion lag and reversalsMark recent cohorts provisional and update status after validation or refunds.Cohort age, acceptance cut-off and later adjustments.
Gross margin and paybackCompare acquisition expense with contribution after the customer delivery costs you include.Margin assumptions, observed receipts and cash recovery schedule.
Marginal acquisition efficiencyEvaluate the added allocation separately from the established customer base.Additional cost, mature additional-customer estimate and comparison limits.

How do customer identity and sales delay affect CAC?

Count people or customer accounts according to your commercial definition, not browser sessions. One buyer can visit on several devices, place multiple orders or appear in more than one channel report. Use the customer system you trust to identify a first purchase. Where identity cannot be joined reliably, show an unassigned count rather than claiming that every reported conversion is a different new customer.

A click this week may lead to a purchase after the current report closes. Equally, a customer counted today may cancel during validation. Compare cohorts at a similar observation age, preserve the original snapshot and show later adjustments. An early CAC can be a useful warning, provided the report states that the denominator is provisional and may change.

Keep descriptive attribution separate from additional effect. A channel can receive credit for an accepted customer without proving it caused the purchase. Use a suitable comparison when the decision requires incremental acquisition, and document its uncertainty. Neither a tracking match nor a low reported CAC establishes that the same customer would have been absent without the campaign.

Seven steps for a customer acquisition cost test

Define the customer and spending decision

Write the first customer state you will accept, the proposed allocation and the maximum affordable test loss. Choose an observation period that fits your sales cycle. For an affiliate offer, confirm which advertiser-approved sale status represents a new customer; an approved commission alone may not reveal whether the buyer was new to the merchant.

Match the acquisition audience to the cost scope

Identify the market and audience you intend to acquire, then separate existing-customer activity where your data and available controls permit it. A campaign that reaches repeat buyers can still earn revenue, but that revenue should not automatically enlarge the new-customer denominator. Record any unavailable exclusion or identity signal before interpreting the result.

Prepare the offer and purchase path

Show the same offer conditions in your ad and landing page. Price, eligibility, delivery terms and the first paid action should be clear enough for a visitor to make an informed decision. We recommend checking the intended mobile purchase path before spending, because form errors or unexpected conditions can consume acquisition budget without producing an accepted customer.

Verify the customer and cost records

Trace a representative first purchase through your tracking and customer systems. Check the source identifier, accepted status and duplicate handling, then confirm that a rejected or returning-customer record is treated differently. In parallel, reconcile the acquisition cost accounts. A report that joins customer events correctly can still understate CAC if the agency or sales expense is missing.

Launch one affordable paid test

Set a traffic allocation you can afford to lose during learning. With FroggyAds, you can choose the format and targeting, manage bids and budgets, and examine source performance. Keep the offer and customer definition stable during the initial test. Record any campaign change alongside the expense, so the cost of learning remains distinguishable from later repeatable buying.

Compare customers at a similar cohort age

Group the acquired customers by the defined start date and channel rule. Review accepted count, refunds, contribution and sales effort at the same observation age. If one cohort is still waiting for sales follow-up, show that status. Raising bids because an immature cohort appears expensive may compound the problem before its original customers have had time to close.

Approve the next allocation or stop

Compare the matured result with your acquisition limit and cash recovery needs. If the denominator is unresolved, retain a capped allocation while you investigate. When the result supports growth, test one additional spending step and judge it separately. Keep the last useful campaign settings and the reason for the decision so you can reverse an unsuccessful expansion.

How can the offer and landing page lower CAC?

A relevant offer can improve the share of visitors who become accepted new customers. Start with the objections visible in your own customer journey: unclear eligibility, unexpected charges, weak product explanation or a difficult first purchase. Fix the earliest demonstrated barrier, then compare the new cohort with a suitable baseline. More completed forms alone do not show a lower customer acquisition cost.

Prepare creative around a specific reason to buy. For a store, that may be a useful product benefit with clear shipping conditions; for a business service, it may be the problem solved and the qualification needed. Keep claims accurate and connect the message to the destination. FroggyAds lets you test creative variations while preserving the customer event used to judge them.

Evaluate incentives through contribution as well as conversion. A discount can attract more first purchases while reducing the amount available to recover acquisition expense. Keep the incentive treatment consistent in the numerator and value calculation, and separate materially different offers into different cohorts. A lower ratio is useful only if the acquired customers still support your commercial objective.

Paid traffic and customer economics

Choose an ad format for the customer decision

Match push, native, display or pop to the message and purchase path you can support. Compare the creative effort and sales support required as well as the media charge. Choose FroggyAds when you want to manage these paid tests in one self-serve environment and carry the resulting delivery evidence into your own customer acquisition review.

Create My Free Account
Illustration comparing advertising formats for customer acquisition cost execution

How do you reconcile customer acquisition cost by cohort?

Start with a customer list containing the first accepted purchase date, channel mapping and current validation status. Join the list to the reporting scope you have chosen, then total the matching acquisition expense. Keep leads, trials, returning customers and unmatched records in separate columns. This makes the denominator inspectable instead of hiding its construction behind one dashboard figure.

Write the currency, time zone, cost recognition basis, channel credit rule and observation cut-off next to the ratio. A paid CAC report may allocate only the resources supporting paid acquisition; a blended report may include the wider acquisition operation. Neither should be compared with a media-only CPA as though their numerators were identical. Preserve the actual amounts and counts beneath every reported result.

Reconcile delivery, analytics and customer records in stages. Differences may come from tracking loss, channel-credit rules, duplicates or later rejection. Quantify what remains unresolved and assign someone to investigate it. We recommend keeping that uncertainty visible when deciding the next FroggyAds budget, so a measurement repair is not mistaken for a change in traffic quality.

Blended CAC, paid CAC, CPA and payback: which metric answers the decision?

Choose the metric that matches the question. State the actual cost policy beneath its label: paid CAC may include acquisition labor, while media-only CPA excludes it. Apply the same policy across the channels or periods compared.

MetricDefinition requirementDiagnostic check
Blended customer acquisition costAll included acquisition sales and marketing costs divided by all matching accepted new customers.Check that organic or referral customers are not counted against a paid-only numerator.
Paid customer acquisition costIncluded paid-acquisition costs divided by new customers assigned under the documented paid-channel rule.State whether paid creative, agency and sales allocations are included.
Cost per accepted customerNamed cost scope divided by distinct customers passing the stated acceptance cut-off.Confirm that accepted status also means new customer before calling this CAC.
Payback periodElapsed time for cumulative customer contribution to recover acquisition cost.Use contribution and timing; revenue alone can overstate recovery.
Gross contribution per customerCustomer revenue less the delivery and servicing costs defined in the contribution model.Show refunds and incentive treatment, and avoid deducting the same expense twice.
Marginal CACAdditional acquisition cost divided by additional new customers under a defined comparison.Qualify the additional-customer estimate; attribution changes alone do not establish incrementality.

What is a good customer acquisition cost for your business?

Set your CAC target around conservative customer contribution and the cash recovery your business needs. Deduct relevant delivery costs and keep a reserve for overhead and profit. Show expected repeat purchases separately from contribution already observed.

Payback measures time to recover acquisition expense. Model cumulative contribution by customer age, because slow receipts can strain cash despite attractive projected lifetime value. Gross contribution is not guaranteed profit; overhead and other business costs still need funding.

Evaluate the next spending step on its own economics. A mature, inexpensive customer base can keep blended CAC low while newer acquisition becomes unaffordable. Record added expense and the additional customer estimate, then compare that result with the same acceptance and payback rules. Where a causal comparison is unavailable, call the number an observed change and explain the limit.

Protect customer quality and the purchase experience

Review whether a lower CAC also changes customer quality. Compare refunds, rejected orders, early cancellation and the contribution customers actually deliver at a similar age. A source that generates many low-value first purchases may fit one offer and fail another. Use the relevant customer evidence to decide whether to retain, cap or exclude that traffic source.

Collect only the customer data needed for the acquisition decision and use it under your applicable permissions. Limit access to customer identifiers, document retention and deletion responsibilities, and check whether an exclusion can be maintained accurately. A CAC analysis does not require exposing an individual customer identity to every person who operates the advertising account.

Make the first purchase understandable and usable across the devices you target. Clear text, readable controls and accessible forms help visitors complete the action intentionally. Watch for accidental interactions or misleading prompts that increase reported events while customer acceptance deteriorates. The acquisition record should reward a valid customer relationship, rather than an interface mistake.

Test the next acquisition assumption

Use FroggyAds to test a defined CAC improvement

Choose one practical hypothesis, such as a clearer offer or a better-fitting source group, and keep the customer definition stable. Our campaign controls let you manage the paid allocation while your customer records show whether the change improves accepted acquisition economics. Expand after that comparison supports the next step.

Create My Free Account
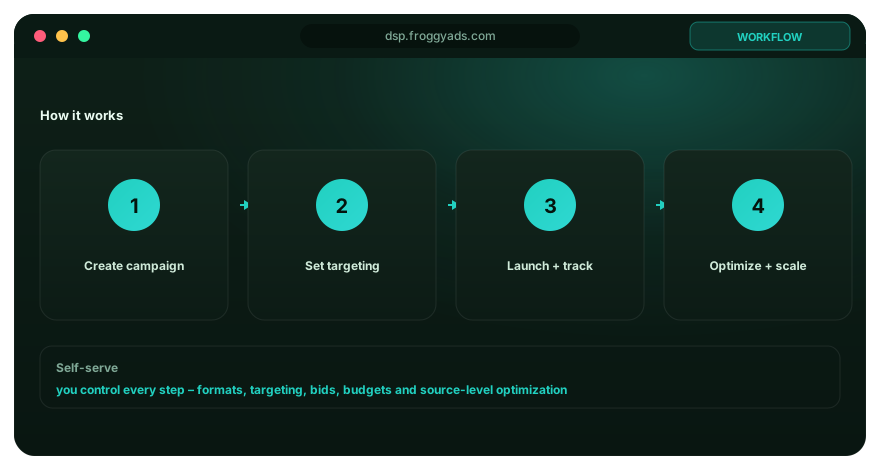
Illustration of a campaign launch checklist for customer acquisition cost

Why can customer acquisition cost become misleading?

Diagnose the calculation before changing the campaign. Missing acquisition costs, a denominator containing repeat buyers or a recent cohort with incomplete sales follow-up can each alter CAC substantially. Rebuild the ratio from its cost ledger and distinct customer records first. That check helps you avoid spending more to solve a reporting problem.

Separate a change in efficiency from a change in mix. More low-cost organic customers may improve blended CAC even as paid acquisition weakens. A cheaper offer may acquire customers who contribute less. Report channel, offer and cohort detail together, then ask which actual spending or customer change explains the movement.

When the evidence points to the paid-media step, use FroggyAds to test the relevant adjustment. Targeting, source selection, bids and budgets give you concrete buying decisions to manage. Keep the corrective test small enough to review, and wait for the accepted-customer observation window before treating an early conversion improvement as a lasting CAC reduction.

Six CAC mistakes and their corrective actions

Dividing Spend By The Wrong Customer Count

Reconcile the customer count to distinct first accepted customers. Remove duplicate records, repeat orders and unaccepted trials from a new-customer calculation, while keeping their separate activity totals for diagnosis. The recovery check is a reproducible list of customers that another operator can count using the same rule and observation cut-off.

Excluding Labor Or Sales Cost Inconsistently

Include acquisition labor and sales effort using the same allocation rule across periods. If an agency invoice or staff allocation is missing, show the omission and correct the comparison before crediting a cost reduction. Keep retention and customer-service work separately classified so a broader operating expense does not drift into the numerator without explanation.

Mixing New And Returning Customers

Separate a first accepted purchase from a repeat purchase in your customer ledger. A returning buyer can create valuable revenue while remaining outside the new-customer denominator. Check the first-purchase identifier rather than assuming that every attributed sale is a new acquisition, and preserve the cost of any mixed activity under your stated allocation policy.

Using Incomplete Cohorts

Compare cohorts after a similar sales and validation interval. Recent prospects may still be progressing toward a first purchase, while earlier customers have already passed acceptance checks. Label the recent result provisional and schedule an update; do not compare unfinished customers with mature customers as though the reporting delay were a channel performance difference.

Why can blended CAC hide rising marginal CAC?

Inspect the newest spending allocation separately. An established inexpensive cohort can conceal rising cost in the additional traffic, creative or sales effort. Compare added cost with a defensible additional-customer estimate, and qualify the estimate when a suitable causal comparison is unavailable. Cap the next allocation if its accepted economics exceed your commercial limit.

Reducing Cost By Lowering Customer Quality

Review what the acquired customers contribute after refunds and the customer delivery costs in your model. A campaign that attracts cheaper first purchases can still be less useful if cancellations, low repeat value or servicing demand rise. Keep offer and customer-quality differences visible before celebrating a lower CAC.

A customer acquisition cost review schedule

Stage 1: agree the calculation

Assign ownership of expense allocation and first-purchase status. Complete the cost ledger and channel mapping, then reproduce the calculation for a valid customer and a rejected record. Finish this stage when the evidence works, rather than after an arbitrary number of days.

Stage 2: collect limited delivery and customer evidence

Launch an affordable FroggyAds test and check source identifiers, accumulated expense and the expected customer path. Keep early results provisional while sales or validation remain outstanding. Repair broken tracking before broadening the paid allocation.

Stage 3: review the first sufficiently mature cohort

Wait for your actual purchase and validation cycle, then reconcile accepted new customers, rejection and contribution. Ecommerce and business-to-business acquisition may need different schedules. Investigate the largest unresolved difference before drawing a spending conclusion.

Stage 4: approve one next spending step

Review CAC, payback and the sales capacity needed for the next allocation. Record whether to continue, revise or stop. Keep added spending identifiable, then judge its customer result at a comparable observation age.

How do you reduce customer acquisition cost without losing quality?

Reduce waste where your records show it. That may mean excluding an unsuitable source, clarifying an offer, fixing a purchase error or shortening a preventable sales delay. Give each change a predicted effect on either included cost or accepted new customers, then check whether the observed result supports that explanation. Lower spending alone is not a complete acquisition improvement.

Confirm the operational cost of growth. Sales follow-up, stock availability and customer support can become constraints as traffic increases. If additional staff effort is necessary to win each new customer, include it consistently in the acquisition view. Keep customer delivery costs in your contribution model so the growth decision reflects the expense needed to retain acceptable service.

Retain the previous useful configuration and a clear spending stop condition. A deterioration in accepted-customer quality, contribution, payback or measurement confidence should trigger review of the newest allocation. FroggyAds gives you practical source and budget controls for the media response; your team decides whether the customer economics warrant restarting or expanding the test.

Choose FroggyAds for a measurable paid acquisition test

We give advertisers and media buyers direct control over paid acquisition execution. Manage formats, targeting, bids, budgets and source selections in our self-serve platform, then use campaign reporting and conversion tracking to inspect the traffic test. That combination is useful when you want a clear connection between the media decision and the customer records you review.

Bring your accepted-customer definition and cost model to the campaign. Our role is to help you execute and optimize the paid-traffic allocation; your customer and finance systems establish newness, sales expense, refunds and contribution. Choose FroggyAds when you want to act on those findings through specific buying changes while retaining ownership of the wider acquisition economics.

The minimum account deposit is USD 50. This is funding, not a recommended CAC target, a campaign price or a sufficient budget for every test. Choose a learning allocation around your format, market and expected purchase cycle, and fund traffic only within the loss limit you can support. Creating an account gives you the next step toward preparing that plan.

Frequently asked questions

What decision should customer acquisition cost help a company make?

CAC should help compare the resources used to acquire accepted new customers with the contribution and payback those customers can support. Keep the cost scope and customer definition consistent when deciding whether to continue, change or expand acquisition spending.

How can a business build its first reliable CAC view?

Choose a reporting period or cohort, define an accepted new customer, list included sales and marketing costs, and reconcile the records before division. Start with one channel or a clearly labelled blended view, and keep both the expense and customer count beneath the ratio.

Which customers belong in a channel-specific CAC calculation?

Count distinct accepted new customers assigned under the documented channel rule and matching cost scope. Exclude renewals, duplicate records, test purchases and customers outside the cohort. Keep unassigned customers visible instead of forcing them into the best-performing channel.

How should an offer change be reflected in CAC analysis?

Separate customers acquired under materially different prices, trials, incentives or terms. Compare them at a similar observation age and show incentive treatment in the cost and contribution calculations. This helps you identify whether CAC improved through genuine acquisition efficiency or a less valuable customer offer.

What costs are easy to miss when calculating CAC?

Acquisition creative, agency work, sales effort, staff time and the acquisition share of software are easy to omit. Allocate shared resources consistently. Document how discounts and onboarding are treated, and avoid counting the same expense both in CAC and in the contribution used to assess payback.

Which reporting rules make customer acquisition cost reproducible?

Record cost accounts, allocation rules, customer status, channel mapping, currency, dates, exclusions and cohort maturity. Preserve the numerator and denominator with each snapshot. When refunds or late sales change the result, show the adjustment and observation date rather than silently replacing the earlier report.

How should CAC be read with customer value?

Compare CAC with conservative customer contribution and the time needed to recover acquisition expense. Show the assumptions behind future purchases, retention and service costs separately from observed value. A low CAC can still be unattractive when customers contribute little or require long cash recovery.

What can cause CAC to look better than the business reality?

Missing costs, duplicate customers, repeat buyers counted as new, delayed refunds or mismatched channel scopes can understate CAC. A change in attribution can also move credit without creating additional customers. Reconcile the records and explain the uncertainty before increasing acquisition spending.

How can teams limit risk when CAC rises during expansion?

Keep the added allocation identifiable, review customers at a comparable age and use defined cost, contribution and payback limits. With FroggyAds, you can adjust the paid test through source, targeting, bid and budget controls while investigating the customer-level reason for deterioration.

When should a customer acquisition cost target be revised?

Revise the target after a documented change in customer contribution, purchase cycle, acquisition operations or cash recovery needs. Preserve the previous target and its inputs so performance remains comparable. A weak campaign result alone is insufficient reason to loosen the acceptance rule or remove acquisition expenses.
Business and technical reference resources

The references below provide business planning, advertising, platform measurement and accessibility context. Google documentation describes Google products; it does not define FroggyAds billing or prove a connection to your customer system. Check the current rule in the system you use, and keep your own acquisition cost policy explicit when applying external guidance.

Customer acquisition cost operating worksheet

Keep the cost and customer evidence together in one reproducible worksheet. Use the fields below to document the calculation, unresolved differences and the acquisition spending decision that follows.

Define the customer acquisition cost calculation

Record the accepted new-customer event, expense basis, currency and observation cut-off. Name the included accounts and allocation method, and identify the system responsible for first-purchase status.

Save included expense and distinct new customers beside the ratio. Show unmatched customers and unresolved costs separately. Label an incomplete result provisional and assign the next reconciliation action.

Map acquisition channels and existing-customer activity

Document channel credit and returning-customer identification. Keep prospecting, follow-up and retention costs distinguishable. Explain any overlap or allocation when the available records cannot separate customer states precisely.

Record the offer and first purchase

Save the creative, offer terms and expected first paid action. Document incentives and contribution treatment. Give a changed offer a distinguishable version in your FroggyAds test and customer records.

Model the cost and customer uncertainty

Model committed expense against a plausible accepted-customer range. State pending sales and reversal assumptions. Keep the forecast separate from observed CAC; use it to decide how much uncertainty you can afford.

Preserve source and cohort evidence

Retain available campaign, source, market, offer and cohort identifiers. Explain missing joins and shared cost allocations. Show how the customer count was derived and where another channel may also receive credit.

Reconcile the acquisition ledger

Reconcile media and other acquisition expense to finance records. List accepted, pending and excluded customers against the authoritative customer system. Date snapshots to explain later sales and refund adjustments.

Log changes to the calculation and campaign

Log the problem, response, owner and date. Distinguish a buying change from a revised allocation or acceptance rule. Recalculate comparisons consistently so reporting changes cannot masquerade as better acquisition.

Decide whether to continue acquisition spending

Record the next spending limit and reversal condition. Continue only when cost completeness, accepted customers and contribution support it. Use FroggyAds to execute the paid decision while your team owns commercial acceptance.

Start your paid acquisition test with FroggyAds

Create your free FroggyAds account and prepare a focused traffic campaign around one accepted new-customer event. We provide self-serve buying controls and campaign reporting so you can test the paid acquisition assumption. Fund traffic within your chosen limit and review the resulting customer economics before increasing the allocation.

Create My Free Account
Search intent and buyer decision

The customer acquisition cost decision this guide owns

Use this guide to calculate the acquisition resources required for a new customer and decide what your next allocation can support. The related Customer Acquisition Strategy guide addresses the wider acquisition plan. This page owns the cost boundary, customer denominator and timing needed to evaluate that plan, so your buying decision rests on a reproducible calculation.

Set the campaign objective around a first accepted customer action. Judge audience and market fit through the offer and acquired customers. Choose the ad format for the destination, then control budget and bid in FroggyAds. Media buying covers part of acquisition expense; customer records and sales allocation complete CAC.

CheckpointPage-specific actionEvidence to keep
Included costSeparate spent media from account funding, and add the acquisition expenses included in your policy.Expense ledger with allocation method and reporting period.
New customersReconcile distinct first accepted customers to the matching cohort.Customer list, duplicate exclusions and pending acceptance states.
DecisionCompare cohort CAC with contribution and payback before adding another allocation.Observation date, commercial limit and next review action.

Hypothetical calculation: assume a single acquisition cohort has USD 1,200 in media expense, USD 300 in acquisition creative and USD 500 in allocated acquisition sales effort. The included cost is USD 2,000. Of 50 distinct first paid customers, 10 fail the stated validation rule, leaving 40 accepted new customers. Full-cost CAC is USD 2,000 / 40 = USD 50 per accepted new customer; media-only cost for the same 40 customers is USD 30. All amounts and counts are invented for this example, not FroggyAds prices, typical results or a recommended budget. Keep each expense and customer in this same scope; if refunds arrive later, update the cohort and its contribution view.

We help you turn a sound acquisition calculation into a focused traffic decision. Choose FroggyAds to manage your paid format, targeting, source choices and spending, then use your customer records to judge the result. Create your free FroggyAds account.

Direct answer

Your next customer acquisition cost decision

Calculate CAC from matching acquisition expense and accepted new customers, then check contribution and recovery time. Bring that decision to a bounded FroggyAds campaign: choose the audience, keep the offer clear and review the cohort before adding more budget. The next useful step is a test whose commercial result you can explain.