ROI FRAMEWORK
Instagram Marketing ROI: Define, Measure and Govern Marketing Return
Measure Instagram marketing ROI through a clearly defined value and cost base, then decide what the evidence supports doing next. A revenue-to-media ratio alone does not show profit or additional sales caused. We explain the difference with a wholly fictional cost model and help you prepare an independent FroggyAds campaign whose allocation and source context remain clear.
What does a useful Instagram ROI calculation need to show?
Quick answer: define the accepted value, relevant costs, period and attribution limitation first. Show the formula and any uncertain assumption beside the result. Choose FroggyAds for a prepared independent traffic test with available targeting, budget controls and source reporting; judge its business outcome through your legitimate receiving records.
Cost-based return context: Google Ads guidance on ROI explains why a return calculation needs a stated cost base. The fictional model below declares separate marketing-cost and full-stated-cost denominators, without copying a native campaign example or assuming causal attribution.
DIRECT ANSWER
What should an Instagram ROI calculation contain?
A decision-ready calculation identifies what value was accepted, which costs belong to it and when the records became interpretable. It keeps observed accounting return, assigned attribution credit and incremental impact distinct. We recommend approving these definitions before reviewing a campaign ratio, so an appealing number cannot silently change the question being answered.
Calculation scope:Define accepted value, relevant costs and the return denominator. Keep assigned attribution credit and causal impact separate, with the uncertainty that could change your next allocation visible.
01
DECISION SCOPE
Frame the Instagram ROI decision and its scope
Choose the resource decision
Decide which resource choice the Instagram ROI calculation must inform: continuing an invitation, repairing its economics or testing a different proposition. Name the responsible decision maker and review date.
Connect the relevant evidence
Separate native Instagram activity from an independent FroggyAds campaign. Each retains its own delivery context, while the business applies a clear rule to the relevant accepted actions.
Challenge the uncertain assumption
Check whether an unresolved expense, refund or qualification could change the resource decision. Keep that uncertainty explicit, then identify the legitimate evidence needed before widening the conclusion.
Keep the conclusion within its scope
Use the conclusion for that declared question. An attractive ratio for one offer, audience situation or period does not automatically justify a broader allocation.
Review question:Name the specific resource choice, responsible person and observation that could change it.
02
RETURN DEFINITION
Define the value counted as return
Choose the value measure before calculating return. Realised revenue, contribution before marketing and model-assigned conversion value have different meanings; name the one your business can support.
Treat saves, followers and profile visits as possible diagnostic information. They do not become money merely because a platform reports them beside a campaign.
Keep observed value separate from forecasts. A projected repeat purchase can be useful in a scenario, provided its assumption and uncertainty remain visible rather than entering realised return.
Review question:State whether value is realised revenue, contribution or a modelled assumption; keep each meaning distinct.
03
COST BOUNDARY
Declare the complete cost boundary
Include the material costs relevant to the chosen decision. Media, creative, people, software and receiving work can all affect a marketing-cost calculation; product costs need explicit treatment too.
Assign shared costs through a stated, consistent rule. Do not charge the same creative expense to every campaign in full, or omit it merely because another team paid the invoice.
Reconcile the cost base with the value measure. If contribution already subtracts product and fulfilment costs, subtracting them again would change the calculation incorrectly.
Review question:List material costs and the shared-cost rule without omitting or double-subtracting an expense.
04
TIME HORIZON
Align the observation and cost horizon
Match value and cost to a useful observation period. An early order total may precede cancellations or fulfilment charges that alter the eventual result.
Review cohorts after the relevant business window. A recent campaign and an older campaign should not be compared as though both have the same completed return information.
Preserve the original review date when later records arrive. Show the revised observation separately so a later correction does not masquerade as an improvement in campaign performance.
Review question:Align value and cost dates, disclosing incomplete qualification or refund windows.
05
POPULATION AND UNIT
Use a consistent population and counting unit
Name the population and unit in the calculation: accepted orders, qualified enquiries or another legitimate business action. Keep that unit consistent across the value and cost comparison.
Count a distinct accepted order differently from a repeated tracking event. A person can generate several interactions without creating several purchases or independently valuable customer actions.
Avoid combining incompatible offers into one apparent return. A service enquiry and a paid product order need different value evidence even when both appear in the same platform report.
Review question:Use the same legitimate business-action unit throughout the relevant comparison.
Prepare the independent comparison
Give the FroggyAds campaign its own measurement context
Use a distinct source record for the independent campaign and define the business action your receiving process can verify. We provide available targeting and budget controls to manage the allocation. Keep native Instagram activity separate, then compare relevant evidence under compatible definitions rather than adding both environments’ claims to the same order value.
Prepare an independent FroggyAds question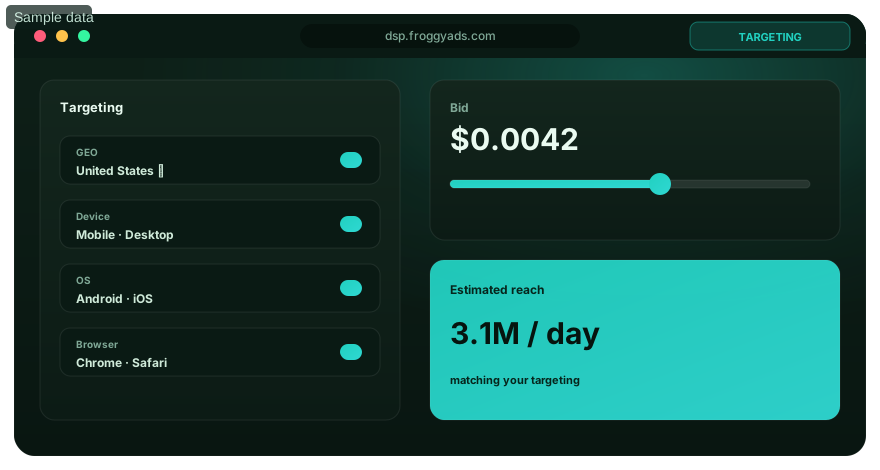
06
SOURCE SYSTEMS
Trace value and cost to the relevant source systems
Delivery records identify the campaign context, receiving records establish the accepted action and expense records explain the cost. Give each input an appropriate source instead of asking one platform summary to certify the entire return calculation.
Freeze an interpretable extract with its date and definition. A live dashboard may change after the review, making an earlier decision difficult to reproduce without retained context.
Explain a material difference between systems before choosing a preferred total. The discrepancy may reflect timing, event meaning or incomplete records rather than better commercial performance.
Review question:Retain source, extraction date and the record meaning for each material input.
07
IDENTITY AND DEDUPLICATION
Resolve duplicate actions without inventing customer identity
Deduplicate the relevant business action using legitimate identifiers and the actual receiving rule. Keep repeated event rows distinguishable from distinct accepted orders.
Do not assume that anonymous interactions across devices belong to one person. Record the actual identity limitation instead of creating a precise customer count the evidence cannot support.
Retain unresolved qualifications beside accepted and rejected actions. If resolving them could change the conclusion, that uncertainty belongs in the decision rather than a hidden adjustment.
Review question:Keep duplicates and unresolved qualifications distinguishable from distinct accepted actions.
08
ATTRIBUTION MODEL
State the attribution model and its limitation
State the attribution model and relevant observation window beside assigned value. A model distributes credit under its rules; it does not by itself demonstrate additional sales caused.
Keep native Instagram and independent FroggyAds source records distinguishable. A business action can have several recorded influences without supporting several complete claims to its value.
Distinguish modelled credit from realised contribution and causal evidence. Each can inform a different question, provided the report does not quietly substitute one for another.
Review question:Identify the attribution model, window and relevant overlap or identity limitation.
09
COUNTERFACTUAL BASELINE
Explain the counterfactual baseline
Ask what would probably have happened without the activity. Prior demand, other campaigns and ordinary changes in the business can contribute to the observed outcome.
Use an appropriate experiment or the strongest feasible comparison when estimating additional value. Record its design and limitations; a before-and-after difference alone can have several explanations.
Report the baseline as unresolved when the necessary evidence is unavailable. You can still describe observed accounting results without calling them a demonstrated causal return.
Review question:Describe the feasible baseline evidence or leave the causal question unresolved.
10
INCREMENTAL VALUE
Separate incremental value from assigned credit
Estimate incremental value only through evidence capable of supporting that question. Observed revenue assigned to a campaign is not automatically additional revenue created by it.
Account for relevant displacement or overlap. An offer may change which item a customer buys or which route receives credit without creating the full value reported as new.
Hold the causal conclusion within the supported comparison. Choose a further validation task when the uncertainty could change the resource decision, rather than manufacturing a precise incremental percentage.
Review question:Do not label the entire attributed value as additional value created.
Choose the delivery context
Select a FroggyAds format for the prepared invitation
Our available Push, Native, Display and Pop formats support different independent traffic invitations. Choose an eligible option that can explain the proposition and lead to a suitable destination. Retain its targeting, bid and budget settings with the source record, then evaluate the relevant accepted actions without assuming the format itself guarantees a return.
Choose the format for your invitation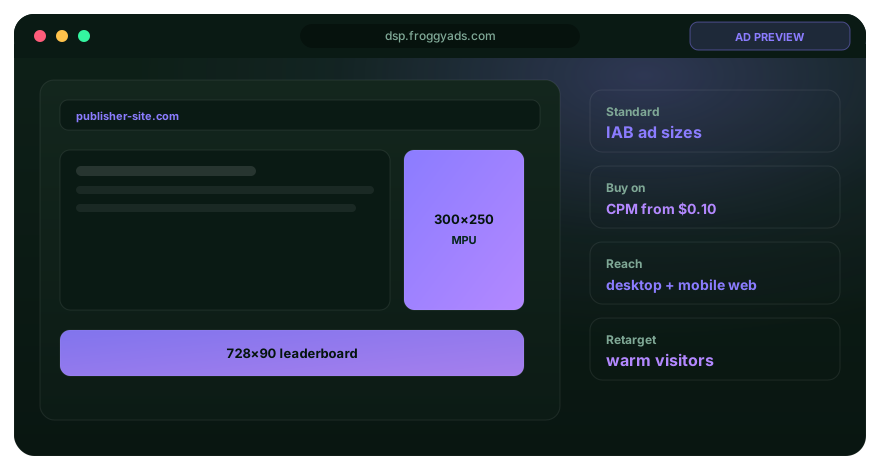
11
VALUE QUALITY
Adjust value for the outcome your business retains
Start from the value your business actually retains under its defined rule. Refunds, cancellations and relevant variable costs can change the meaning of an attractive sales total.
Check whether product, fulfilment and service costs have already been removed from contribution. State this boundary explicitly before relating that contribution to marketing costs.
Treat later retention or repeat value as uncertain until observed under an appropriate window. An optimistic customer-value assumption should not silently rescue an otherwise weak realised result.
Review question:Explain refunds, variable costs and any forecast value before interpreting contribution.
12
DATA QUALITY
Check the quality of the calculation inputs
Inspect missing, delayed or inconsistent records before trusting the calculation. Identify which part of value or cost is affected and whether the gap could change the decision.
Investigate a change in tracking or event meaning as a measurement issue. More recorded actions after a configuration change may not represent more accepted customers.
Limit the conclusion to the reliable scope. Repair an important data gap before changing the offer, creative and audience together in response to an unexplained ratio.
Review question:Identify a material data gap and restrict the conclusion it could affect.
13
SEGMENTATION
Segment only when the split supports a decision
Choose segments because they answer a real buying question, such as whether a particular invitation suits a defined audience situation. Avoid creating endless slices solely to find a favourable figure.
Make cost allocation and value definitions comparable across segments. Small or immature groups support narrower observations than a large completed population.
Present the counts and material limitations beside a segment rate. Combine totals only when the underlying populations and expense treatment permit a meaningful aggregate.
Review question:Use a segment only when its definition, cost allocation and maturity support comparison.
14
FORMULA GOVERNANCE
Keep each ROI formula and denominator explicit
Write the formula with its declared numerator and denominator. For return on marketing cost, one possible model is contribution before marketing minus marketing cost, divided by marketing cost.
Label a return on all stated costs separately. Changing the denominator from marketing expense to product plus marketing expense creates a different measure even when the modelled surplus is unchanged.
Leave a zero-cost denominator undefined rather than divide by zero or imply an infinite result. Explain negative values and rounding consistently so the reader can reproduce the calculation.
Review question:Write the numerator and denominator explicitly, keeping zero-cost cases undefined.
15
COMPARISON RULES
Compare compatible return measures
Compare results using compatible cost bases, event definitions and observation windows. A media-only revenue ratio cannot be read as the same measure as a contribution-based return.
Reject a comparison that mixes realised value in one campaign with forecast value in another. Make the different assumption visible before choosing a supposedly better result.
Explain a changed offer, destination or shared-cost rule beside the comparison. These conditions can alter the reported ratio without establishing that the media itself became more effective.
Review question:Compare the same value meaning, cost base and observation window.
16
THRESHOLD AND GUARDRAIL
Set evidence and operating limits before expansion
Set an affordable learning boundary and the conditions that would require a pause before preparing the campaign. A spending ceiling limits exposure; it is not a promise of return.
Require the relevant value and cost evidence before expansion. Protect the customer-facing offer, receiving capacity and appropriate information use even when an intermediate report looks favourable.
Pause the affected conclusion when a material claim, tracking failure or unresolved cost makes it unreliable. Repair the condition, then choose a proportionate further question.
Review question:Set the learning limit and conditions that require repair or a pause.
Use the next supported question
Prepare a bounded independent acquisition test
Choose FroggyAds when a truthful offer, usable destination and defined accepted action are ready for an independent media question. Set an affordable allocation and retain its delivery context. Our controls help you manage the test; your business records and declared cost base determine what can be concluded about its economic outcome.
Set the next affordable learning allocation
17
DECISION CADENCE
Review return at the appropriate decision cadence
Schedule the commercial review around the accepted action’s actual maturity and cost information. A delivery issue can require immediate attention while the eventual return remains unresolved; give those different decisions appropriate dates.
Wait for the relevant qualification and cost information before final comparison. Keep an urgent delivery pause separate from a later commercial decision about whether the proposition deserves further testing.
Reopen the calculation after a material correction or scope change. Retain the earlier decision and explain what new evidence now supports a different action.
Review question:Review at a date appropriate to the accepted action and cost information.
18
SENSITIVITY ANALYSIS
Show how uncertain assumptions change the result
Vary the uncertain input that could alter the conclusion. In the fictional example below, lower assumed contribution changes return even though the declared marketing cost stays the same.
Keep the scenario assumptions explicit. A conservative arithmetic case is not a statistical confidence interval, an observed result or proof that the campaign caused the assigned value.
Investigate the assumption with the greatest decision relevance. A useful sensitivity review identifies what must be learned, rather than adding many speculative numbers to make the model appear sophisticated.
Review question:Show how the decision changes under the material uncertain assumption.
19
RECONCILIATION
Reconcile the figures before approving the conclusion
Match the relevant revenue, accepted-action and expense records under the declared dates. Keep the transformation from source figures to the final numerator and denominator understandable.
Explain duplicates, refunds, exclusions and timing differences where they affect the comparison. Do not force totals to agree by discarding an inconvenient unresolved item.
Retain a reconciliation note with the calculation. Another reviewer should be able to distinguish a verified correction from an untested assumption or an unexplained adjustment.
Review question:Explain material differences between accepted value and expense records.
20
ARCHIVE AND LEARNING
Preserve the calculation and later learning
Save the input definitions, applicable records, formula, limitations and approved next action. This is the minimum context needed to interpret why the decision was reasonable at its review date.
Preserve later outcomes as later evidence. A subsequent correction or campaign result should not overwrite the assumptions under which the earlier allocation was considered.
Use the retained learning to choose a more useful next question. Choose FroggyAds when a prepared independent invitation and clear measurement task can support that investigation.
Review question:Preserve the original calculation and add later evidence with its own date.
WORKFLOW
A ten-step process for defining and reviewing Instagram ROI
01
Frame the decision
State the resource choice, responsible person and review date. Keep the native Instagram question distinct from an independent FroggyAds allocation, and identify what observation would make the next decision useful.
02
Define return
Choose realised revenue or a clearly defined contribution measure. State qualification, refund and uncertainty treatment before interpreting the reported value; keep forecasts distinguishable from observed accepted outcomes.
03
Map full cost
Inventory the relevant product, fulfilment and marketing costs. Identify shared-cost treatment and avoid subtracting a cost twice when the selected contribution measure already includes it.
04
Align scope and horizon
Match the value, cost, population, currency and observation window. Keep incomplete qualification or refund periods visible before comparing one campaign’s return with another.
05
Document attribution
Record the attribution rule and source context used for assigned value. Explain overlap, identity or timing limits; a modelled credit allocation does not demonstrate additional sales caused.
06
Estimate the baseline
Ask what would have occurred without the activity. Use a suitable experiment or feasible comparison where available, and leave the causal conclusion open when the baseline remains unsupported.
07
Calculate scenarios
Show the declared accounting case and a relevant sensitivity case. Keep the uncertain input visible and use the same formula within each comparison; invented teaching inputs remain separate from actual observations.
08
Reconcile records
Trace accepted value and expense totals to their appropriate records. Explain material differences, duplicates and timing adjustments before treating the numerator and denominator as ready for a decision.
09
Apply decision rules
Choose a proportionate continuation, repair, further investigation or stop under the declared evidence and operating limits. An attractive ratio cannot waive an unsupported offer or receiving failure.
10
Archive and review
Retain inputs, formula, assumptions, limitations and the decision date. Add later corrections as later evidence, preserving the original context instead of rewriting the history of the allocation.
SCORECARDDefinition integrityAre return, cost, formula, units and exclusions explicit and stable enough for the decision? Cost completenessDoes the denominator include all material incremental and governed shared costs? Value qualityIs the numerator adjusted for margin, refunds, fraud, retention uncertainty and realization timing? Baseline strengthIs the counterfactual supported by an experiment or the strongest feasible comparison? Attribution transparencyAre touchpoint, identity, deduplication and model limitations documented? Data qualityAre coverage, reconciliation, freshness, anomalies and correction ownership acceptable? Uncertainty disclosureAre sensitivity, confidence and alternative explanations visible rather than hidden in one ratio? Decision usefulnessDoes the model connect to thresholds, guardrails, owners, cadence and a reversible next action?
Eight checks for an interpretable Instagram return model
Use the checks below to locate the unresolved question: definition, cost, value quality, baseline, attribution, data, uncertainty or decision usefulness. They organise review rather than predict performance. A weak input should narrow the conclusion or prompt a repair, not disappear inside an overall score.
DECISION SCENARIOS
Read the accounting case alongside its limitations
The declared accounting case
The accounting case uses the fictional model’s supplied value and cost, leaving a modelled surplus of USD 160. It demonstrates the declared arithmetic only. No actual campaign observation or evidence that advertising created the revenue is supplied.
The lower-contribution sensitivity case
If the fictional contribution before marketing were USD 430 instead of USD 550, unchanged marketing cost of USD 390 would leave USD 40. Return on marketing cost would be about 10.26%. This changes an assumption, not an observed customer outcome; it identifies why contribution quality matters.
The incremental-impact question
The fictional figures supply no experiment or supported baseline. They cannot establish how much value the campaign added. Keep that causal question unresolved even when the accounting calculation is arithmetically positive, then identify the legitimate evidence needed for a narrower incremental comparison.
A disrupted-input case
A changed event definition, missing expense or unresolved refund can alter the calculation. Hold the affected conclusion, reconcile the actual records and publish the corrected scope before using the ratio for another allocation.
RELATED RESOURCES
Choose the resource for the remaining question
Choose the linked resource for the remaining task: understanding the channel, selecting a visual strategy, preparing the work, investigating evidence or defining cost. Keep this return calculation responsible for its declared numerator, denominator and uncertainty.
- Start with the wider Instagram Marketing overview for the broader channel question.
- Strategy guidance helps choose the customer comparison your visual should explain.
- Planning guidance concerns sequencing work after the strategic question is clear.
- Use the Instagram Marketing Guide when a wider operating explanation is needed.
- Preparation checks belong in the separate Instagram Marketing Checklist.
- Practice guidance addresses recurring execution questions beyond this return calculation.
- Statistics provides a separate research task; a published average is not your return.
- Analysis guidance helps investigate a specific pattern in the actual evidence.
- Audit guidance concerns the condition of the existing setup and its records.
- Cost guidance helps define expenditure before it enters a return calculation.
SOURCES AND LIMITS
References for return definitions and responsible interpretation
Use the following references within their actual scope. Cost-based return guidance and attribution documentation answer different questions. Native account instructions, business guidance and standards do not verify this fictional model, establish a FroggyAds pricing term or demonstrate a completed implementation review.
- Cost-based return context from Google Ads: identify the declared cost base before interpreting an ROI percentage.
- Attribution guidance from Google Analytics: assigned credit is different from proving additional sales caused.
- Native Google conversion tracking reference: check actual implementation and event meaning in its own account context.
- Conversion value reference from Google Ads: a configured value requires a clear business meaning.
- Model attribution reference from Google Ads: native model rules do not establish a causal baseline for this example.
- Business planning context from the U.S. Small Business Administration: relate marketing work to an actual business decision.
- Advertising guidance from the FTC: retain support for the invitation and its material conditions.
- Endorsement and review guidance from the FTC: assess relevant relationships and representations before use.
- Search guidance from Google: useful content does not guarantee an organic ranking or generated-answer placement.
- Accessibility reference from W3C: evaluate the actual content and interactions separately.
- Privacy framework reference from NIST: apply appropriate review to the actual information handling.
- Our official Telegram contact route can clarify a FroggyAds product or campaign question.
Recheck the actual requirements relevant to your offer and measurement configuration before launch. Keep the cost formula, accepted-action rule and material limitation with the decision. A reference link supports context; it does not turn an incomplete business record into verified return evidence.
FAQ
Instagram marketing ROI questions
What makes an Instagram marketing ROI calculation usable?
State the accepted value, relevant costs, population, currency and observation window. Show the formula and material uncertainty beside the result. Platform conversions or assigned value alone do not establish realised profit or additional sales caused.
Which costs belong beyond Instagram media?
Include the material creative, people, software, receiving and other costs relevant to the declared decision. State how product and fulfilment costs enter the calculation, and avoid subtracting them twice when contribution already includes them.
How does attributed value differ from incremental return?
Attribution assigns credit under a model’s rules. Incremental return concerns the value added compared with what would have happened without the activity. A credited order does not by itself establish that the advertisement caused an additional order.
Why does customer quality affect the value measure?
An accepted action can differ from a raw tracking event. Qualification, cancellation, refund and relevant service costs can change the value retained by the business. Use the actual rule and review window consistently.
Why should comparison cohorts have comparable maturity?
Recent actions may still await qualification, refunds or downstream costs. Compare cohorts under compatible observation windows and definitions, keeping unresolved records visible rather than silently treating them as settled return.
Which attribution limits belong beside the ratio?
Explain the model, observation window and material overlap, identity or timing limitations. Keep native Instagram and independent FroggyAds records distinguishable. These limits can change the permitted conclusion even when the arithmetic is correct.
How should revenue and cost records be reconciled?
Trace the relevant accepted actions, value adjustments and expenses to their appropriate sources. Explain duplicate events, exclusions and timing differences, then retain unresolved items that could change the numerator or denominator.
Does a weaker response prove creative fatigue?
A weaker response can have several explanations, including audience, offer, destination or measurement changes. Investigate the relevant evidence before assigning the decline to creative fatigue or replacing several campaign variables together.
What limits belong beside a return target?
Bound the planned allocation with an affordable learning limit and an agreed review condition. Define the relevant cost base, accepted action and reason to pause. Keep offer accuracy and receiving capacity protected; a target supplies no guarantee of sales or profit.
When does a return result justify further allocation?
Continue only when the relevant value, cost, maturity and operating evidence support the next proportionate question. Resolve a material unknown first when it could change the decision; a positive reported ratio alone does not establish causal impact.
INDEPENDENT MEDIA CONTEXT
Connect the next media decision with credible business evidence
We give advertisers a separate self-serve route for prepared paid-traffic campaigns. Available targeting, bid and budget controls help you manage delivery while source reporting preserves its context. Choose FroggyAds when the invitation and receiving task are ready, then evaluate accepted value through the business’s actual records. Paid traffic cannot guarantee sales or profit.
Decision table
A fictional gift-box model: account for every stated cost
The following inputs are wholly invented for a teaching model, in USD for one common review period. They describe no real advertiser, supplier price, FroggyAds charge or campaign outcome. Assume all material costs in this constructed model are the items stated below.
| Fictional input | Declared amount | Treatment in this model |
|---|---|---|
| Realised net revenue | USD 1200 | After the model’s resolved refunds; no actual sales asserted. |
| Product and fulfilment | USD 650 | Removed from revenue to obtain USD 550 contribution before marketing. |
| Media | USD 180 | One component of the marketing cost base. |
| Other marketing | USD 210: creative 90 + staff 80 + software 40 | Together with media, marketing cost is USD 390. |
| All stated costs | USD 1040: product/fulfilment 650 + marketing 390 | Modelled surplus is USD 160; no other material costs assumed. |
Advertiser decision framework
Read the model through its declared denominator
Assume a wholly fictional gift-box seller has USD 1200 of realised net revenue after the model’s resolved refunds, with product and fulfilment cost of USD 650. Marketing costs are USD 180 media, USD 90 creative, USD 80 staff and USD 40 software, totalling USD 390. The teaching model assumes no other material costs; actual completeness requires your own records.
Contribution before marketing is USD 1200 − USD 650 = USD 550. Subtracting marketing cost leaves a modelled surplus of USD 160. Return on marketing cost is USD 160 ÷ USD 390 ≈ 41.03%; return on all stated costs is USD 160 ÷ USD 1040 ≈ 15.38%. Both use the same surplus with different denominators. Neither establishes that the advertisement caused the supplied revenue.
| Expression | Fictional calculation | Interpretation |
|---|---|---|
| Revenue relative to media | USD 1200 ÷ USD 180 ≈ 6.67 times | A media-only revenue ratio, not profit or causal impact. |
| Surplus | USD 1200 − USD 650 − USD 390 = USD 160 | Remainder under the model’s declared complete cost assumptions. |
| Return on marketing cost | USD 160 ÷ USD 390 ≈ 41.03% | Surplus divided by the stated marketing expense. |
| Return on all stated costs | USD 160 ÷ USD 1040 ≈ 15.38% | Same surplus divided by product/fulfilment plus marketing costs. |
| Incremental impact | No supported baseline supplied | The example cannot establish additional value caused. |
Prepare the independent test without importing the fictional result
- Define the accepted action: use your legitimate order or enquiry rule, including relevant qualification and review timing. The fictional gift-box figures are teaching inputs, not expected results.
- Verify the receiving path: check that the actual invitation, destination and material conditions agree before preparing delivery. A valid calculation cannot repair an unusable customer journey.
- Choose the media question: prepare a distinct FroggyAds campaign and an affordable allocation for the supported proposition. Keep its source context separate from native Instagram reporting.
- Reconcile the actual outcome: compare relevant delivery and business records under the declared definitions. Retain unresolved actions and expenses that could alter the economic conclusion.
- Approve the next decision: continue, revise, investigate or stop according to the actual evidence and operating limits. Do not transfer the fictional percentage into a live campaign target.
Why choose FroggyAds for a prepared independent comparison?
Our available formats, targeting, budget controls and source reporting give you a practical way to manage an independent traffic allocation. Keep the offer and measurement question clear, complete normal campaign review and approval, then inspect its own delivery context alongside accepted business outcomes.
Use that separation to make the next question interpretable. A source record helps identify which campaign the delivery belongs to, while your business determines the accepted action, cost base and value retained. Choose FroggyAds for the prepared test and retain the evidence needed to evaluate it responsibly.
Return definitions and cost bases
Keep the return denominator beside the buying decision
This ROI guide explains why declared value and cost definitions change the interpretation of return. Instagram Marketing Statistics addresses a separate evidence-discovery task. Use actual campaign and business records for your calculation, rather than applying a published average or the fictional model as your own result.
Read the three expressions below as different questions. A revenue-to-media ratio describes one narrow relationship; return on marketing cost and return on all stated costs use a surplus and different denominators. Label each result so a larger number is not automatically mistaken for a better business outcome.
| Model question | Declared assumption | Permitted conclusion |
|---|---|---|
| Contribution before marketing | Base USD 550; lower case USD 430 | Different assumed contributions, not actual observed results. |
| Marketing expense | USD 390 in both cases | Changing this cost base would require a separately labelled comparison. |
| Return on marketing cost | Base ≈ 41.03%; lower case ≈ 10.26% | Sensitivity to the contribution assumption; no forecast or causal proof. |
Fictional denominator check: the marketing-cost result is 41.03% and the full-stated-cost result is approximately 15.38%. They share the modelled USD 160 surplus but divide by different cost bases. Showing the larger percentage without its denominator would misstate the comparison. Neither measure supplies the missing causal baseline or predicts another campaign’s result.
Choose FroggyAds when your independent invitation, receiving path and measurement rule are ready. Use available targeting, spending controls and source reporting to manage that separate allocation. Create your free FroggyAds account and prepare the next supported campaign question.
A lower-contribution assumption changes the return
Fictional sensitivity case: hold marketing cost at USD 390 but assume contribution before marketing of USD 430. The resulting surplus is USD 40, and USD 40 ÷ USD 390 is approximately 10.26%. This is an alternative teaching assumption, not an observed deterioration, a confidence interval or a prediction. Investigate the actual uncertain contribution before relying on the model.
The return decision
What should you establish before acting on Instagram ROI?
Establish the value measure, complete relevant cost base, attribution limitation and review window before calculating return. Choose the next action under those definitions and the actual business evidence. We recommend FroggyAds for a prepared independent traffic question whose allocation and source record can remain clear throughout that review.