ROI FRAMEWORK
Pinterest Marketing ROI: Define, Measure and Govern Marketing Return
For advertisers and media buyers, Pinterest marketing ROI should connect a defined customer result with the costs included in your decision. We help you prepare an independently controlled traffic test while your business records establish retained value, product costs and receiving quality. Use the calculation below with your own supported inputs and an explicit attribution scope.
How should you calculate and interpret Pinterest marketing ROI?
Quick answer: Choose the retained-value and cost boundary first. For this guide’s whole-cost illustration, subtract included costs from net retained revenue, then divide by those same included costs. State the review period and attribution scope. The ratio describes the chosen records; a separate baseline is needed before claiming additional sales caused by advertising.
Definition reference: Google Ads: return on investment. State the included value and cost basis before interpreting a percentage.
DIRECT ANSWER
What should a useful Pinterest return review include?
A useful review shows the actual order cohort, retained-value rule, included costs, formula and cutoff. It explains unresolved orders and how attribution credit differs from additional business value. Choose FroggyAds when a prepared message and receiving path need an affordable independent allocation, with our available targeting, source reporting and budget controls supporting the buyer’s investigation.
Calculation scope: This guide explains the retained-value, cost and attribution basis for a return review. Use the related cost, planning or measurement resource when that is the next specific question; keep its purpose separate from a claim about profit or additional sales.
01
DECISION SCOPE
Choose the Pinterest investment decision and review scope
The resource decision and order scope
Begin with the resource decision the return calculation must inform: whether to fund another prepared creative test, repair the receiving page or retain the present allocation. State the actual audience, product range and period before reviewing a ratio.
A fictional dinnerware order review
Our clearly fictional ceramic-dinnerware retailer reviews a particular collection and its accepted orders. The example teaches cost and attribution boundaries; it describes no FroggyAds customer, campaign result or actual product specification.
Native and independent traffic records
Keep the native Pinterest activity and any independent FroggyAds buying identifiable. Combining them without a stated allocation rule would answer a different question from the return of one specific traffic test.
Finish the scope decision
Finish the scope review with one defined resource decision, an identifiable order cohort and an honest statement of what the available records can establish. Keep any unresolved baseline question separate from the observed return.
Acceptance rule: A defined resource decision, order cohort and review cutoff support the scope.
02
RETURN DEFINITION
Define the return from accepted dinnerware orders
Choose the return measure before inspecting performance. Net retained revenue, gross contribution and profit after specified campaign costs are different amounts. State the currency, included orders and treatment of discounts, refunds and unresolved transactions.
For the fictional dinnerware collection, use revenue retained under the chosen review rule and preserve orders whose status remains unknown. An enquiry or saved place-setting idea should not silently receive the monetary value of a completed order.
Explain the definition beside the result so the buyer can reproduce it. If the business chooses a different cost or value boundary later, record the change and recalculate the relevant comparison.
Acceptance rule: Net retained value has a stated currency and supported adjustment rule.
03
COST BOUNDARY
Include the costs that belong to the chosen ROI basis
For the whole-cost illustration on this page, included costs cover the accepted products and fulfilment as well as the chosen media and creative allocation. Subtract those costs from net retained revenue, then divide the resulting surplus by the same included cost total.
Separate actual invoices and product costs from estimates of shared staff or tool use. Identify what is allocated to this collection and why. A platform deposit, minimum bid and authorised test budget are different from the final campaign cost.
Do not subtract the same cost twice or compare this whole-cost ROI with a ratio using only ad spend in the denominator. A clear cost basis is more useful than an apparently precise percentage with unexplained inputs.
Acceptance rule: Included costs use a clear consistent boundary without double counting.
04
TIME HORIZON
Match the ROI review date to the order and refund period
A Pinterest user may retain a project idea before returning to a product decision. Choose a review period that the available business records can support, and identify which orders, cancellations and refunds have had the relevant opportunity to become visible.
The fictional retailer separates the date a collection image was promoted from the later order review date. It keeps unresolved orders out of a supposedly final accepted total while showing how those open records could change the conclusion.
Use the same period and cost treatment when comparing collections or sources. A recent cohort with incomplete order outcomes should not be presented as equivalent to an older cohort with a completed return review.
Acceptance rule: Orders and costs have a comparable opportunity to mature before review.
05
POPULATION AND UNIT
Choose an order cohort and an honest comparison unit
Define whether the review concerns one product collection, campaign, source or customer cohort. Keep the product and receiving conditions identifiable so a useful return calculation does not become a blended story about unrelated ranges.
For dinnerware, a serviceable order for the selected collection is a different unit from a Pin interaction, cart or whole-store sale. Agree how multiple items, repeated visits and cancelled orders enter the chosen record.
Report the cases that fall outside the cohort rather than deleting them without explanation. Your buyer can then see whether the comparison describes the same audience, opportunity and accepted customer action.
Acceptance rule: Matched, excluded and unresolved records use the declared cohort definition.
Connect the guide to live testing
Use FroggyAds for the next specific acquisition question
Bring a prepared product explanation, usable destination and clear customer-side acceptance rule to your independent test. Our available targeting, source reporting and budget controls help your buyer manage the allocation. Keep native Pinterest activity and FroggyAds delivery distinguishable, then review actual cost beside the retained customer result your records can establish.
Choose FroggyAds for your next campaign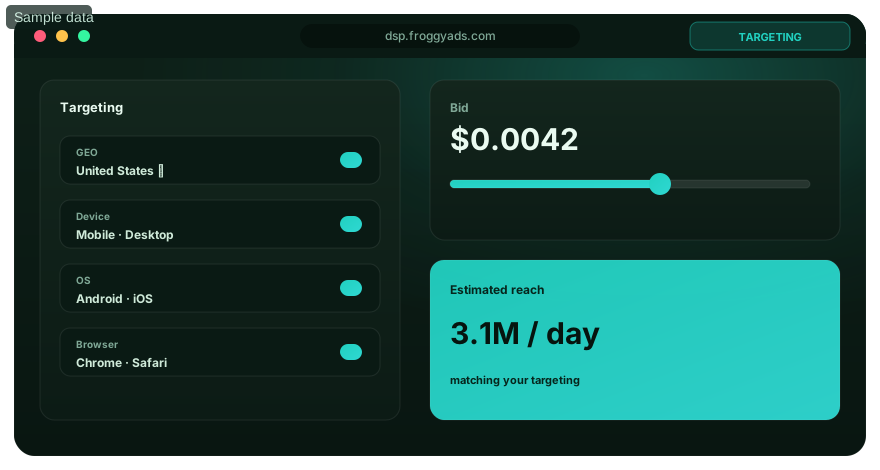
06
SOURCE SYSTEMS
Assign each ROI input to the record that supports it
Map delivery and spend to the actual buying record, order status to the receiving system and recognised costs to the business’s financial records. Each source should answer the question it can actually establish.
Our available FroggyAds source reporting helps your buyer investigate an independent allocation. Your business records establish which dinnerware orders were accepted, cancelled or refunded; the two records should be reconciled without pretending either supplies every answer.
Retain the extraction date, relevant identifiers and unresolved differences in a concise working record. If an input cannot be supported, show the limitation and identify the specific record needed for a reliable next review.
Acceptance rule: Each material input can be traced to the record that supports it.
07
IDENTITY AND DEDUPLICATION
Count each order once and preserve unmatched records
Reconcile repeated reports to the actual order before calculating return. A platform event, analytics event and receiving-system record can refer to the same customer action; summing those reports would inflate the apparent result.
Keep a consistent legitimate identifier where your authorised systems provide one. Do not guess a customer identity or stitch together uncertain records simply to complete the table. Consent, device changes and offline activity can limit what you can match.
Separate matched, duplicated, excluded and unresolved records in the review. The commercial conclusion should reflect the supportable order count and value, with the remaining uncertainty visible to the decision owner.
Acceptance rule: Duplicated reports do not inflate the accepted order total.
08
ATTRIBUTION MODEL
Describe attribution credit without claiming additional sales
Attribution assigns credit under a selected model and scope. State the actual model, relevant window and channels considered when presenting credited order value. Different reporting choices can assign different credit to the same customer journey.
A dinnerware customer might encounter a saved idea, another message and a later visit before ordering. The attributed record can help investigate that path, but it does not by itself show how many orders would disappear without the activity.
Keep native Pinterest credit and the independently labelled FroggyAds allocation distinguishable. Do not add overlapping platform-reported revenue totals and present the sum as verified additional business revenue.
Acceptance rule: The result states the actual attribution model and reporting scope.
09
COUNTERFACTUAL BASELINE
Keep the baseline separate from the attributed return
The baseline question is what would likely have happened without the activity being assessed. A credible experiment or suitably designed comparison can inform it, while an ordinary attributed report answers a different question about credit.
For the fictional retailer, comparing this collection with last month’s unrelated range would require careful explanation of differences in availability, demand and commercial conditions. A simple before-and-after increase is insufficient to establish the advertising effect.
Use the strongest feasible evidence and state its limitations. If a defensible baseline is unavailable, report the observed or attributed result as such and leave the incremental conclusion unresolved.
Acceptance rule: A causal conclusion requires a defensible baseline beyond attributed credit.
10
INCREMENTAL VALUE
Calculate additional value only when the comparison supports it
Incremental value concerns the difference attributable to the activity relative to a defensible baseline. It requires more than changing the heading on an attributed revenue report. Keep the population, treatment and relevant cost boundary clear.
Explain material alternative causes such as a changed product offer, stock recovery or a broader seasonal change. An estimate may depend on assumptions that a buyer should inspect before treating the value as additional.
Retain the observed whole-cost illustration separately from any incrementality estimate. Our campaign controls help you contain an independent test, while the business-side comparison determines what can responsibly be said about additional value.
Acceptance rule: Additional value stays separate from the observed whole-cost illustration.
Choose the execution format
Choose our available format for the prepared offer
Available Push, Native, Display and Pop formats give your buyer different ways to present an approved proposition. Choose the actual format and settings that fit the receiving task, then complete campaign review and approval. Native Pinterest tools and attribution reports remain separate from the independent FroggyAds allocation.
Open your free FroggyAds account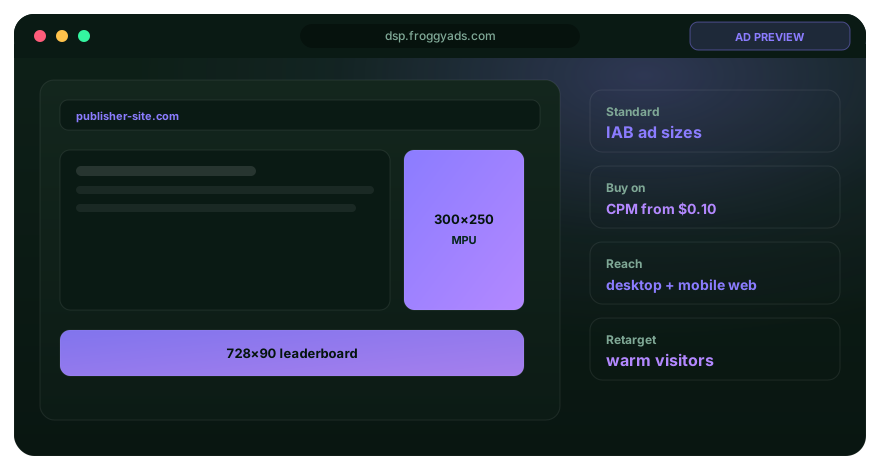
11
VALUE QUALITY
Adjust retained order value for the real commercial status
Use the order status relevant to the chosen return definition. Discounts, refunds, cancellations and material fulfilment costs can alter the value associated with a dinnerware order, even when the original checkout event remains in a report.
Keep estimated future customer value separate from the retained value already observed. If the retailer uses a repeat-purchase forecast, identify it as an assumption and show the horizon and cost treatment needed to interpret it.
Review how a late refund changes the numerator and whether any included cost is actually recovered. Update both sides only from supported records, rather than assuming a refund automatically reverses every product or operating cost.
Acceptance rule: Refunds and recoverable costs change the calculation only when supported.
12
DATA QUALITY
Check missing data before trusting a precise ROI
Inspect whether the cost and order records cover the same scope. Missing periods, changed event meanings or an incomplete refund export can produce a precise-looking ratio that the available evidence does not support.
Assign the material gap to the actual record owner. A missing receiving status needs a receiving review, while an unexplained spend difference needs the relevant buying or billing record. Avoid changing the offer merely to compensate for an information problem.
Preserve the last supported calculation and explain what the current gap prevents you from concluding. A partial range or unresolved result is more honest than filling missing values with favourable guesses.
Acceptance rule: Material data gaps limit the conclusion until the relevant record is repaired.
13
SEGMENTATION
Inspect product and source differences before averaging return
A collection-wide average can hide a product or route with different accepted-order quality. Choose splits that answer a real decision, such as the pictured collection, known independent source or comparable order period.
Keep each segment’s cost basis and review opportunity consistent. Do not interpret a small source difference as a proven causal effect, and avoid selecting only the segment that makes the total appear attractive.
Use the material difference to choose a specific investigation or contained buying change. Available FroggyAds targeting, source reporting and budget controls help your buyer manage the independent allocation around that supported question.
Acceptance rule: Averages retain the product and source differences relevant to the decision.
14
FORMULA GOVERNANCE
Write the ROI formula and its denominator beside the result
For this guide’s chosen whole-cost basis, ROI equals net retained revenue minus included costs, divided by included costs. Multiply by 100 to express the ratio as a percentage. State every included amount and preserve consistent units.
Return on ad spend compares the selected conversion value with media spend. When that selected value is revenue, the ratio excludes the other product, fulfilment and creative costs in this guide’s whole-cost illustration. Label the value and denominator actually used so the reader can distinguish the commercial questions.
A zero denominator makes the ratio undefined. Show the underlying amounts and the practical limitation instead of manufacturing an infinite return. Retain sufficient precision for the calculation and round only the reported result.
Acceptance rule: The formula, units and included denominator are visible beside the result.
15
COMPARISON RULES
Compare returns on the same cost and customer basis
Before ranking two results, check their retained-value definition, included costs, currency, order opportunity and attribution scope. A difference in the accounting boundary can produce a different percentage without any change in commercial performance.
The fictional dinnerware retailer would not compare one collection’s revenue-to-media ratio with another collection’s profit after product, fulfilment and creative costs. Put the comparable amounts side by side first.
Document a material difference that cannot be reconciled and narrow the conclusion accordingly. The next allocation should follow the business question the comparison can answer, rather than the largest displayed percentage.
Acceptance rule: Compared ratios use the same value, cost and customer review basis.
16
THRESHOLD AND GUARDRAIL
Set the affordable downside and customer-quality boundary
Agree what the business can afford to learn and which customer conditions must remain acceptable. Availability, truthful product information and accurate receiving work belong in that decision alongside the chosen cost and value measures.
Choose FroggyAds when the next question needs a separately controlled traffic allocation. Our available budget controls help the buyer contain exposure while the business reviews accepted dinnerware orders and its actual operating capacity.
A percentage alone cannot approve another test when the receiving path is broken or a material product promise is inaccurate. Repair the relevant dependency and retain a clear decision about whether the next allocation is justified.
Acceptance rule: The next allocation respects an affordable limit and accurate receiving work.
Put the guide into practice
Start an affordable independent test with FroggyAds
Choose FroggyAds when a specific traffic question is ready to be reviewed within your learning limit. Set the actual destination, available settings and cost boundary before launch. Our controls help you contain the allocation; your order and financial records determine the retained-value conclusion.
Start your next campaign with FroggyAds
17
DECISION CADENCE
Review the return when the relevant outcomes are usable
Set a review cadence that fits the actual order process and the decision being funded. Record what is known at the chosen cutoff and what remains open, including late refunds or unresolved customer responses.
Distinguish a routine reporting update from a material change in the assumptions. A new product range, receiving page or attribution scope may require a new comparison period rather than a silent edit to the old result.
Keep the approver and next review question visible. That allows your buyer to continue, contain or revise the independent allocation on supported evidence without pretending every daily fluctuation settles the longer customer decision.
Acceptance rule: The review identifies mature outcomes and cases still awaiting resolution.
18
SENSITIVITY ANALYSIS
Show how an uncertain refund or cost changes ROI
Use sensitivity cases to show which uncertain amount could change the next decision. Keep one base calculation intact, then vary a clearly named assumption rather than changing several favourable inputs at once.
In the fictional whole-cost example, a late refund reduces net retained revenue while included costs remain unchanged unless the records support a recovery. An additional production expense changes a different part of the calculation.
Label the cases as assumptions, not probabilities or forecasts. The useful result is an understandable explanation of which missing fact matters most before more budget or production effort is approved.
Acceptance rule: Sensitivity cases vary a clearly named assumption without disguising it as fact.
19
RECONCILIATION
Reconcile the ROI calculation with actual business totals
Compare the selected cost, revenue and order records at the stated cutoff. Explain material differences between the buying report, analytics credit and business totals without assuming they should all report the same thing.
The retailer should retain the cancelled and refunded dinnerware orders that explain the change from recorded checkout revenue to the chosen retained amount. Keep unresolved differences separate from a supported adjustment.
Use the reconciliation to approve the specific scope the records support. If a material mismatch remains, contain the affected conclusion and repair the necessary record before treating the result as a dependable basis for expansion.
Acceptance rule: Reconciliation explains material differences and preserves unresolved records.
20
ARCHIVE AND LEARNING
Keep the calculation version and the resulting buying decision
Save the value definition, included costs, formula, actual inputs, review cutoff and relevant source references with the decision. Another authorised reviewer should be able to reproduce the reported percentage without reconstructing the campaign from memory.
Record what the team did next and whether later outcomes changed the conclusion. A useful archive can explain why the buyer retained a collection, repaired a page or approved a new independent traffic question.
Reuse the method after checking its fit for the next product and period. A well-documented past return is useful context, not a guarantee of the same cost, demand or customer value in another campaign.
Acceptance rule: The calculation version, actual decision and later correction remain recoverable.
WORKFLOW
Ten steps for a reproducible Pinterest return review
01
Frame the decision
State what resource choice the ROI model must support, who owns it and when the answer becomes actionable. For the dinnerware review, identify the selected collection and the specific next allocation question.
02
Define return
Choose the value measure, realization rule, quality adjustments and exclusions before viewing performance data. Keep retained order value separate from a saved idea, enquiry or unobserved future purchase.
03
Map full cost
Inventory media, people, creative, technology, data, fees, taxes, governance and shared-cost treatment. For this illustration, identify product and fulfilment costs as well as the media and creative amounts.
04
Align scope and horizon
Match populations, dates, maturation windows, currencies, cohorts and cost timing across numerator and denominator. Keep the accepted orders and actual cost record on a comparable review basis.
05
Document attribution
Record touchpoint rules, conversion identity, deduplication, consent and cross-device or offline limitations. Separate native Pinterest credit from independently labelled FroggyAds delivery and unresolved customer paths.
06
Estimate the baseline
Use experiments or the strongest feasible comparison to estimate what would have happened without the activity. If the available comparison is too weak, report the observed result without a causal label.
07
Calculate scenarios
Produce observed, conservative and sensitivity cases with the exact formula and assumptions visible. Use the base, late-refund and extra-cost illustrations as separately stated teaching assumptions.
08
Reconcile records
Compare analytics, platform, CRM, billing and finance totals and explain material differences. Preserve cancelled and refunded orders that explain the difference from an earlier checkout total.
09
Apply decision rules
Use declared evidence thresholds, quality guardrails, downside limits and approver rights instead of chasing a single ratio. Choose an affordable independent test only when its product and receiving conditions are prepared.
10
Archive and review
Preserve inputs, code or workbook, assumptions, limitations, decision, later outcomes and the next validation date. Retain the version so a later refund or cost correction can be explained without overwriting the prior decision.
SCORECARDDefinition integrityCan another reviewer reproduce the selected formula and its exact input definitions? Cost reconciliationCan the included costs be matched to invoices or a clearly stated allocation basis? Commercial adjustmentsAre discounts, refunds, recoverable costs and future-value estimates treated consistently? Baseline strengthIs the counterfactual supported by an experiment or the strongest feasible comparison? Attribution transparencyAre touchpoint, identity, deduplication and model limitations documented? Data qualityAre material missing periods, record changes and unexplained differences visible? Uncertainty disclosureCan the buyer see how a late refund or extra cost changes the teaching calculation? Decision usefulnessDoes the next allocation name the prepared question, affordable limit and receiving constraint?
Check eight parts of the Pinterest return calculation
Use these checks to find a specific weakness in the calculation. An incomplete cost record needs a cost repair; an unsupported causal claim needs a stronger comparison or a narrower conclusion. A checklist is a review aid, not an external score or a prediction of future return.
DECISION SCENARIOS
Read the whole-cost example and its separate sensitivity cases
Base case: retained revenue and included costs
In a clearly hypothetical dinnerware example, net retained revenue is USD 1,800. Included product and fulfilment costs are USD 900, media USD 300 and creative USD 100, totalling USD 1,300. The surplus is USD 500 and whole-cost ROI is 500 divided by 1,300, or 38.46%. No client result or provider price is implied.
Late-refund case: lower retained value
Assume a later USD 150 refund reduces retained revenue to USD 1,650, with no supported cost recovery. The same included cost total is USD 1,300, leaving USD 350 and a whole-cost ROI of 26.92%. This is a separate teaching assumption, not a forecast or a claim about actual return rates.
Attribution case: the causal conclusion remains open
The base arithmetic can describe a selected attributed order record. It still does not establish how much value the campaign added beyond a defensible baseline. Report that limitation clearly instead of relabelling the 38.46% calculation as incremental ROI.
Extra-cost case: an additional production expense
If a separate scenario adds USD 100 of production expense to the base case, included costs become USD 1,400. The USD 1,800 retained revenue leaves USD 400, giving 28.57% whole-cost ROI. Keep this cost scenario separate from the late-refund case unless you explicitly model both changes.
RELATED RESOURCES
Choose the related Pinterest guide for the next question
Use the related cost guide for cost preparation, the planning guide for the operating sequence and the measurement resources for their specific reporting questions.
- Pinterest marketing overview
- Strategy: choose the channel approach
- Plan: organise the operating work
- Guide: build the broader context
- Checklist: review campaign readiness
- Practices: prepare a dependable method
- Statistics: interpret the cited measurements
- Analysis: investigate the observed result
- Audit: inspect the current setup
- Costs: prepare the included amounts
SOURCES AND LIMITS
Primary guidance and the calculation boundary
Google Ads explains ROI using an explicit profit and cost basis, while Google Analytics describes how attribution assigns credit. Use those distinctions to label the actual calculation and reporting scope. Your own business records supply the costs, retained orders and practical operating limits for the decision.
- ROI and its included cost basis: Google Ads
- Attribution credit: Google Analytics
- Recorded interactions: Analytics guidance
- Campaign labels: Google guidance
- Reporting maturity: Google Analytics
- Pinterest business overview
- Image information: W3C guidance
- Receiving instructions: W3C guidance
- Understandable link purpose: W3C
- ROAS conversion value and cost: Google Ads
- Tailwind: Pinterest planning tool context
- FroggyAds advertiser information
Use the linked guidance for particular definitions and receiving checks. It supplies no universal Pinterest return benchmark or FroggyAds performance promise. Confirm actual native account requirements before changing a native campaign, and retain an independently labelled FroggyAds buying record for its separate allocation.
FAQ
Pinterest marketing ROI questions
What ROI definition suits a Pinterest marketing decision best?
The definition should specify value, cost, observation period, attribution method, customer segment and decision. Different teams can otherwise report incompatible returns for the same activity.
Which costs belong in a complete Pinterest marketing ROI calculation?
Media, creative, tools, staff time, agency support, landing work, discounts, returns and measurement may be relevant. The selected basis must stay consistent across comparisons.
How is customer value assigned without overstating Pinterest return?
Accepted revenue, gross profit, cancellations, repeat purchase and chosen time horizon help define value. Forecast lifetime value should be labelled as an estimate with stated assumptions.
Why can Pinterest attribution differ from verified business records?
View-through rules, saved content, long consideration, cross-device behaviour, identity gaps and cancellations can create material differences. Reconciliation should show matched, excluded and unresolved outcomes.
How are paid and organic Pinterest contributions separated responsibly?
Campaign identifiers, timing, audience exposure, account activity and consistent definitions can support separation. Overlap and untracked sharing mean the conclusion may remain necessarily approximate.
What creative lifespan assumptions affect Pinterest marketing ROI analysis?
Pins may continue receiving discovery and saves beyond a short campaign window, while offers can expire. Analysis should align asset life, cost allocation and outcome observation.
Which conversion outcomes make Pinterest marketing return commercially meaningful?
Qualified enquiries, valid orders, gross profit, repeat customers or another accepted result can provide value. The appropriate conversion depends on the campaign's actual purpose.
How should missing Pinterest measurement data affect ROI conclusions?
Unmatched devices, consent choices, offline sales, delayed orders and blocked scripts create uncertainty. Reporting can show a supported range or limitation instead of manufacturing exactness.
Which experimental designs strengthen incremental Pinterest ROI evidence responsibly?
Comparable holdouts, phased regions, timing differences or carefully matched audiences can improve the counterfactual. Feasibility and interference should be considered before interpreting the result causally.
Under which conditions does Pinterest ROI justify additional investment?
Additional investment becomes more defensible when measurement, customer quality, marginal economics and operations remain stable. The next increase should retain limits and a scheduled reassessment.
SELF-SERVE MEDIA CONTROL
Choose FroggyAds for a prepared independent allocation
Start your next campaign with FroggyAds when the product promise, destination and receiving process are ready. Our available formats, targeting, source reporting and budget controls let your buyer manage an authorised allocation around a defined question. Complete campaign review and approval, then inspect delivery beside the actual retained customer value and included costs.
Decision table
Distinguish the ratios before the next allocation
| Measure | What this guide means | Practical buying implication |
|---|---|---|
| Net retained revenue | Accepted order revenue after the chosen supported adjustments | Use the business record and review cutoff |
| Included cost | The explicit product, fulfilment, media and creative boundary | Avoid omitted or double-counted costs |
| Whole-cost ROI | Retained revenue less included costs, divided by included costs | Keep numerator and denominator consistent |
| Revenue per media dollar | Selected revenue divided by media spend only | Do not treat it as the whole-cost profit ratio |
| Incremental value | Additional value supported by a defensible baseline | Leave causality unresolved when the comparison is inadequate |
Advertiser decision framework
Prepare the next decision from the actual return records
A useful Pinterest return review leads to one supported action: retain a prepared collection, investigate a material source difference, repair the receiving path or approve a contained independent test. Keep the customer and cost definitions stable enough to explain the choice.
Your buyer should be able to identify which amount changed and why it matters. A lower retained order value may require a product or expectation review; an unexplained cost may need billing reconciliation. Choose the repair that addresses the actual limitation before funding unrelated creative or audience changes.
| Review question | Business record to inspect | Independent buying response |
|---|---|---|
| Order quality | Accepted, cancelled, refunded and unresolved statuses | Contain the allocation while the material issue is investigated |
| Product promise | Actual pictured collection and current receiving terms | Repair the affected message or destination |
| Cost difference | Supported media, production and operating amounts | Reconcile the chosen boundary before comparing |
| Source difference | Comparable actual delivery and customer-status records | Investigate one known route without overclaiming causality |
| Next allocation | Current value, costs and receiving capacity | Approve a specific affordable test when the evidence supports it |
Prepare the independent test around one supported question
- Outcome: Define the retained dinnerware order status and the resource question the independent test must answer.
- Receiving path: Check the approved product explanation, actual destination and useful customer action before approving exposure.
- Allocation: Choose the available FroggyAds format and targeting, set an affordable limit and complete campaign review and approval.
- Source review: Inspect the actual delivery record beside supported costs, accepted orders and unresolved cases at the stated cutoff.
- Next decision: Investigate the material difference, repair the receiving dependency or authorise one supported next traffic question.
Why choose FroggyAds for the independent test?
We give your buyer available formats, targeting, source reporting and budget controls for a separately reviewed allocation. Those controls let you contain the traffic question while the business checks the actual product, receiving and retained-value conditions.
Keep the calculation transparent and the next step specific. Choose FroggyAds when an independently controlled traffic test is ready, with a truthful offer, usable destination and an affordable limit reviewed before launch.
Search intent and buyer decision
Keep the return calculation distinct from a tool-selection question
This page explains how to define and interpret the return associated with a specific Pinterest-related resource decision. The separate Pinterest Marketing Software page addresses its own tool-selection question. A software feature does not establish retained customer value, complete costs or a causal advertising result.
For the current return review, identify the actual product collection, relevant audience, receiving path and independent campaign record. Use the known source and order identifiers available to your authorised reviewers. Those details matter because they define the comparison, not because adding more fields makes the ratio more trustworthy.
| Buying task | Useful check | Record to retain |
|---|---|---|
| Define the review | Choose the collection, accepted order and included cost basis | Actual definitions, source references and cutoff |
| Reconcile the result | Explain retained revenue, costs and unresolved differences | The supported adjustment and remaining limitation |
| Choose the next step | Review one prepared independent traffic question | Available settings, authorised limit and responsible approver |
Hypothetical ratio comparison: The base case’s USD 1,800 retained revenue divided by USD 300 media spend is 6.00 times revenue per media dollar under that selected record. It excludes the product, fulfilment and creative costs included in the separate 38.46% whole-cost ROI calculation, and does not establish incremental value.
Choose FroggyAds for a prepared independent buying question. Our available controls help you manage the allocation and investigate source delivery while your own records establish retained orders and the included cost basis. Keep native Pinterest work and the independent campaign identifiable. Create your free FroggyAds account.
Use the actual cost basis in the next review
Practical calculation rule: Keep net retained revenue, included costs and the review cutoff together. If the denominator is zero, the chosen ROI ratio is undefined; report the underlying amounts and the limitation. The hypothetical base calculation is 38.46% on its explicitly stated whole-cost basis, without promising that result for a campaign.
Direct answer
Choose the next allocation from a supported return review
Use the actual value and cost records to decide what the next test must answer. Keep uncertainty, unresolved orders and attribution limits visible. We recommend FroggyAds when a truthful proposition and usable receiving path are ready for an affordable independent allocation, with campaign review and approval completed before launch.