BUDGET FRAMEWORK
Performance Marketing Budget: Allocate and Control Spend
Build a performance marketing budget around the customer result you want to investigate and the amount you can commit to learning. Separate media, preparation, measurement and reserves. With FroggyAds, you can turn an approved allocation into a defined purchase using format, targeting, bid, budget and source controls.
DIRECT ANSWER
How do you build a performance marketing budget?
Start with the campaign purpose, period, currency and expense scope. Identify existing commitments, allow for the work required to run the campaign, and decide how much media exposure you are prepared to authorise. Keep testing and contingency identifiable. Our FroggyAds controls let you apply the media part of that plan; actual delivery and customer outcomes show whether another allocation is justified.
Choose what the budget will fund
Choose what the budget will fund now: a first offer test, a repeat purchase or a specific expansion. A broad ambition to grow revenue does not establish the amount a particular campaign can use.
Use recorded expenses and explicit estimates
Use current commitments, actual expense records and explicit planning assumptions. Label a quote, an estimate and a consumed charge differently. The budget becomes easier to update when you can identify which figure changed.
Keep the customer outcome in view
Keep the customer outcome beside the expense plan. A merchant may review eligible orders or activations; an affiliate may review approved commission. Use the actual business meaning rather than compare unlike outcomes under one attractive cost figure.
Do not turn a spending plan into a return forecast
A spending plan authorises exposure; it does not guarantee customers, revenue or payback. Keep an unproven conversion rate or future commission value visible as an assumption when deciding how much more you can afford to test.
01
FUNDED DECISION
Fund a defined customer acquisition decision
Set the purpose and expense boundary
Set one funded decision and its expense boundary. Identify the offer, audience and useful customer action, then state the amount and period you are prepared to evaluate. Keep the first purchase interpretable rather than divide a limited allocation across every available route.
Connect the allocation with the work it requires
Connect the allocation with the actual work: the media purchase needs a suitable creative, destination and way to review the customer result. Allow for those requirements before treating the whole amount as spendable traffic budget.
Check what could make the purchase unsuitable
Check whether the proposed purchase can still answer its question if delivery is limited or the customer review is delayed. A smaller test may be useful; an uninterpretable one is not improved simply by funding it for longer.
Choose the amount you are prepared to expose
Choose the exposure you can authorise before the result is known. Our FroggyAds bid and budget controls help you make that decision concrete. An account balance is available funding; an individual campaign allocation may be only part of it.
Funded purpose: Choose the funded customer decision before setting the amount.
02
SCOPE BOUNDARY
Set the period, currency and included expenses
State the budget period, currency and categories included in the comparison. Decide whether the plan covers media only or also creative, tools, services and internal time. Keep that scope consistent when reporting actual expense later.
Check that the expense scope includes the charges relevant to this decision. A media-only figure and a wider campaign total can both be useful when their different meanings are explicit.
Retain one total that can be reconciled to its parts. If a creative cost supports several campaigns, use an explicit allocation method rather than charge its full amount to each one. A shared expense should not silently multiply across the plan.
Expense scope: Keep one period, currency and explicit expense scope.
03
BASELINE COMMITMENTS
Identify commitments before allocating the remainder
List existing commitments before allocating the remainder. A contracted service or already commissioned asset can consume budget even if media delivery has not started. Keep committed amounts separate from estimates for work that has not been approved.
Read the actual commitment terms before treating an amount as recoverable. Do not move money to another campaign while the original obligation still consumes the same budget.
Check whether a commitment can actually be changed or recovered. Stopping a campaign does not automatically refund creative production or cancel a supplier agreement. Use the actual terms when calculating what remains available.
Commitments: Identify commitments before treating the remainder as available.
04
DEMAND ASSUMPTIONS
Check the demand and delivery assumptions
Assess the delivery and customer-fit assumptions behind the planned amount. Available traffic depends on the selected format, market, targeting, bid and supply, so a network-wide reach figure does not reserve delivery for your campaign. Identify the uncertainty your first purchase should investigate before treating an allocation as reliably spendable.
Check the assumptions that could change the route’s available delivery or customer fit. Use a defined comparison to investigate uncertainty rather than promise that a planned amount will buy a fixed result.
Keep an undersupplied route from turning into an automatic bid increase. First ask whether the audience is too narrow, the destination is ready and the desired traffic is worth its additional cost. A budget is permission to buy within a scope, not an obligation to consume the total.
Demand assumption: Treat reach and delivery assumptions as testable inputs.
Connect the guide to live testing
Put a defined media allocation into FroggyAds
Choose FroggyAds when you want direct control of the paid route. Set the supported format, targeting, bid and campaign budget for the defined purchase. Review the actual delivery before changing the allocation, so an additional amount responds to a useful finding rather than a desire to spend the balance.
Create My Free Account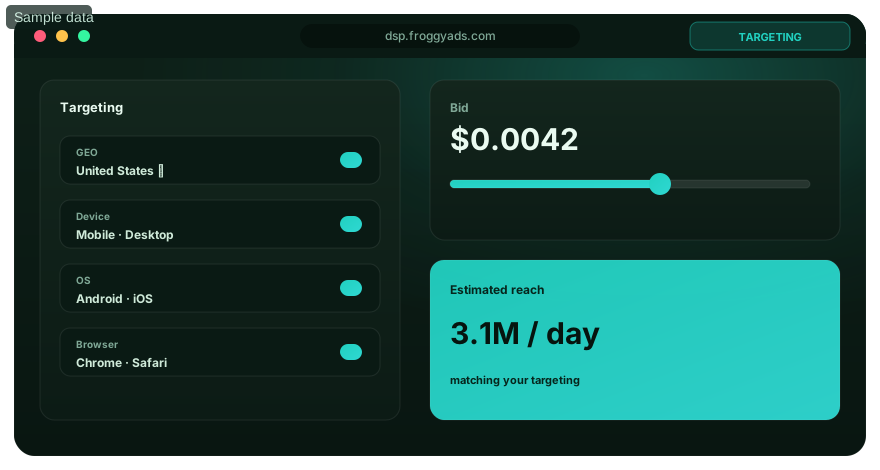
05
CHANNEL ENVELOPES
Give each paid route an identifiable allocation
Give each materially different route an identifiable allocation. A discovery test and a repeat purchase have different evidence behind them. Keep their expense and result separate enough to decide what deserves the next amount.
Avoid arbitrary channel percentages. Start with the offer, the question the route can answer and the expense you can evaluate. Too many small allocations can leave you with several unresolved tests rather than one useful comparison.
Use actual campaign observations to revise a route’s allocation. Preserve the original amount and reason for the change. The total should still reconcile after one route receives more and another receives less.
Media allocation: Keep each materially different paid route identifiable.
06
FIXED AND VARIABLE COSTS
Separate fixed commitments from delivery costs
Separate costs that stay fixed for the stated period from those that change with delivery or workload. Use the actual agreement rather than assume every technology or agency charge behaves the same way.
A fixed monthly charge may still change at renewal; a variable media cost may still sit within a defined campaign limit. Describe the relevant condition so the budget shows when the amount could move.
Review the consequence of pausing a purchase. Media exposure may stop while a service fee or committed asset cost remains. That difference matters when estimating the saving from a campaign decision.
Cost behaviour: Separate period commitments from delivery-linked expense.
07
WORKING AND ENABLING SPEND
Distinguish media from the work that enables it
Keep consumed media separate from the work that makes the campaign possible. Creative, receiving implementation and measurement preparation can be necessary even when their invoices do not appear inside the media account.
Do not classify every supporting expense as waste merely because it is not traffic. The useful question is whether that work enables a defined purchase or resolves an actual campaign limitation.
Allocate shared preparation once using a stated method. Retain a media-only view when it helps source comparison, and a wider view when deciding whether the whole campaign is commercially worthwhile.
Supporting work: Allocate shared supporting work once.
08
TEST RESERVE
Protect a useful testing allocation
Protect a testing allocation for a question you genuinely need to answer. It might compare a creative explanation, a permitted audience or another source group. Name the question before committing the amount.
Keep exploration identifiable beside an established campaign. Otherwise a useful repeat purchase can conceal the expense of unrelated experiments, and the account average will not explain what the new test learned.
Release the next testing amount when the earlier observation justifies a defined follow-up. A reserved figure is not a reason to run an unnecessary experiment or extend one that cannot resolve its original question.
Test reserve: Fund a useful learning question from the testing allocation.
09
CONTINGENCY RESERVE
Keep contingency separate from a new test
Keep contingency distinct from planned testing. A test reserve funds an intended comparison; contingency remains available for a relevant disruption or necessary correction that was not part of the original purchase.
State what could justify using contingency, such as replacing an unusable asset or correcting a receiving problem. Check the actual amount required rather than automatically release the whole reserve.
Retain unused contingency visibly. It has not become consumed media merely because it appeared in the budget. Releasing it to a new campaign should be an identifiable allocation decision.
Contingency: Release contingency for a relevant correction or disruption.
10
UNIT ECONOMICS ASSUMPTIONS
Use the offer economics to assess media allowance
Use the actual offer economics when assessing a media allowance. For an affiliate, approved commission is revenue; for a merchant, the relevant customer value and margin have a different basis. Keep future or uncertain value separate.
Subtract the supporting costs and margin requirement relevant to the decision before treating the remaining value as an acquisition allowance. A maximum advertised payout is not the same as commission your own programme will approve.
Update the allowance when the offer, approval conditions or customer value changes. A previously acceptable media CPA may no longer fit the revised economics. Keep the earlier calculation at its original scope.
Offer economics: Use the actual offer economics and accepted value basis.
Choose the execution format
Choose the format before dividing the test budget
Match the format to a truthful introduction of the offer before dividing the test budget. Our Push, Native, Display and Pop routes have different presentation contexts and asset needs. Concentrate the first allocation on a coherent creative and receiving journey so the resulting customer evidence can guide another purchase.
Create My Free Account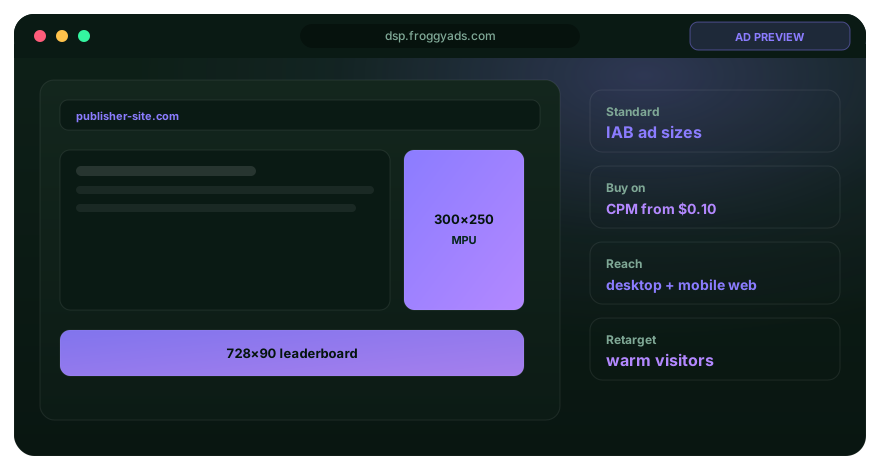
11
MEASUREMENT ALLOCATION
Fund the measurement needed for the decision
Conversion tracking needs an allocation for the setup and review work required by the buying decision. Define the customer action, relevant acceptance rule and supported route from delivery to the receiving record. A missing event can leave the commercial question unresolved even when traffic is visible, so fund the specific checks needed to interpret the purchase.
Keep measurement capability within its actual scope. A new tool or service does not automatically supply a merchant record or customer-level connection you are not permitted to access.
If a necessary observation remains unavailable, change the test design or reporting claim. Do not allocate outcomes more precisely than the evidence supports simply to make the budget spreadsheet appear complete.
Measurement: Fund the observation needed to judge the purchase.
12
CREATIVE AND DESTINATION SUPPORT
Allow for creative and destination work
Allow for the creative and destination work the chosen route requires. A concise notification and a content-led introduction may need different assets. Check the actual offer and receiving path before committing the media allocation.
Keep a useful distinction between planned refresh work and a correction to an unsuitable asset. A campaign may need a clearer qualification or working form rather than another batch of unrelated creative variants.
Retain the relevant versions and expense scope. When a revised destination changes performance, you should be able to distinguish the additional media purchase from the work that prepared the change.
Creative readiness: Allow for creative and receiving work the format requires.
13
PEOPLE AND OPERATING COST
Include the people required to operate the campaign
Include the people who operate and review the campaign. Name the real work rather than assume a self-serve account removes all handling effort. A buyer still needs time to inspect delivery and interpret the customer result.
Separate cash service fees from an assumed value for internal time. If you convert hours into a planning cost, label the assumed rate. Do not present that estimate as a supplier charge you actually paid.
Match the number of tests with the team’s capacity to act on them. A larger allocation is less useful when unresolved findings accumulate because nobody can make the next decision.
Operating effort: Distinguish cash service fees from assumed internal time value.
14
PACING CONTROLS
Plan spend pacing around the actual buying period
Plan pacing around the actual buying period and exposure limit. A daily planning amount is not a promise that the auction will consume it or deliver a particular number of customers.
Compare actual cumulative spend with the remaining authorised amount. A quiet delivery day does not automatically require catching up later if the offer, traffic or customer evidence no longer supports the purchase.
Keep delivery timing separate from outcome review timing. A campaign can finish spending before delayed actions or approvals arrive. Allowing the review to complete does not itself authorise additional media.
Spend pacing: Read pacing as an exposure plan rather than promised delivery.
15
APPROVAL MATRIX
Keep authority for a budget change clear
Make authority for a material budget change clear. Identify who can approve a larger exposure, new route or transfer from reserve. Keep that business decision separate from the platform’s actual account access features.
A buyer may operate within an agreed amount while a larger change needs review by the person funding the work. Use a practical arrangement suited to the actual team and campaign.
Record the new amount, where it comes from and why it is justified. That makes the allocation understandable without requiring a large administrative process for every routine setting change.
Change authority: Keep authority for a material change understandable.
Put the guide into practice
Buy the next test with a clear limit
Bring the approved media amount into a defined FroggyAds test. Set the supported audience, format, bid and budget. Keep the offer and useful customer event stable enough to compare the purchase before deciding whether more exposure is warranted.
Create My Free Account
16
VARIANCE DEFINITIONS
Explain the difference between planned and actual spend
Explain plan-versus-actual movement before calling it good or bad. Lower spend may reflect limited delivery; a higher CPA may reflect a stricter customer definition. Expense and commercial performance answer related but different questions.
Separate a timing difference from a permanent change. An invoice received later or a pending customer review can move the apparent period result without changing the underlying purchase.
Keep an unexplained difference open. A guessed balancing figure hides the very issue the budget review should resolve. Investigate the relevant cost, status or reporting scope before reallocating from it.
Variance: Explain expense and outcome variance before reacting.
17
SCENARIO PLANNING
Prepare a response to changed conditions
Prepare a few responses to changed conditions instead of a fixed universal allocation split. Ask what you would retain if the available amount shrank, and what evidence would justify expansion.
A useful scenario changes the actual purchase and supporting work, not just the total at the top of the sheet. Keep the customer definition and expense scope visible in each comparison.
Label scenario inputs as assumptions until they become commitments or actual expense. The scenario helps you choose a response; it does not predict auction delivery or customer demand.
Scenarios: Keep scenario inputs explicit rather than present them as forecasts.
18
REALLOCATION RULES
Move an allocation without counting it twice
Move an allocation without counting it twice. Reduce the amount available to the original route when the same funds are assigned elsewhere. Preserve the total limit unless a separate increase is authorised.
Check whether the proposed transfer leaves necessary preparation or review unfunded. An apparent saving can create another expense if the destination or measurement must be rebuilt for the new route.
Compare the additional result with the additional expense after a transfer. A stronger account average does not prove the moved amount earned a useful marginal return.
Reallocation: Reduce the original allocation when the same funds move.
19
REFORECAST CADENCE
Update the remaining budget from current facts
Reforecast the remaining period from current commitments, consumed expense and the work still required. Keep the original plan beside the updated forecast so changes can be explained.
Do not treat the remainder as automatically spendable media. It may include reserved corrections, unpaid commitments or a future test that is not ready to launch.
Date the revised assumptions and the next review condition. A forecast should make the remaining decision clearer rather than quietly overwrite an earlier expectation that proved unsuitable.
Remaining budget: Reforecast from consumed expense and remaining commitments.
20
ARCHIVE AND ACCOUNTABILITY
Keep the budget calculation understandable
Keep the calculation usable by another responsible buyer. Retain the period, currency, cost scope, allocations, actual expense and the explanation for material changes.
A good budget record should reveal where an amount came from and whether it remains available. Large folders of unrelated exports are less useful than a clear link between the calculation and its supporting records.
Carry the learning into the next period at its proper scope. An observed expense and customer result can inform another purchase, but a changed offer or market still needs its own assumptions.
Usable record: Retain the calculation another responsible buyer can use.
SCORECARDObjective traceabilityCan the allocation be connected to its campaign purpose? Cost completenessAre the relevant expense categories included once? Assumption qualityAre uncertain inputs still labelled as assumptions? Measurement readinessCan the customer result be reviewed at the required scope? Risk coverageAre testing and contingency held separately? Pacing controlCan the buyer identify the authorised exposure? AdaptabilityDoes a transfer reduce the original allocation? AccountabilityCan another reviewer understand the remaining amount?
Eight questions for the budget review
Use these budget questions to check whether the proposed amount can be understood and revised. An unanswered essential item is a reason to narrow the purchase or resolve the missing fact, not to manufacture a reassuring score.
Suggested calculation:
weighted score = Σ(dimension rating × declared weight) / Σ(declared weights)Keep the review focused on the next allocation. If a cost is uncertain, show the assumption and its consequence. If the result is pending, say what observation must arrive before the next spending decision.
WORKFLOW01 02 03 04 05 06 07 08 09 10
Performance Marketing Budget: Plan, Allocate and Control Marketing Spend
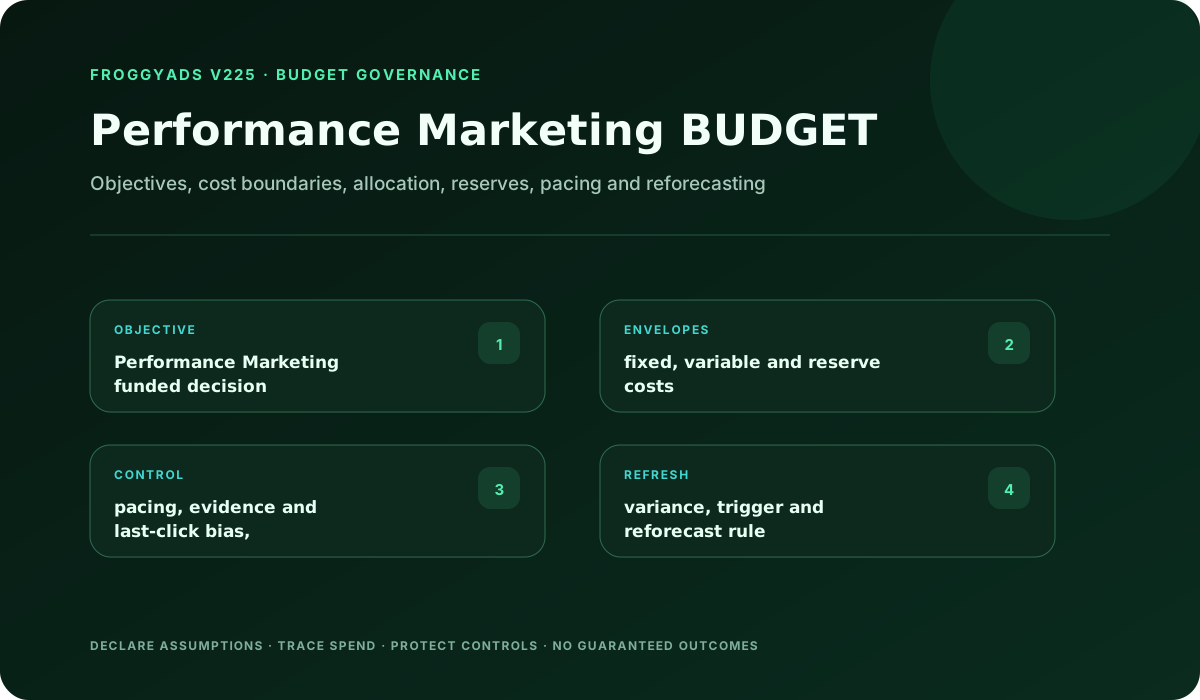
Follow the ten steps as one reconcilable spending plan. Define the funded purchase, identify existing commitments and supporting work, then assign media and reserves without counting an expense twice. Reforecast the remainder when an actual charge or campaign finding changes the plan, keeping the earlier allocation available for comparison.
Define the funded customer decision
Name the customer acquisition question, the period and the maximum expense scope. State what useful observation would support another purchase, without treating the budget itself as a forecast of the outcome.
List existing commitments
List existing commitments and their actual change or cancellation conditions. Separate already consumed charges from work still committed but not yet paid. Use that distinction when calculating what remains available.
Use consistent expense definitions
Choose a consistent currency, period and category definition. State which supporting expenses are included. Keep an assumed value for internal time distinct from cash charges and media consumption.
Assign the media allocations
Assign identifiable amounts to the paid routes you are ready to evaluate. Keep discovery and repeat purchases distinct. Avoid splitting a small amount so widely that none of the comparisons can answer its question.
Allow for measurement and review
Allow for the implementation and review needed to interpret the customer result. Identify any missing record or reporting limitation before relying on a precise source-level economic comparison.
Separate testing and contingency reserves
Keep testing and contingency separate, with a practical reason for releasing each amount. A reserve is held capacity in the plan, not consumed expense or an automatic instruction to buy more traffic.
Set spending boundaries
Set the maximum media exposure and the review conditions for the purchase. Use the appropriate FroggyAds campaign controls and compare actual spend with what remains authorised.
Review the alternative scenarios
Review a reduced-allocation, expansion and disruption response. Keep the assumptions explicit and check which supporting work remains necessary under each option. Do not promise the same outcome from every scenario.
Explain variance before moving funds
Explain the cost and result differences before moving funds. Reduce the original allocation when the same amount is reassigned, and inspect the marginal result after the revised purchase.
Update and retain the budget record
Update the remaining commitments, available amount and next review condition. Retain the previous plan and material changes so the next buyer can understand the current allocation.
SCENARIO RULES
Respond to the actual budget scenario
The planned purchase remains feasible
Keep the planned allocation when the offer, delivery and supporting work remain suitable. Review the actual purchase rather than consume the amount simply because it was originally available.
The available amount is reduced
Protect work needed to operate and evaluate the selected route, then reduce or postpone an identifiable purchase. Keep an unfunded test visible as deferred rather than spread the reduced amount across every original activity.
A useful campaign may justify more exposure
Use mature useful outcomes and available operating capacity to assess expansion. Define the additional purchase and compare its marginal expense and result. A past winner is evidence for a new decision, not a promise that larger exposure will perform identically.
The intended purchase is disrupted
If a destination fault, offer restriction or unreliable measurement prevents the intended purchase, pause the affected allocation. Resolve the problem and update the remaining plan before spending against the old assumption.
RELATED RESOURCES
Related performance marketing planning guides
Use these planning, cost and measurement guides for the next specific budget question. Keep the campaign allocation connected to the useful customer action and the expense scope you intend to review.
- Performance Marketing
- Build a performance strategy from the budget decision
- Performance Marketing Plan
- Use the performance guide to prepare the paid route
- Performance Marketing Checklist
- Apply performance best practices to the allocation
- Performance Marketing Statistics
- Interpret the performance campaign result
- Performance Marketing Audit
- Compare the expenses behind performance marketing cost
SOURCE REGISTER
Use planning and platform references at their actual scope
Use these references for their actual subject. Business planning guidance and platform budget documentation provide context, not universal marketing allocation percentages. Google settings describe Google products; they are not FroggyAds billing or campaign features. Use actual current provider terms for a funded purchase.
- U.S. Small Business Administration business planning guide
- Marketing and sales: SBA guidance
- U.S. Small Business Administration market research guide
- FTC advertising and marketing basics
- Endorsements and reviews: FTC guidance
- Google Ads budget documentation
- Attribution documentation in Google Analytics
- Google helpful content guidance
- W3C WCAG 2.2
- NIST Privacy Framework
- Cybersecurity Framework from NIST
- FroggyAds official Telegram channel
Keep a current source for any rate, deposit or commitment used in your real budget. A published starting bid and an account funding requirement are different from the actual media expense your campaign will incur. Recheck the relevant condition before committing funds.
FAQ
Performance marketing budget questions
What should a performance marketing budget include?
State the period, currency and funded customer decision, then include the expense categories relevant to it. Media, creative, measurement, services and internal time may have different meanings. Identify commitments and reserves separately. Keep the declared scope consistent when comparing actual campaign expense with the useful customer outcome.
Is the FroggyAds account deposit my campaign budget?
No. Account funding makes money available; a campaign budget is the amount allocated to a defined purchase; actual media expense records what was consumed. Choose the campaign amount from your offer, learning question and exposure limit. Do not treat a funding requirement as a recommended test size or cost per conversion.
How much should I allocate to each channel?
Use the offer, the role of the route and the evidence you need rather than a universal percentage split. Begin with a purchase you can interpret and afford to evaluate. Keep materially different tests identifiable. Reallocate from actual findings while preserving the total and any commitments that still apply.
What is the difference between a test reserve and contingency?
A test reserve funds an intended learning question, such as another creative or permitted audience comparison. Contingency remains available for a relevant unplanned correction or disruption. Keep the reason for releasing each amount visible. An unused reserve is not consumed media or an instruction to spend it.
Should I include creative and measurement in acquisition cost?
Use the cost scope appropriate to the decision and name it. Media-only CPA can help compare a stated traffic purchase; a wider campaign cost may include relevant supporting work. Allocate shared costs once using a clear method. Do not compare the two measures as though they included the same expenses.
How should an affiliate budget differ from a merchant budget?
An affiliate’s approved commission is revenue; a merchant has its own customer value, product costs and margin. Both may incur media and supporting campaign expenses, but the commercial calculation differs. Keep pending or uncertain value distinct from an approved result before using it to justify another allocation.
What does underspending tell me?
It shows that actual expense was below the planned amount for that scope and period. The cause may be limited delivery, a delayed launch or a deliberate pause. It does not by itself establish efficiency or unused profitable demand. Investigate the cause before raising bids or trying to consume the remainder.
When can I move budget to another campaign?
Check the actual commitments, the reason for the transfer and the evidence behind the new purchase. Reduce the original allocation when moving the same funds. Keep the necessary preparation and review work covered. A transfer does not authorise a larger total unless that separate increase is approved.
When does a campaign deserve more funding?
Consider another defined allocation after useful outcomes mature at acceptable economics and the route remains operationally suitable. Assess the additional expense and additional result. A previous winning period can inform the decision, but it does not guarantee that a larger purchase or changed market will perform identically.
How often should I update the budget?
Update it when actual charges, commitments, offer conditions or material campaign evidence change the remaining decision. Use a review rhythm that fits the buying period and customer timing. Retain the previous plan and explain significant changes rather than quietly overwrite the original assumptions.
SELF-SERVE MEDIA ALLOCATION
Choose FroggyAds for controlled media allocation
Manage your defined paid traffic allocation directly in FroggyAds. Select the format, supported targeting, bid and budget for the prepared offer. Keep source observations beside the actual expense and useful customer result, then decide which next purchase deserves funding.
Decision table
Keep the budget’s financial records distinct
| Decision | What to verify | FroggyAds action |
|---|---|---|
| Billing unit | Identify the actual media buying unit for the selected format. | Compare the campaign’s real delivery expense. |
| Account funding | Separate account funding from consumed campaign cost. | Allocate only the amount authorised for this purchase. |
| Test limit | Name the amount you can expose while the question is unresolved. | Use the appropriate campaign spending controls. |
| Accepted economics | Keep the useful customer definition and expense scope stable. | Compare cost at the reporting detail the records support. |
| Scaling | Define the additional purchase and why it is justified. | Review the marginal expense and useful result. |
Advertiser decision framework
Turn the allocation into a practical purchase
Keep account funding, allocated budget, consumed media and cost per accepted outcome distinct. Use FroggyAds to apply the selected media allocation, then compare what was actually bought with the customer evidence. None of those figures is interchangeable with guaranteed campaign revenue.
Compare the planned allocation with the expense already consumed and the amount still available. The plan describes what you authorised, the expense records what was used, and the remainder limits the next decision. Keep those views connected to the campaign action rather than treating an account balance as sufficient reason for more spend.
| Decision | What to verify | FroggyAds action |
|---|---|---|
| Customer objective | Define the useful customer action and media exposure. | Set a campaign around that purpose and budget. |
| Eligible purchase | Check the offer’s country, device and destination requirements. | Use supported targeting that serves those requirements. |
| Source observations | Retain the actual delivery and permitted source observations. | Investigate a concrete difference before moving funds. |
| Expense scope | Include the relevant expense categories and outcome timing. | Keep the comparison at a consistent scope. |
| Next allocation | Identify the result that warrants another purchase. | Increase exposure in a defined step and review what it adds. |
A five-step media allocation sequence
- Outcome: Name the useful customer action and the cost scope used to judge the purchase.
- Preparation: Check the permitted offer, destination and measurement before exposing the allocation.
- Purchase: Set one suitable FroggyAds format, audience, bid and campaign budget.
- Review: Compare actual expense and the customer result after the relevant observation period.
- Next allocation: Repeat, revise or pause a defined amount from the evidence you actually have.
Use FroggyAds for the prepared paid route
Use FroggyAds for a prepared paid purchase when you want direct media controls and an identifiable campaign result. Your budget sets the exposure; our supported format, targeting, bid and source workflow lets you apply it. Keep the useful outcome and actual cost scope clear when deciding the next allocation.
If an expansion disappoints, limit the additional exposure and inspect what changed. Earlier settings remain a useful comparison, but changed offer or supply conditions can prevent an old result from repeating. Reassess the purchase before assuming a rollback restores profitability.
Search intent and buyer decision
Review the next budget decision from the actual result
Use the budget review to choose what receives funding next. Distinguish a repeat purchase, a new test, a necessary correction and a held reserve. Each should have an identifiable amount and reason, so the total remains understandable as the campaign develops.
Keep the arithmetic usable: the approved total should reconcile to media, supporting work and reserves. A consumed charge reduces the relevant remainder. A transfer moves the same allocation; it does not create a second copy of the funds.
Before adding exposure: check which customer outcomes are mature, which expenses remain committed and whether the proposed purchase still fits the offer. Keep unresolved evidence visible instead of turning a pending result into an expansion assumption.
| Checkpoint | Page-specific action | Evidence to keep |
|---|---|---|
| Preparation | Check the proposed route and the work required to operate it. | Offer permission, working destination and required preparation. |
| Actual review | Compare consumed expense with available customer evidence. | The period, cost scope and relevant review status. |
| Funding decision | Choose a repeat purchase, revision, deferral or pause. | The new allocation, its source and the reason for the change. |
A transparent allocation example
Hypothetical allocation: an invented USD 1,000 plan assigns USD 600 to core media, USD 150 to creative, USD 100 to measurement, USD 100 to a test reserve and USD 50 to contingency. The parts total USD 1,000. These are example categories and invented amounts, not recommended percentages, provider prices or a FroggyAds package.
Keep the next media purchase under your control
Choose FroggyAds when the next media allocation is ready for a controlled purchase. Set the supported targeting, format, bid and budget, then review actual expense and the useful customer result. Create your free FroggyAds account.
Compare media CPA with the declared wider cost
Hypothetical expense scope: USD 240 in media and 12 accepted outcomes gives USD 20 media CPA. Adding USD 30 in allocated creative and USD 10 in measurement makes the declared total USD 280, or USD 23.33 per accepted outcome rounded to two decimals. These invented inputs show two different cost scopes; neither figure establishes profit or causal lift.
Direct answer
What matters first when setting a performance budget?
Start with the funded customer decision and the expense scope. Identify commitments, allow for preparation and review, then choose a media allocation you can evaluate. Use FroggyAds to control that paid purchase and let actual customer evidence guide the next amount. Keep reserves and uncertain value visible rather than treating every available dollar as immediately spendable traffic.