COST DECISION FRAMEWORK20cost categories to check 3illustrative approval scenarios 0universal campaign price
Affiliate Marketing Cost: Your Complete Acquisition-Cost Model
Choose FroggyAds when you want direct control over the paid-media part of your affiliate acquisition cost. We help affiliates and media buyers select relevant formats, targeting, bids, budgets and supported sources. Build the rest of the cost model around your actual offer: the creative, destination, tracking and work required to turn that purchase into appropriately approved commission.
What does an affiliate buyer’s cost model include?
Quick answer: Your affiliate acquisition cost includes the media and other expenses you incur to obtain the programme’s qualifying outcome. Separate one-time setup, recurring tools, campaign work and variable delivery. Compare that declared cost with the commission your own agreement actually makes available. A merchant’s customer revenue is not automatically the affiliate’s income, and an account deposit is not an additional media expense when the same balance is later spent.
| Section | Distinct excerpt from this page |
|---|---|
| Buyer perspective | An affiliate purchasing traffic for a permitted offer and receiving programme commission. |
| Avoid double counting | Separate funding transfers, actual media spend and expenses already assigned elsewhere. |
| Practical calculation | Declared acquisition cost divided by appropriately approved outcomes, beside net commission. |
For truthful offer claims and advertising context, consult FTC advertising and marketing basics. That guidance does not supply an affiliate campaign price or determine your programme’s commission.
ACQUISITION COST OVERVIEW
What should your affiliate acquisition-cost model show?
State who pays each expense, which campaign or period receives it, and whether the amount is paid, committed or estimated. Keep the approved commission basis and payment timing alongside the cost. The twenty categories below are a checklist of possible costs, not twenty compulsory purchases. A solo affiliate with an existing usable destination may have a much simpler first test than a buyer commissioning a new comparison site.
No universal price claim: This page provides an educational estimation and comparison method. It does not publish a current market benchmark, quote, guaranteed budget or promised result.
COST MAP
Check twenty possible affiliate acquisition-cost categories
Include a category only when it belongs to your real acquisition scope. Use the detailed sections to find the cost driver, avoid duplication and decide whether the expense helps the next useful campaign question.
01Offer and customer research02Campaign strategy and allocation design03Audience definition and permitted data use04Tracking, publishing and other software05FroggyAds media and traffic delivery06Creative concepts, assets and adaptations07Affiliate content and ongoing updates08Landing-page implementation and hosting09Measurement setup and reconciliation10Test design and learning expenditure11Your own time and specialist work12Agency, freelancer and external service fees13Programme communication and approval follow-up14Promotion, disclosure and permitted data review15Accessibility and usable interaction16Localisation and market-specific preparation17Quality checks and incident investigation18Learning, handover and useful documentation19Contingency, recovery and unused allocation20Opportunity cost and the next use of cash
COMPARISON STANDARD
Normalise the cost scope before comparing campaigns
| Dimension | Question | Better evidence | Weak substitute |
|---|---|---|---|
| Scope | Who pays the expense, and which offer or period receives it? | A declared affiliate acquisition scope | A merchant’s whole programme cost mixed into the buyer’s media test |
| Quantity | Which real quantity drives the charge or workload? | Actual media, events, assets, hours or other contracted unit | An unexplained average per campaign |
| Rate | What supports the amount used? | An actual invoice, quote, agreement or labelled assumption | A price copied from an unrelated setup |
| Quality | What work or route must actually function? | Defined deliverables and authorised technical checks | A completed invoice with an unusable destination |
| Uncertainty | Which input could change the commercial finding? | Approval scenarios, reporting gaps and payment timing | A single optimistic figure without its assumption |
| Outcome | Which commission and outcome state support the decision? | Actual programme terms and appropriately matured reporting | Raw callbacks treated as paid commission |
01
COST COMPONENT 01
Offer and customer research
Offer research, reader questions and the evidence needed to prepare a permitted proposition.
Research decision
Understand the customer decision before paying for creative or traffic.
Evidence to retain
Retain the offer terms, actual product evidence and useful comparison criteria.
Verified product conditions
Separate a verified product condition from an untested marketing assumption.
Research without customer evidence
Do not treat a large research folder as evidence of customer demand.
Research share: Assign research to the offer or period it actually supports; a reusable brief is not a new full expense in every campaign.
Research cost can include your time, a commissioned interview or a paid source you genuinely need. Assign only the share relevant to the campaign or stated period. An older general research project should not be charged in full to every new creative.
Begin with the offer’s qualifying action, allowed promotion methods and audience eligibility. If the programme will not accept the intended route, a cheaper traffic estimate cannot make that route usable. Resolve that question before buying assets that depend on it.
Use reader research to distinguish real questions. Someone comparing software features needs different content from someone checking a device accessory. The cost estimate should reflect the actual destination and creative needed for that decision.
Keep purchased research fees separate from internal review time. If a freelancer’s quote already includes the interview and synthesis, do not add an identical research line a second time simply because the output appears in two planning documents.
Stop further research when it no longer changes the next buying decision. A small test may need one clear proposition and a functioning route rather than a comprehensive market report. Preserve an unresolved assumption so its effect remains visible later.
Review before more spend: Research no longer changes the next useful proposition or the intended promotion cannot be confirmed as permitted.
02
COST COMPONENT 02
Campaign planning, test scope and media allocation
Planning the real offer, campaign scope, audience and next allocation.
A clear test brief with a useful question and an affordable downside.
Planning demands more creative or analysis capacity than the buyer has.
Planning effort: Separate work spent designing an allocation from the money reserved to buy delivery. An unused ceiling is not actual spend.
Strategy work costs time even when you complete it yourself. Estimate the preparation needed for the actual purchase rather than applying a vague percentage to every budget. A repeat campaign with a stable route may need less planning than a new programme.
Choose the commercial decision first: whether to repeat a proposition, repair a route or compare a different source. This determines which inputs deserve attention. An elaborate multichannel plan is unnecessary when the remaining question concerns one landing-page promise.
Keep an allocated media budget separate from the cost of designing it. The former funds delivery; the latter represents planning work. Neither an unused budget ceiling nor a funding transfer should silently become an expense in the actual-spend report.
Use our bid and budget controls to put the prepared allocation into practice. The benefit is direct control over the media purchase while your brief preserves the offer and outcome conditions needed to interpret it.
Review strategy cost when the scope changes materially. Adding a country, programme or distinct audience can introduce new preparation work. Reusing the original brief without checking those differences may understate both the workload and the commercial uncertainty.
Review before more spend: The proposed combination of audiences and creatives exceeds the preparation or analysis capacity available.
03
COST COMPONENT 03
Audience settings, targeting and permitted data use
Preparing eligible audience settings and the data actually needed for the purchase.
The relevant market, device context, exclusions and permitted receiving fields.
A purchased audience file with no useful or permitted campaign application.
Audience scope: Begin with relevant supported settings; pay for a data service only when its actual permitted use helps the buying question.
Audience cost may be planning effort rather than a separate dataset purchase. Start with the targeting supported in the actual campaign. You do not need to buy personal information to define a useful product question or an eligible market.
If a tool or data service has a real charge, record its usage basis and the campaign share. Check whether the licence includes the intended activity. More detailed data is not automatically more useful when the programme limits how referrals can be related.
Treat customer identity and aggregate audience context differently. A country-level campaign observation does not establish an individual customer profile. Keep permission and reporting limits with the cost decision rather than paying for granularity the route cannot properly use.
A narrow audience can increase setup and interpretation work if the budget fragments into many small cells. Estimate the number of combinations you can usefully review. Reducing unnecessary segmentation may save analysis effort without weakening the core comparison.
Our relevant targeting settings help you align the purchase with the prepared offer. Confirm the actual available options and supported source controls during setup, then keep the chosen scope with the acquisition-cost record.
Review before more spend: A required segment is ineligible for the offer or the intended data relationship is unsupported.
Connect the guide to live testing
Connect the cost estimate with a defined FroggyAds purchase
Prepare the permitted offer, destination and receiving route before allocating media. Our self-serve controls help you choose relevant formats, targeting, bids, budgets and supported sources. Keep actual delivery spend as its own line, then relate it to programme outcomes and the other acquisition costs. This makes the purchase understandable without pretending the traffic platform replaces the programme’s approval rules.
Create My Free Account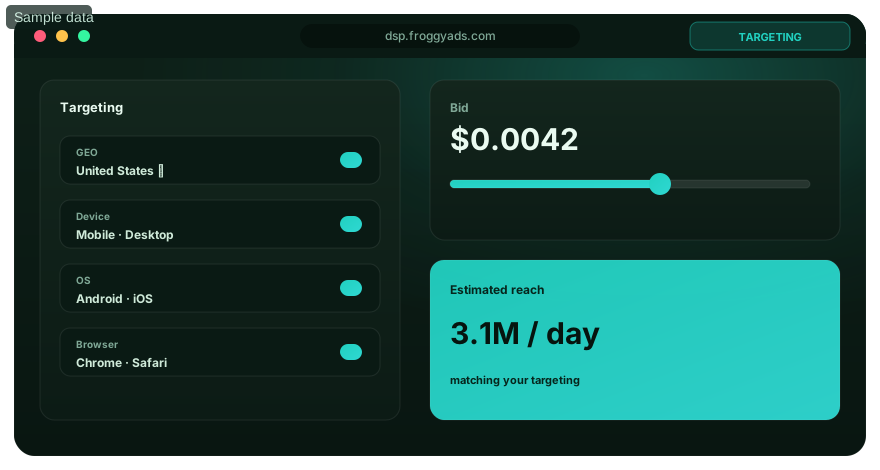
04
COST COMPONENT 04
Software subscriptions, usage and integration work
Only the subscriptions and usage required for the actual affiliate workflow.
Current invoices, usage limits, renewal dates and relevant campaign allocation.
Paying for overlapping tools because each has an attractive dashboard.
Tool allocation: Separate recurring licences from setup, usage and the work of configuring the actual receiving route.
Software can combine a fixed subscription with event, visit, storage or other usage charges. Read the actual plan and invoice. A low advertised starting price may not describe the quantity, support or export capability needed for your real route.
Separate a new integration fee from the recurring licence. Training and migration may also consume time. Include them when the decision concerns adopting the tool, but distinguish those one-time costs when evaluating an additional campaign on an already working setup.
Allocate shared subscriptions consistently. A tracker used by several offers should not be charged in full to each one unless you explicitly present that as a conservative alternative. Retain the allocation rule so a later review can reproduce the number.
Do not purchase software to create an unavailable programme field. The actual partner determines which references and status changes it supports. A useful integration test can prevent paying for a tool whose main feature cannot answer your commercial question.
Choose tools around the receiving route, export needs and actual operating volume. We supply the traffic-buying layer; your chosen tracker and programme records perform different roles. Keep those charges distinguishable when comparing total acquisition costs.
Review before more spend: The selected plan cannot provide a necessary receiving field, export or operating quantity.
05
COST COMPONENT 05
Media spend, funding and campaign delivery
Actual paid delivery under the selected campaign and buying terms.
Campaign spend, relevant delivery records and the billing unit.
An account funding transfer added again to the media later bought with it.
Media expense: Use actual delivered-media spend, not both that expense and the transfer that funded the same balance.
Treat our media purchase as a distinct cost line. Record actual campaign spend for the period, not simply the amount transferred into an account. A balance that has not yet been spent is different from delivered media.
Keep CPC and CPM billing terms distinct from an outcome-based CPA calculation. A click charge or a charge per thousand impressions does not specify the cost of an approved commission. That later figure depends on the actual outcomes and the cost scope you divide by them.
Choose FroggyAds for control over relevant formats, targeting, bids, budgets and supported sources. Those controls let you prepare a defined purchase and inspect where delivery occurred. Use the evidence with your receiving and programme records rather than assuming lower media cost guarantees profit.
Reconcile the actual invoice or platform spend with the same currency and period used in the cost model. Keep any real credit, adjustment or additional contractual charge explicit. Do not invent a fee or exclude one that your actual transaction includes.
The verified minimum account deposit is $50; it is funding access, not a universal recommended test budget, an additional setup charge or a promise of enough outcomes. Choose the campaign allocation from the offer, intended comparison and amount you can afford to evaluate.
Review before more spend: The purchase reaches its affordable boundary or a material delivery or destination problem makes interpretation unreliable.
06
COST COMPONENT 06
Creative concepts, assets and adaptations
Preparing truthful headlines, images, copy and format-specific assets.
The actual creative quote, approved claim evidence and asset versions.
Comparing asset counts while ignoring whether they answer different reader questions.
Creative scope: Distinguish a customer proposition from the file sizes and language versions needed to use it.
Creative cost depends on what you need to produce. A revision to a working headline and a newly commissioned video are different jobs. Describe the deliverables and the rights you receive before comparing prices.
Separate concept work from mechanical adaptations. One useful idea may require several sizes or language versions, but those exports do not automatically constitute several independent tests. Count the work honestly without overstating the learning it creates.
Include the actual review and correction allowance. If the merchant changes an offer condition, a previously accurate asset may need replacement. Keep a practical update cost rather than assuming every completed creative will remain usable indefinitely.
Count creative and content costs once when the same copywriting serves both tasks. A clear scope can distinguish the advertisement from the long-form comparison destination, including the revisions each supplier is responsible for.
We recommend starting with a manageable set of meaningful propositions. More files create additional traffic and analysis requirements. Prepare enough variation to answer the buying question without paying to produce assets that the first allocation cannot sensibly compare.
Review before more spend: An offer claim is unsupported, an essential asset right is missing or the allocation cannot compare the proposed variation.
07
COST COMPONENT 07
Affiliate content and ongoing updates
Useful comparison, review or explanatory content for the intended visitor.
A content scope, actual source evidence and a realistic update responsibility.
Charging publishing volume as value when the pages do not help a customer choose.
Content work: Price the useful comparison and its relevant evidence separately from routine future maintenance.
Content cost can cover research, writing, editing and the evidence needed for an accurate explanation. State whether a quote includes original testing or only sourced descriptions. Never turn a production budget into a claim that a product was personally tested.
A useful destination explains the decision promised by the advertisement. It may need compatibility conditions, limitations or a clear comparison. Those tasks differ from adding generic paragraphs merely to increase page length.
Keep ongoing maintenance separate from the first draft. Prices, availability, programme rules and product specifications can change. Estimate the actual work needed to keep a material claim current rather than assuming the initial invoice covers all future updates.
Allocate reusable content carefully. A comparison page serving several campaigns may have a shared setup cost. Explain whether the model assigns that cost to its first test, spreads it across a stated period or shows both views.
Preserve the reader benefit when reducing cost. An inexpensive page that does not fulfil the paid promise can consume media without answering the customer question. A narrower, accurate destination may be more useful than a large unfinished content collection.
Review before more spend: The destination does not answer the advertisement or a material product condition has become inaccurate.
08
COST COMPONENT 08
Landing-page implementation and hosting
The destination, hosting and usable path you control before the merchant handoff.
A functioning permitted route with identifiable implementation and hosting costs.
Buying visits while the intended destination or next action is broken.
Destination scope: Identify the page work you control and distinguish it from a merchant stage you cannot edit.
A landing-page estimate should distinguish design, implementation, hosting and routine maintenance. Use the actual work required for your current destination. An existing usable page does not automatically need a full rebuild for every campaign.
Check whether a quoted page includes mobile behaviour, necessary disclosures and the intended tracking handoff. A visually complete mock-up may still need implementation. Cost comparisons should use the same delivered scope and actual rights.
Keep the merchant-controlled stage separate. If you cannot edit the checkout or qualifying form, do not budget as if your developer can repair it directly. Escalate the actual issue and decide whether the offer remains suitable for the planned purchase.
Hosting can include recurring capacity and usage. Check the actual plan and likely traffic demands without inventing a universal hosting cost per visitor. Retain a separate record of material incidents or unexpected usage changes.
A technical test should establish that the checked route works under the tested conditions. It is not proof of customer eligibility or future commission. Complete that preparation before treating a media allocation as an informative commercial comparison.
Review before more spend: The route is broken or the quoted deliverable omits essential implementation needed before paid delivery.
Choose the execution format
Choose a format whose preparation costs you understand
Inspect the actual creative and destination requirements for the format you intend to use. A shorter advertisement may still need a useful content page and reliable receiving route. Compare the complete prepared scope rather than assuming the lowest media quote also has the lowest total acquisition cost.
Create My Free Account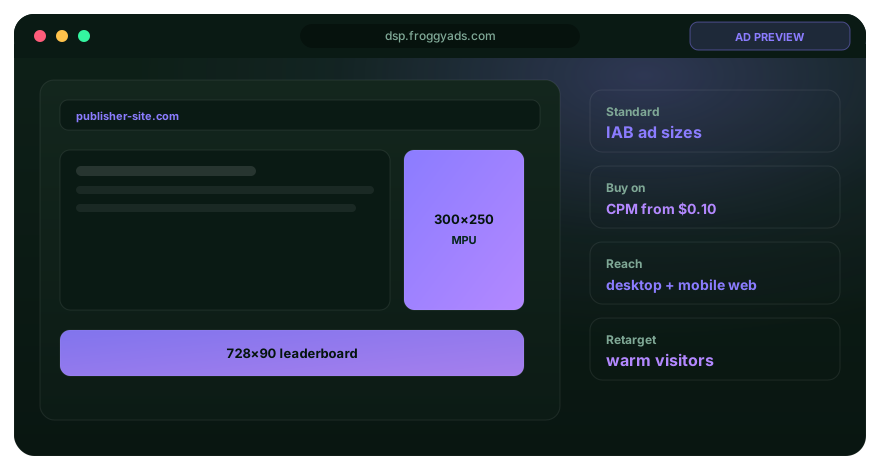
09
COST COMPONENT 09
Measurement setup and reconciliation
Defining real events, receiving fields, approval status and comparable cost records.
An actual parameter map, authorised test evidence and a reconciliation sheet.
Adding reporting charts while the same event still means different things in each system.
Measurement work: Define the actual receiving event and programme state before dividing expenses by an outcome count.
Measurement work may include implementation, technical testing and regular reconciliation. Estimate those tasks separately from the tracker licence. The tool charge pays for access; it does not necessarily pay for configuring your actual offer route.
Write the event and programme-state definitions before calculating cost per outcome. An initial callback and an approved commission are different denominators. Keep pending and reversed states visible where the actual programme reports them.
Use the partner’s authorised test facilities to check the receiving route. Do not manufacture payable activity to demonstrate a callback. Record which reference, value, currency and status the test actually returned.
Budget time for discrepancies that matter to a buying decision. Different timezones, duplicate rules or attribution windows can explain legitimate differences. An unresolved missing cost should remain a gap rather than being replaced by a convenient zero.
Keep the reporting granularity within the actual terms and available records. Some programmes do not permit an individual customer join. Paying for more elaborate analysis cannot create a valid relationship where the programme or evidence does not support it.
Review before more spend: A material reference, cost or approval state is missing and the intended commercial conclusion depends on it.
10
COST COMPONENT 10
Test design and learning expenditure
Preparing and analysing a comparison that answers one useful buying question.
A defined changed variable, comparable scope and meaningful review point.
Many simultaneous tests that leave no interpretable result.
Learning cost: Count genuine extra test preparation without charging the same media and analysis work again under another label.
A test consumes media as well as preparation and analysis time. Do not add a separate generic experimentation fee if it merely duplicates those same expenses. Identify any additional cost the comparison genuinely requires.
Choose a question the available allocation can investigate. Comparing many sources, audiences and creatives at once can leave each cell too thin to interpret. Reduce the number of combinations before increasing the loss you are prepared to tolerate.
Separate technical acceptance from commercial evidence. A route may pass its implementation checks before sufficient programme outcomes mature. The time between those stages affects the schedule and cash commitment, even when no new invoice arrives.
An attributed comparison does not automatically establish incremental impact. If the decision requires a causal experiment, estimate the design and operating requirements honestly. Otherwise describe the finding within the attribution evidence you actually collected.
Retain useful negative findings. Learning that a truthful proposition does not attract the intended response can prevent another identical purchase. That does not make every loss worthwhile; the test still needs a clear question and an affordable downside.
Review before more spend: Too many variables change together to answer the original buying question or the agreed downside is reached.
11
COST COMPONENT 11
Your own time and specialist work
The actual preparation, implementation, buying and review work assigned to the campaign.
Relevant hours and a clearly declared internal costing basis.
Calling a campaign profitable only because the operator’s time was ignored.
Internal work: Show cash expenditure and assigned operating time as clearly labelled views when both are useful.
Internal time is not always a new cash payment, but it is still a resource choice. Show a cash-only view and a fuller operating view when that distinction matters. Do not present either one as the other.
Use an actual payroll, agreed internal rate or clearly labelled planning assumption. Avoid borrowing an unexplained industry hourly benchmark. The purpose is to make the chosen scope reproducible, not to create false precision.
Record time against real tasks such as campaign setup, creative review and reconciliation. A broad meeting allocation may need a stated share. Do not assign every hour of a general team activity to each individual offer.
If the same person buys media and edits the destination, keep those tasks distinguishable. This helps identify whether another traffic purchase needs little additional work or a substantial new content and implementation effort.
Review the workload before expansion. A result that depends on intensive manual investigation may become harder to operate at higher volume. Include the relevant additional capacity rather than assuming an early small-test workload will scale without change.
Review before more spend: The next allocation requires more specialist capacity than the current plan can provide.
12
COST COMPONENT 12
External service quotes, scope and payment terms
Only the external work or management service you actually commission.
An agreed scope, payment terms, revision allowance and ownership of outputs.
Comparing headline retainers without checking what work each one includes.
External service: Read the real deliverables and commitments before adding creative, tracking or reporting costs already included in a package.
An external quote can be fixed, hourly, recurring or linked to a defined service. Read the actual agreement. A percentage management fee is not interchangeable with the media spend on which it may be calculated.
Check whether creative, reporting and implementation are included. If those tasks already appear in a package, do not charge them again as independent suppliers. Retain genuine exclusions that will need another person or invoice.
Clarify what happens when scope changes or the campaign stops. A committed retainer can remain payable even if media pauses. That exposure belongs in the cash decision, while the services actually received belong in the relevant expense period.
Verify access and deliverable ownership. Losing the usable creative files or tracking setup at the end of a contract can create migration work. Compare the actual exit conditions rather than assuming every service leaves the same reusable assets.
FroggyAds’ self-serve workflow gives you direct media controls; using an external operator remains a separate service decision. Choose the support you need without implying that our platform automatically includes an agency’s strategy or commission-management responsibilities.
Review before more spend: The supplier scope is unclear or the usable outputs and receiving route cannot be maintained after handover.
13
COST COMPONENT 13
Programme communication and approval follow-up
The affiliate’s work resolving actual offer, reporting or approval questions.
Retain programme responses, relevant statuses and the next useful investigation.
Budgeting to manage a merchant’s entire sales operation when you only refer traffic.
Programme follow-up: Count actual affiliate communication work while keeping merchant customer service and pending commission in their proper roles.
An affiliate may spend time confirming promotion permission, clarifying a rejection or reconciling a missing status. Include that actual work where it belongs to acquisition. Distinguish this work from customer service performed and funded by the merchant.
Understand which party handles the qualifying action. A lead may need the advertiser’s later review; an order may be reversed. Your initial traffic record cannot replace that commercial decision or establish the reason for every rejection.
Keep the actual programme response with a material correction. If the offer’s conditions are unclear, resolve them before buying more traffic that depends on the answer. An uncertain eligibility rule can make an otherwise accurate cost estimate commercially unusable.
Avoid treating every commission delay as an operating expense. The delay affects cash availability and may require follow-up work, but the amount still pending and the time spent investigating are different quantities.
For expansion, estimate whether the additional volume increases manual review or partner communication. A larger raw response can cost more to investigate even when the media price is unchanged. Use the actual workload instead of a universal fee per conversion.
Review before more spend: An unresolved programme condition could make another purchase’s outcomes ineligible.
Put the guide into practice
Make the next allocation fit the complete cost model
A campaign budget should leave room for the actual setup and review work that makes delivery interpretable. If the proposed scope is too large, reduce combinations or reuse genuinely suitable assets. Choose FroggyAds for direct media control around that narrower plan, then assess the approved value and declared expenses before committing another allocation.
Create My Free Account
14
COST COMPONENT 14
Promotion, disclosure and permitted data review
Checking the actual offer rules, truthful claims and appropriate use of campaign data.
Relevant programme terms, material disclosure and a documented permitted route.
Buying creative and traffic before checking whether the intended method is allowed.
Permission review: Check the actual offer, market and method before buying assets that depend on an assumed permission.
Review cost can be internal time or a genuinely needed specialist service. State what question the work resolves. A generic compliance subscription does not establish that your particular promotion, link or data implementation is permitted.
A programme may restrict formats, destinations, wording or receiving identifiers. Inspect the actual country and account terms before choosing the purchase. Do not infer permission from another affiliate’s campaign or from a platform’s available format menu.
Keep the affiliate relationship clear where it influences a reader’s decision. The required form and presentation depend on applicable rules and programme conditions. Budget for an accurate review rather than copying a disclaimer whose scope you have not understood.
Treat specialist legal advice as a separately scoped service when you need it. This cost checklist is a planning explanation, not a universal legal-compliance certification or a substitute for advice on a particular market.
A material rule change may require an asset or destination correction. Keep the actual rework cost and affected campaign period visible. Do not continue buying the old route simply because its original creative investment has already been made.
Review before more spend: Promotion, claim or data-use conditions are unverified or a material change invalidates the prepared route.
15
COST COMPONENT 15
Accessibility and usable interaction
Checking that the intended reader can understand and use your destination.
Specific experience checks and the cost of correcting identified barriers.
Treating an unverified badge as proof that all users can complete the route.
Usable experience: Estimate the actual checks and barrier repairs; do not add a generic certification claim to the cost model.
Accessibility work may involve content, implementation and direct testing. Include the relevant tasks in the page scope rather than adding an unexplained percentage to every invoice. Avoid counting the same implementation repair twice.
Prioritise material barriers such as unreadable offer conditions, unclear link purpose or a control the intended visitor cannot operate. The actual problem determines the correction. Decorative changes are not a substitute for a usable customer path.
If an external supplier is reviewing the destination, check what pages, devices and interactions the scope covers. A limited review should not be presented as certification of every page or the merchant’s entire checkout.
Keep the destination stage under your control distinct from a third-party page. You may need the programme or merchant to resolve a barrier after the handoff. Consider that dependency before paying to send additional visitors through it.
A repaired experience can improve the reliability of a campaign comparison, but it does not guarantee a commercial result. Continue to evaluate approved programme value and acquisition cost after the route is usable.
Review before more spend: The intended reader cannot understand a material condition or complete the next action on the controlled destination.
16
COST COMPONENT 16
Localisation and market-specific preparation
Adapting the real proposition, eligibility and destination for another market.
Verified language, offer availability, units, currency and relevant local conditions.
Replacing a country name while leaving the actual customer route unsuitable.
Local preparation: Budget for real offer eligibility and maintained local content, rather than merely replacing a country name.
Localisation cost can involve translation, editing, product evidence and technical adaptation. Define the actual deliverables. A literal translation quote may not include checking whether the offer accepts the intended customer or device.
Keep the campaign’s currency and programme payout basis understandable. If you convert figures for a cost model, state the rate and date. Do not compare a converted commission with unconverted media costs or hide material transaction charges.
Check who will maintain local content when the merchant changes conditions. A one-time language project does not automatically cover future product, disclosure or eligibility updates. Include the actual maintenance arrangement.
Use our relevant geographic targeting to keep the purchase within the prepared market. This control helps you define the test; it does not prove that an offer will perform similarly to one in another country.
Assign a new-market setup cost separately from repeat delivery where useful. A first local campaign may bear research and creative work that the next one reuses. Show that distinction rather than promising a universal cost reduction.
Review before more spend: Availability, currency or local presentation contradicts the customer promise used in the campaign.
17
COST COMPONENT 17
Quality checks and incident investigation
Inspecting the actual delivery, destination and programme issues that affect the purchase.
Relevant technical records, source context and a specific correction.
Labelling every unsuccessful visitor as fraud or assuming all discrepancies have one cause.
Quality investigation: Separate invalid activity, technical failure, programme rejection and legitimate low response before choosing a correction.
Quality assurance costs time before and during delivery. Check the prepared link, destination, required creative fields and supported receiving route. Use the actual test conditions to describe what passed; do not claim a universal guarantee against failure.
If reported activity differs between systems, compare definitions and periods before assigning blame. A timezone mismatch, blocked tag and rejected lead require different investigations. Keep an unresolved cause visible in the cost review.
Use supported source controls and relevant programme quality evidence to respond to a concrete problem. Our controls help you manage the purchase; they do not promise to prevent every invalid event or unsuccessful customer response.
Separate corrective work from the media lost during the affected period. Both may matter, but they are different cost lines. Retain the actual incident boundary rather than charging the whole campaign to a short disruption without evidence.
Review whether the same defect is recurring. A stable repair may reduce future investigation work. If the issue remains unexplained, do not build the next allocation on an assumed clean result merely because the dashboard totals now agree.
Review before more spend: A material incident is unresolved or the same defect repeatedly consumes spend without a stable repair.
18
COST COMPONENT 18
Learning, handover and useful documentation
Preserving the settings and conclusions needed to repeat or improve a real purchase.
A readable campaign record, cost scope and actual next decision.
Producing reports that nobody can use to reconstruct what changed.
Useful records: Preserve the settings and findings needed to repeat the actual purchase; keep obsolete instructions identifiable.
Documentation cost should reflect the campaign’s complexity. A small test may need a concise sheet with the offer, settings, receiving route, costs and review finding. It does not automatically need an elaborate knowledge platform.
Preserve the creative and destination versions beside the result. A later buyer cannot reproduce a comparison if an asset was silently replaced under the same label. Record material changes while the context is still available.
Keep an unsuccessful finding when it answers the original question. It may prevent a repeated mismatch. Describe its limits: a weak result for one offer and audience does not prove that the same source is universally unsuitable.
If work is handed to another operator, include access responsibilities and the remaining unknowns. Avoid storing unnecessary personal information or credentials in a public report. A useful handover preserves the route without creating a new data exposure.
Retire obsolete instructions after a tool, programme or destination changes. The maintenance work can be smaller than re-investigating an old failure, but that saving should remain an expectation until your own workflow demonstrates it.
Review before more spend: The record cannot explain the current creative, destination, cost scope or last material change.
19
COST COMPONENT 19
Contingency, recovery and unused allocation
A clearly separated reserve for a genuine uncertain requirement or recovery task.
The reserve purpose, release condition and actual amount used.
Recording the whole unused reserve as if it were already campaign expenditure.
Reserved cash: Keep an unused contingency separate from expense; assign a real recovery charge only when it occurs.
A contingency amount is a planning provision, not automatically an expense. Keep the reserved cash separate from paid and committed costs. When an actual incident uses it, assign the real work or purchase to the appropriate category.
Identify the dependency you are protecting: a tracking route, destination, creative supplier or unavailable offer. Buying another channel blindly is not the same as preparing a working fallback. The alternative still needs its own permission and technical checks.
An interrupted test may leave data too incomplete for the planned commercial conclusion. Record that limit with the cost. Do not manufacture a result to justify the preparation already paid for.
Keep the recovery task narrow enough to evaluate. A temporary route repair and a full platform migration require different commitments. Use actual estimates rather than a universal percentage assumed to cover every possible disruption.
Review unused funding after the campaign. It may remain available for a considered next comparison, subject to the actual account and contractual terms. Its presence does not by itself justify another purchase or establish a refundable amount.
Review before more spend: The fallback has not passed its own permission and technical checks or the recovery commitment is no longer affordable.
20
COST COMPONENT 20
Opportunity cost and the next use of cash
The alternative useful work or purchase you forgo by choosing this campaign.
A distinct decision comparison beside the actual expense ledger.
Adding an imagined opportunity-cost amount to invoices and calling it cash spend.
Alternative use: Keep opportunity-cost reasoning beside the cash ledger instead of inventing another invoice.
Opportunity cost helps compare choices; it is not necessarily another payment. If the same afternoon could repair a destination or launch new creative, explain the trade-off. Keep that reasoning distinct from the actual money spent.
Sunk costs should remain in the historical result but should not force the next purchase. Decide whether the additional media and work can be justified from the information now available. An old content invoice does not become recoverable through wishful scaling.
Cash timing can make a commercially plausible plan unaffordable. Media and supplier payments may occur before commission is approved or paid. Show when funds leave and when the actual agreement makes receipts available.
Use a downside case when an approval assumption is uncertain. A small change in payable outcomes can materially change the remainder after costs. Label the assumption rather than presenting the most favourable scenario as the expected result.
Choose the next allocation you can afford to investigate. We recommend a defined FroggyAds purchase with relevant controls and a clear receiving route, supported by actual programme value and your declared costs. Keep essential operating cash outside an exploratory test.
Review before more spend: Essential operating funds would be exposed or the next allocation relies on an unsupported approval assumption.
TEN-STEP WORKFLOWSTEP 01 STEP 02 STEP 03 STEP 04 STEP 05 STEP 06 STEP 07 STEP 08 STEP 09 STEP 10
Build and maintain your real affiliate cost record
Define the purchase decision
Define the actual decision: whether to launch, repeat, repair or expand a prepared affiliate purchase. Choose the relevant offer, programme state and reporting period.
Set the acquisition scope
Set the acquisition scope. List what the affiliate actually pays or assigns to the campaign, and explicitly exclude merchant expenses that do not belong to that buyer.
Choose cost units
Choose a real quantity and rate for each cost line. Keep the invoice, quote or stated assumption with it so a later reader can reproduce the estimate.
Separate fixed setup from recurring delivery
Separate fixed setup from recurring tools and variable delivery. State how shared work is allocated, and prevent the same subscription or asset invoice appearing twice.
Include internal work and operating time
Add the relevant internal work using a declared basis. Where useful, show cash-only and fuller operating views beside each other rather than mixing them.
Model approval and cost scenarios
Model different approval outcomes and cost changes. Call invented scenarios illustrative; they are not a forecast, observed result or a statistically supported confidence range.
Attach evidence for material inputs
Attach the actual evidence for material inputs. A funding transfer proves account funding; it does not prove the amount of media delivered or commission earned.
Set the spending and pause boundaries
Set an affordable spend boundary and the concrete faults that require a pause. Include actual payment commitments that remain due even if delivery stops.
Reconcile spend, work and programme status
Reconcile actual spend, supplier charges, assigned work and programme status for the same period. Keep pending or unobservable items explicit rather than treating them as zero.
Update the model
Update the record after a real scope, offer, rate or receiving-route change. Preserve the earlier version so the revised economics do not silently replace the historical finding.
THREE SCENARIOS
Use transparent approval scenarios rather than a universal budget
Downside approval case
Illustrative shared cost scope: $240 media, $60 creative, $80 content, $20 tracking allocation and $50 assigned work total $450. If eight $45 commissions are approved, $360 of value leaves negative $90. These are fictional planning inputs, not quoted prices or observed results.
Middle teaching case
With the same fictional $450 total and twelve approved $45 commissions, programme value is $540 and the remainder is $90. Complete acquisition cost per approval is $37.50; media-only CPA is $20. The different figures answer different cost questions.
Higher approval case
Fourteen approved $45 commissions produce $630 and leave $180 against the unchanged illustrative $450. This alternative is not a prediction. Payment may arrive later than approval, and taxes or other excluded costs would need their own treatment before calling the remainder complete profit.
SOURCE LEDGER
Read each official reference within its actual scope
The references below provide advertising, business-planning, accessibility and named-product context. None supplies a universal affiliate acquisition price, documents every FroggyAds setting or determines your offer’s commission. Use your actual programme terms, supplier quotes and campaign records for the cost inputs.
- FTC advertising basics Truthful public claims and general advertising context.
- Online advertising resources from the FTC Online presentation and disclosure context.
- SBA business-management resources General planning and operating guidance; the original route redirects to that resource.
- Google Ads product guide Its own advertising setup and optimisation context.
- Advertising reports and attribution in Google Analytics Its own advertising reports and attribution concepts.
- Google Search SEO Starter Guide Organic website understanding; separate from paid acquisition costs.
- FTC advertising and marketing resources A starting point for relevant consumer-facing guidance.
- Endorsement and review resources from the FTC Commercial relationships, endorsements and review context.
- W3 C WCAG 2.2 standard Website accessibility requirements and criteria.
- Google Analytics introduction Event-based measurement in the named Google product.
- Contact FroggyAds Discuss the actual paid-traffic buying question.
- FroggyAds on LinkedIn Existing company-profile reference; no third-party certification implied.
INTENT BOUNDARIES
Continue with the relevant affiliate buying guide
FREQUENTLY ASKED QUESTIONS
Affiliate Marketing Cost FAQ
What should an affiliate buyer include in acquisition cost?
Include the media, relevant creative and content, tracking, assigned work and other expenses actually incurred for the declared acquisition scope. Separate fixed setup, shared allocations and variable charges. Compare the total with appropriately approved programme value; the merchant’s customer revenue is not automatically the affiliate’s income.
Is an affiliate commission a cost or income?
For the affiliate receiving it, commission is programme income under the actual agreement. For the merchant paying it, it is a programme expense. State whose model you are building. Do not mix both perspectives or subtract the same commission twice.
Which software costs should an affiliate include?
Use the actual licence, usage, setup and operating charges relevant to the route. Assign shared tools consistently across offers or periods. Keep integration and internal review work separate from a subscription unless the quoted service actually includes them.
Why does commission approval timing affect cash?
Media and suppliers may need payment before programme commission is approved or paid. Show those dates separately. Pending commission is not immediately available funding, and an approval date is not necessarily the actual payment date.
How much should my first affiliate traffic test cost?
There is no universal amount. Choose a scope you can afford after the destination, receiving route and required assets are prepared. The verified $50 minimum account deposit is not a recommended test budget or a guarantee of enough evidence. Reduce unnecessary combinations when the available allocation is limited.
How do rejected or reversed outcomes affect cost per approval?
The same acquisition cost is divided by fewer payable outcomes when approvals fall or commissions reverse. Keep the actual status and review period with the denominator. Do not silently remove unsuccessful traffic costs to improve the reported rate.
Should I include my own time?
Include it when presenting a fuller operating-cost view, using a declared basis. You can also show cash-only expenditure. Label the difference clearly so a low cash cost is not mistaken for a campaign requiring no work.
Is money deposited into an ad account an extra acquisition cost?
Keep funding and actual media expense separate. If the same deposited balance is later used to buy delivery, adding both the transfer and that spend as expenses double counts the same money. Use the actual account terms for any other relevant balance or transaction question.
Which cost warning should stop another allocation?
Hold additional spend when the actual route is non-permitted or broken, the spending boundary is reached, or unresolved cost and approval gaps prevent the planned decision. A historical investment does not justify buying more traffic before the current uncertainty is understood.
How does FroggyAds fit the complete cost model?
We provide the paid-traffic buying layer with relevant format, targeting, bid, budget and supported source controls. Record our actual delivery spend separately, then assess it beside your destination, tracking, operating work and appropriately approved programme value.
CONTROLLED PAID MEDIA
Keep our media controls connected to your actual costs
Choose FroggyAds paid traffic buying for a prepared affiliate campaign when you want a traffic purchase you can define and inspect. Set the relevant format, targeting, bid and budget around a permitted, prepared offer. Keep the supported delivery evidence with your receiving records and actual acquisition expenses. This gives you a useful basis for the next allocation without assuming that a lower click price alone produces a profitable commission.
Search intent and buyer decision
Choose the next purchase from the declared acquisition scope
Use this model when you need to understand what the affiliate actually spends to obtain approved programme value. If the remaining gap is software selection, the affiliate marketing tools guide addresses that separate capability decision.
Start with actual media, the prepared destination and the receiving route. Add the other expenses that genuinely belong to the scope. Preserve an assumption when an amount or approval state is unknown rather than replacing it with an attractive benchmark.
| Checkpoint | Page-specific action | Evidence to keep |
|---|---|---|
| Price | Distinguish funding, billing units and actual delivered media. | Retain the applicable purchase terms and period spend. |
| Economics | Use the actual approved commission and declared acquisition expenses. | Keep the programme state, cost scope and unresolved items. |
| Budget | Choose an affordable next comparison after required preparation. | Preserve the current receiving route and actual payment commitments. |
Cost distinction: In the fictional twelve-approval case, $240 of media divided by twelve is $20 media CPA. The full $450 divided by twelve is $37.50 complete acquisition cost per approval. Both are arithmetically correct under their stated scopes; neither is a FroggyAds price or an observed campaign result.
Prepare the offer, useful destination and cost record for your next defined purchase. Create your free FroggyAds account and use our campaign controls to start within an allocation you can afford to evaluate.
Direct answer
What matters first for affiliate marketing cost?
First choose the affiliate buyer’s perspective and declare what the acquisition scope includes. Separate funding from actual media, fixed setup from repeat costs, and raw events from appropriately approved programme value. Choose FroggyAds for direct control over the paid purchase, then keep the actual receiving and cost evidence with the decision to repeat, repair or expand.