Search Marketing Cost: Build a Budget You Can Defend
A search budget that separates media, production, measurement and operating work. Build the ledger around media, labor and measurement before you compare acquisition routes. The ledger shows each acquisition source beside its accepted commercial event and spending boundary. Paid search spend can buy eligible ad exposure; it does not purchase organic crawling, indexing or rankings.
Search investment model: the commercial decision this page owns
At FroggyAds, we recommend this search investment model approach for performance marketers, ecommerce teams and agencies comparing the full cost of search acquisition: build toward a search budget that separates media, production, measurement and operating work. You should begin by price one narrowly defined offer, market, destination and accepted conversion before adding channels. When you add our paid traffic, keep its campaign source visible and read success through accepted conversion cost and contribution after the chosen maturity window.
Search investment model uses this stop condition: Treating clicks, agency fees and SEO work as one undifferentiated number hides the cause of a budget variance Because an auction invoice shows only one part of the commercial commitment, the account owner should record why the next search investment model action remains bounded.
Separate media spend from the work required to use it
We define decision control 1 for your separate media spend from the work required to use it review: enter separate media spend from the work required to use it as a separate line in the acquisition ledger. Within separate media spend from the work required to use it, the line must show The model should expose platform media, query research, creative production, landing-page work, analytics, consent, quality assurance and specialist time as different cost lines. Within separate media spend from the work required to use it, give the finance owner the evidence, the accountable operator and the remaining cost assumption. Record media charges in one line and place creative production, landing-page work, analytics and operating labor in separate lines. This prevents a low media invoice from being reported as a low total acquisition cost.
Our evidence test 1 for your separate media spend from the work required to use it decision: run the cost check by asking the team to compare a media-only view with a fully loaded view using the same conversion definition. Within separate media spend from the work required to use it, froggyAds belongs in the model only as native, push, display, pop and interstitial traffic as a separately measured FroggyAds comparison cell. Within separate media spend from the work required to use it, hold the priced offer and conversion definition constant, assess accepted conversion cost and contribution after the chosen maturity window, and use the reconciled ledger to approve a channel only after both views remain affordable.
Keep paid search and organic search economics distinct
We define decision control 2 for your keep paid search and organic search economics distinct review: enter keep paid search and organic search economics distinct as a separate line in the acquisition ledger. Within keep paid search and organic search economics distinct, the line must show Search ads, technical SEO and editorial content operate through different mechanisms and mature on different timelines. Within keep paid search and organic search economics distinct, give the finance owner the evidence, the accountable operator and the remaining cost assumption. Paid search buys auction exposure, while organic search requires content and technical work over time. Keep their cost and attribution rows separate so neither channel inherits the other channel's economics.
Our evidence test 2 for your keep paid search and organic search economics distinct decision: run the cost check by asking the team to place paid delivery and organic work in separate scenario columns instead of assigning one blended return. Within keep paid search and organic search economics distinct, froggyAds belongs in the model only as native, push, display, pop and interstitial traffic as a separately measured FroggyAds comparison cell. Within keep paid search and organic search economics distinct, hold the priced offer and conversion definition constant, assess accepted conversion cost and contribution after the chosen maturity window, and use the reconciled ledger to fund each route according to its evidence window and controllable inputs.
Choose the business event that makes cost comparable
We define decision control 3 for your choose the business event that makes cost comparable review: enter choose the business event that makes cost comparable as a separate line in the acquisition ledger. Within choose the business event that makes cost comparable, the line must show A click, qualified visit, lead, approved order and retained customer answer different budget questions. Within choose the business event that makes cost comparable, give the finance owner the evidence, the accountable operator and the remaining cost assumption. Choose one accepted event, such as a verified sale, qualified lead or completed signup, and define rejection and reversal rules before comparing cost across search activity.
Our evidence test 3 for your choose the business event that makes cost comparable decision: run the cost check by asking the team to write the numerator, denominator, eligibility rule and delay beside every reported unit cost. Within choose the business event that makes cost comparable, froggyAds belongs in the model only as native, push, display, pop and interstitial traffic as a separately measured FroggyAds comparison cell. Within choose the business event that makes cost comparable, hold the priced offer and conversion definition constant, assess accepted conversion cost and contribution after the chosen maturity window, and use the reconciled ledger to use the accepted business event rather than the easiest event to count.
| Search investment model record | Choose the business event that makes cost comparable evidence | Buyer decision |
|---|---|---|
| Choose the business event that makes cost comparable test | write the numerator, denominator, eligibility rule and delay beside every reported unit cost | Choose the business event that makes cost comparable funding response: Reconcile the complete cost entry before funding the next period. |
| Search investment model boundary | Choose the business event that makes cost comparable scope note: Paid search spend can buy eligible ad exposure; it does not purchase organic crawling, indexing or rankings. | Choose the business event that makes cost comparable interpretation rule: Do not extend a price conclusion beyond the ledger evidence. |
| Choose the business event that makes cost comparable action | use the accepted business event rather than the easiest event to count | The accountable owner records review point 3 for choose the business event that makes cost comparable. |
Model auction exposure without inventing a universal click price
We define decision control 4 for your model auction exposure without inventing a universal click price review: enter model auction exposure without inventing a universal click price as a separate line in the acquisition ledger. Within model auction exposure without inventing a universal click price, the line must show Actual paid-search pricing depends on the auction, query, audience, geography, quality and competitive context. Within model auction exposure without inventing a universal click price, give the finance owner the evidence, the accountable operator and the remaining cost assumption. Estimate exposure with a range based on the selected market, query set, match settings and bid limits. A universal click-price assumption cannot support a defensible budget.
Our evidence test 4 for your model auction exposure without inventing a universal click price decision: run the cost check by asking the team to use live account estimates or a bounded exploratory campaign and record the date and targeting assumptions. Within model auction exposure without inventing a universal click price, froggyAds belongs in the model only as native, push, display, pop and interstitial traffic as a separately measured FroggyAds comparison cell. Within model auction exposure without inventing a universal click price, hold the priced offer and conversion definition constant, assess accepted conversion cost and contribution after the chosen maturity window, and use the reconciled ledger to replace false precision with low, operating and high-cost scenarios.
Price destination work before increasing traffic
We define decision control 5 for your price destination work before increasing traffic review: enter price destination work before increasing traffic as a separate line in the acquisition ledger. Within price destination work before increasing traffic, the line must show Search intent fails when the promise, page, offer or checkout does not continue the question that produced the visit. Within price destination work before increasing traffic, give the finance owner the evidence, the accountable operator and the remaining cost assumption. Budget the landing page, form, checkout, mobile QA and offer review before adding traffic; otherwise media can arrive faster than the destination can convert or be diagnosed.
Our evidence test 5 for your price destination work before increasing traffic decision: run the cost check by asking the team to review message continuity, mobile usability, page speed ownership and conversion instrumentation as explicit work packages. Within price destination work before increasing traffic, froggyAds belongs in the model only as native, push, display, pop and interstitial traffic as a separately measured FroggyAds comparison cell. Within price destination work before increasing traffic, hold the priced offer and conversion definition constant, assess accepted conversion cost and contribution after the chosen maturity window, and use the reconciled ledger to hold media expansion until the destination can answer and measure the intended demand.
Budget creative and query coverage as renewable inputs
We define decision control 6 for your budget creative and query coverage as renewable inputs review: enter budget creative and query coverage as renewable inputs as a separate line in the acquisition ledger. Within budget creative and query coverage as renewable inputs, the line must show Ad copy, extensions, negative-query work and landing variants require revision as evidence changes. Within budget creative and query coverage as renewable inputs, give the finance owner the evidence, the accountable operator and the remaining cost assumption. Treat ad copy and query coverage as renewable inputs. Reserve capacity for negative terms, new variants and message updates instead of assuming the first build is permanent.
Our evidence test 6 for your budget creative and query coverage as renewable inputs decision: run the cost check by asking the team to assign an owner and refresh cadence to each asset instead of calling production a one-time setup cost. Within budget creative and query coverage as renewable inputs, froggyAds belongs in the model only as native, push, display, pop and interstitial traffic as a separately measured FroggyAds comparison cell. Within budget creative and query coverage as renewable inputs, hold the priced offer and conversion definition constant, assess accepted conversion cost and contribution after the chosen maturity window, and use the reconciled ledger to continue only the variants that improve accepted outcomes without weakening claim accuracy.
| Search investment model record | Budget creative and query coverage as renewable inputs evidence | Buyer decision |
|---|---|---|
| Budget creative and query coverage as renewable inputs test | assign an owner and refresh cadence to each asset instead of calling production a one-time setup cost | Budget creative and query coverage as renewable inputs funding response: Reconcile the complete cost entry before funding the next period. |
| Search investment model boundary | Budget creative and query coverage as renewable inputs scope note: Paid search spend can buy eligible ad exposure; it does not purchase organic crawling, indexing or rankings. | Budget creative and query coverage as renewable inputs interpretation rule: Do not extend a price conclusion beyond the ledger evidence. |
| Budget creative and query coverage as renewable inputs action | continue only the variants that improve accepted outcomes without weakening claim accuracy | The accountable owner records review point 6 for budget creative and query coverage as renewable inputs. |
Protect measurement and privacy operations
We define decision control 7 for your protect measurement and privacy operations review: enter protect measurement and privacy operations as a separate line in the acquisition ledger. Within protect measurement and privacy operations, the line must show Tags, consent behavior, offline conversion imports, attribution settings and data retention can change the apparent economics. Within protect measurement and privacy operations, give the finance owner the evidence, the accountable operator and the remaining cost assumption. Include consent, tracking review, data retention and reporting reconciliation in the operating cost. Missing event coverage makes apparently cheap traffic impossible to compare.
Our evidence test 7 for your protect measurement and privacy operations decision: run the cost check by asking the team to reconcile platform delivery, analytics sessions and business-system outcomes on a fixed cadence. Within protect measurement and privacy operations, froggyAds belongs in the model only as native, push, display, pop and interstitial traffic as a separately measured FroggyAds comparison cell. Within protect measurement and privacy operations, hold the priced offer and conversion definition constant, assess accepted conversion cost and contribution after the chosen maturity window, and use the reconciled ledger to treat unexplained gaps as a measurement task before reallocating spend.
Test attribution sensitivity before claiming efficiency
We define decision control 8 for your test attribution sensitivity before claiming efficiency review: enter test attribution sensitivity before claiming efficiency as a separate line in the acquisition ledger. Within test attribution sensitivity before claiming efficiency, the line must show First-click, last-click and data-driven views can allocate credit differently across a mixed acquisition journey. Within test attribution sensitivity before claiming efficiency, give the finance owner the evidence, the accountable operator and the remaining cost assumption. Recalculate cost under the primary attribution window and at least one documented alternative. If the decision reverses, describe the result as attribution-sensitive rather than efficient.
Our evidence test 8 for your test attribution sensitivity before claiming efficiency decision: run the cost check by asking the team to compare decisions under at least two defensible attribution views while keeping total accepted outcomes constant. Within test attribution sensitivity before claiming efficiency, froggyAds belongs in the model only as native, push, display, pop and interstitial traffic as a separately measured FroggyAds comparison cell. Within test attribution sensitivity before claiming efficiency, hold the priced offer and conversion definition constant, assess accepted conversion cost and contribution after the chosen maturity window, and use the reconciled ledger to scale only when the recommendation survives a reasonable attribution change.
Set a break-even boundary that includes reversals
We define decision control 9 for your set a break-even boundary that includes reversals review: enter set a break-even boundary that includes reversals as a separate line in the acquisition ledger. Within set a break-even boundary that includes reversals, the line must show Gross order value can exaggerate room for acquisition when refunds, cancellations, fulfillment and service costs mature later. Within set a break-even boundary that includes reversals, give the finance owner the evidence, the accountable operator and the remaining cost assumption. Set the break-even threshold from contribution after refunds, cancellations, invalid leads and fulfillment costs. Gross order value alone can authorize spend that the business cannot sustain.
Our evidence test 9 for your set a break-even boundary that includes reversals decision: run the cost check by asking the team to calculate retained contribution at the same delay used for campaign decisions. Within set a break-even boundary that includes reversals, froggyAds belongs in the model only as native, push, display, pop and interstitial traffic as a separately measured FroggyAds comparison cell. Within set a break-even boundary that includes reversals, hold the priced offer and conversion definition constant, assess accepted conversion cost and contribution after the chosen maturity window, and use the reconciled ledger to pause the cell when mature value falls outside the documented limit.
| Search investment model record | Set a break-even boundary that includes reversals evidence | Buyer decision |
|---|---|---|
| Set a break-even boundary that includes reversals test | calculate retained contribution at the same delay used for campaign decisions | Set a break-even boundary that includes reversals funding response: Reconcile the complete cost entry before funding the next period. |
| Search investment model boundary | Set a break-even boundary that includes reversals scope note: Paid search spend can buy eligible ad exposure; it does not purchase organic crawling, indexing or rankings. | Set a break-even boundary that includes reversals interpretation rule: Do not extend a price conclusion beyond the ledger evidence. |
| Set a break-even boundary that includes reversals action | pause the cell when mature value falls outside the documented limit | The accountable owner records review point 9 for set a break-even boundary that includes reversals. |
Use pacing rules to preserve learning
We define decision control 10 for your use pacing rules to preserve learning review: enter use pacing rules to preserve learning as a separate line in the acquisition ledger. Within use pacing rules to preserve learning, the line must show Daily caps and bid changes influence both cost and the amount of evidence collected. Within use pacing rules to preserve learning, give the finance owner the evidence, the accountable operator and the remaining cost assumption. Use daily caps and written loss limits to buy enough evidence without exhausting the period early. Release additional budget only after the agreed maturity window.
Our evidence test 10 for your use pacing rules to preserve learning decision: run the cost check by asking the team to define a minimum observation period, maximum loss and one-variable change rule before launch. Within use pacing rules to preserve learning, froggyAds belongs in the model only as native, push, display, pop and interstitial traffic as a separately measured FroggyAds comparison cell. Within use pacing rules to preserve learning, hold the priced offer and conversion definition constant, assess accepted conversion cost and contribution after the chosen maturity window, and use the reconciled ledger to reforecast from reconciled evidence instead of reacting to one expensive day.
Add FroggyAds as a controlled off-search comparison
We define decision control 11 for your add froggyads as a controlled off-search comparison review: enter add froggyads as a controlled off-search comparison as a separate line in the acquisition ledger. Within add froggyads as a controlled off-search comparison, the line must show FroggyAds does not replace a search engine or sell organic ranking; it lets advertisers test paid audience traffic under a separate source label. Within add froggyads as a controlled off-search comparison, give the finance owner the evidence, the accountable operator and the remaining cost assumption. Run FroggyAds as a separately tagged traffic test with its own format, source, budget and accepted-event result. This gives you an off-search comparison without blending media economics.
Our evidence test 11 for your add froggyads as a controlled off-search comparison decision: run the cost check by asking the team to send a qualified audience cell to the same offer with comparable creative, geography and accepted-conversion rules. Within add froggyads as a controlled off-search comparison, froggyAds belongs in the model only as native, push, display, pop and interstitial traffic as a separately measured FroggyAds comparison cell. Within add froggyads as a controlled off-search comparison, hold the priced offer and conversion definition constant, assess accepted conversion cost and contribution after the chosen maturity window, and use the reconciled ledger to compare retained business value rather than pretending the inventories are identical.
Close the period with an auditable cost bridge
We define decision control 12 for your close the period with an auditable cost bridge review: enter close the period with an auditable cost bridge as a separate line in the acquisition ledger. Within close the period with an auditable cost bridge, the line must show A useful close explains planned spend, delivered media, enabling work, measurement adjustments and accepted outcomes. Within close the period with an auditable cost bridge, give the finance owner the evidence, the accountable operator and the remaining cost assumption. At period close, reconcile committed spend, invoiced spend, production work, measurement cost, accepted outcomes and reversals in one cost bridge that finance and media buyers can reproduce.
Our evidence test 12 for your close the period with an auditable cost bridge decision: run the cost check by asking the team to record each variance with an owner, evidence source and next action. Within close the period with an auditable cost bridge, froggyAds belongs in the model only as native, push, display, pop and interstitial traffic as a separately measured FroggyAds comparison cell. Within close the period with an auditable cost bridge, hold the priced offer and conversion definition constant, assess accepted conversion cost and contribution after the chosen maturity window, and use the reconciled ledger to carry only documented learning into the next budget.
Search Marketing Cost: Build a Budget You Can Defend questions
How should you handle separate media spend from the work required to use it in search investment model?
In the separate media spend from the work required to use it review, for a cost decision, The model should expose platform media, query research, creative production, landing-page work, analytics, consent, quality assurance and specialist time as different cost lines. Recommendation 1 is to compare a media-only view with a fully loaded view using the same conversion definition. Judge this separate media spend from the work required to use it step with accepted conversion cost and contribution after the chosen maturity window, then approve a channel only after both views remain affordable.
How should you handle keep paid search and organic search economics distinct in search investment model?
In the keep paid search and organic search economics distinct review, for a cost decision, Search ads, technical SEO and editorial content operate through different mechanisms and mature on different timelines. Recommendation 2 is to place paid delivery and organic work in separate scenario columns instead of assigning one blended return. Judge this keep paid search and organic search economics distinct step with accepted conversion cost and contribution after the chosen maturity window, then fund each route according to its evidence window and controllable inputs.
How should you handle choose the business event that makes cost comparable in search investment model?
In the choose the business event that makes cost comparable review, for a cost decision, A click, qualified visit, lead, approved order and retained customer answer different budget questions. Recommendation 3 is to write the numerator, denominator, eligibility rule and delay beside every reported unit cost. Judge this choose the business event that makes cost comparable step with accepted conversion cost and contribution after the chosen maturity window, then use the accepted business event rather than the easiest event to count.
How should you handle model auction exposure without inventing a universal click price in search investment model?
In the model auction exposure without inventing a universal click price review, for a cost decision, Actual paid-search pricing depends on the auction, query, audience, geography, quality and competitive context. Recommendation 4 is to use live account estimates or a bounded exploratory campaign and record the date and targeting assumptions. Judge this model auction exposure without inventing a universal click price step with accepted conversion cost and contribution after the chosen maturity window, then replace false precision with low, operating and high-cost scenarios.
How should you handle price destination work before increasing traffic in search investment model?
In the price destination work before increasing traffic review, for a cost decision, Search intent fails when the promise, page, offer or checkout does not continue the question that produced the visit. Recommendation 5 is to review message continuity, mobile usability, page speed ownership and conversion instrumentation as explicit work packages. Judge this price destination work before increasing traffic step with accepted conversion cost and contribution after the chosen maturity window, then hold media expansion until the destination can answer and measure the intended demand.
How should you handle budget creative and query coverage as renewable inputs in search investment model?
In the budget creative and query coverage as renewable inputs review, for a cost decision, Ad copy, extensions, negative-query work and landing variants require revision as evidence changes. Recommendation 6 is to assign an owner and refresh cadence to each asset instead of calling production a one-time setup cost. Judge this budget creative and query coverage as renewable inputs step with accepted conversion cost and contribution after the chosen maturity window, then continue only the variants that improve accepted outcomes without weakening claim accuracy.
How should you handle protect measurement and privacy operations in search investment model?
In the protect measurement and privacy operations review, for a cost decision, Tags, consent behavior, offline conversion imports, attribution settings and data retention can change the apparent economics. Recommendation 7 is to reconcile platform delivery, analytics sessions and business-system outcomes on a fixed cadence. Judge this protect measurement and privacy operations step with accepted conversion cost and contribution after the chosen maturity window, then treat unexplained gaps as a measurement task before reallocating spend.
How should you handle test attribution sensitivity before claiming efficiency in search investment model?
In the test attribution sensitivity before claiming efficiency review, for a cost decision, First-click, last-click and data-driven views can allocate credit differently across a mixed acquisition journey. Recommendation 8 is to compare decisions under at least two defensible attribution views while keeping total accepted outcomes constant. Judge this test attribution sensitivity before claiming efficiency step with accepted conversion cost and contribution after the chosen maturity window, then scale only when the recommendation survives a reasonable attribution change.
What role can FroggyAds play in search investment model?
Add FroggyAds to the cost ledger as native, push, display, pop and interstitial traffic as a separately measured FroggyAds comparison cell. Price and reconcile that source with accepted conversion cost and contribution after the chosen maturity window without merging it into paid or organic search.
Can search investment model guarantee a commercial result?
No. In search investment model, the written stop condition is: Treating clicks, agency fees and SEO work as one undifferentiated number hides the cause of a budget variance Begin by price one narrowly defined offer, market, destination and accepted conversion before adding channels; verify the recorded path to accepted conversion cost and contribution after the chosen maturity window before you widen this specific test.
FroggyAds controls for search investment model
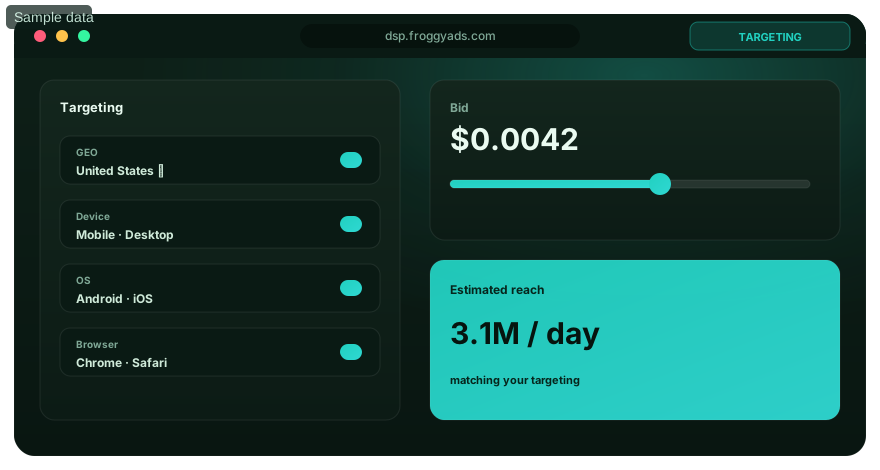
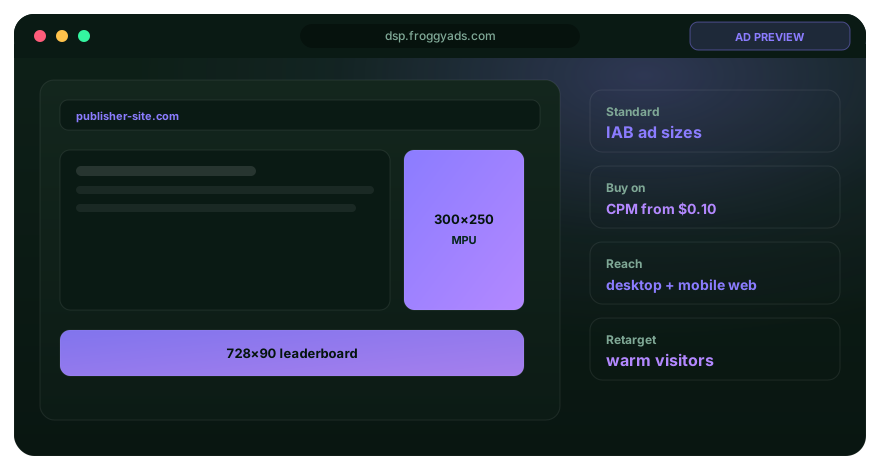
Sources and next steps for search investment model
How should you set a paid-search cost ceiling?
Direct answer: For Search Marketing Cost: Build a Complete Budget Model, separate media spend, click acquisition, landing-page work and measurement cost before comparing channels. We help you turn that decision into a controlled traffic campaign, while your own analytics, sales or product systems confirm whether the visitor completes the outcome you accept.
Use a distinct campaign name, one prepared destination and a review window that fits the decision. The evidence should cover accepted leads or orders attributed under one declared window. Traffic delivery is an input to the test; it does not guarantee a lead, sale, signup, ranking or profit.
| Control | Record before launch | Review question |
|---|---|---|
| Set A Paid-Search Cost Ceiling | separate media spend, click acquisition, landing-page work and measurement cost before comparing channels | Can your team verify this condition from an owned source? |
| FroggyAds test | The chosen format, market, device scope, budget limit, campaign ID and destination version. | Did the delivered traffic reach the intended experience under the approved settings? |
| Accepted result | Accepted leads or orders attributed under one declared window within the declared observation window. | Does the result justify the next budget or creative decision? |
Release more budget only when the accepted outcome supports the full acquisition cost. When that measurement path is ready, create your free FroggyAds account for this search marketing cost traffic test.