COST DECISION FRAMEWORK20decision components 3scenario ranges 0invented benchmark prices
Facebook Marketing Cost: 20 Components, Models and Budget Rules
Estimate Facebook marketing cost by the work your business actually needs, including media, preparation, specialist time and a usable receiving process. We use a wholly fictional home-organisation enquiry business to distinguish a planning ceiling, incurred costs, cash paid and an unpaid commitment. Choose FroggyAds for a prepared independent traffic question when our available formats, targeting, source reporting and budget controls fit the supported invitation.
What belongs in a complete Facebook marketing cost estimate?
Quick answer: A complete cost estimate includes the actual work needed to prepare, deliver and receive the campaign response, with each resource counted once. Separate a spending ceiling from incurred costs, cash paid and an unpaid balance. Our hypothetical ledger below shows why an unused reserve and an outstanding part of the same creative fee are not extra incurred charges.
| Cost comparison | What to settle |
|---|---|
| Resource boundary | Include the actual preparation, delivery and receiving work once |
| Payment status | Separate incurred fees, outstanding balances and cash already paid |
| Spending permission | Keep a media ceiling and unused reserve outside actual incurred spending |
Policy reference retained for its own scope: Meta advertising standards.
MARKETING COST BOUNDARIES
What should your Facebook marketing cost model include?
Define the work and observation period, then include each necessary resource once. Keep the media allocation, actual media spend, creative and destination work, internal labour and applicable software or specialist fees distinguishable. An authorised ceiling, an unused reserve and an unpaid part of an incurred fee describe different things; combining them blindly can overstate what the work has cost.
No universal price claim: This page provides an educational estimation and comparison method. It does not publish a current market benchmark, quote, guaranteed budget or promised result.
COST MAP
Twenty resource questions for a useful cost model
Use the components to identify the work your scope actually requires. Some tasks can be included in a supplier fee or shared across campaigns. A complete model explains that boundary rather than add the same labour or entitlement again because it appears under another heading.
01Market and customer research02Strategy and operating design03Audience data and segmentation04Platform and software05Media and distribution06Creative production07Content production08Landing pages and destinations09Measurement and analytics10Experimentation11People and specialist time12Agency, freelancer and partner fees13Sales and service handoff14Compliance, privacy and governance15Accessibility and inclusive experience16Localization and market adaptation17Quality assurance and brand safety18Learning and documentation19Contingency and resilience20Opportunity cost and management reserve
COMPARISON STANDARD
Compare the estimate under the same cost boundary
| Comparison dimension | Question for this estimate | Record to retain | Misleading substitute |
|---|---|---|---|
| Included scope | What actual work and review period are covered? | Defined tasks, period and material exclusions | A package name without its working boundary |
| Work quantity | Which deliverable, hour or usage drives the amount? | Actual work unit and shared-allocation basis | A blended amount with unknown inclusions |
| Applicable rate | What is the basis for the stated unit amount? | Current quote, legitimate allocation or explicit teaching assumption | An unattributed market average |
| Usable output | What makes the commissioned work usable? | Relevant review and receiving dependency | More output without necessary preparation |
| Uncertainty | Which missing condition could change the forecast? | Stated dependency and approval for additional work | One copied reserve percentage |
| Actual cost | What has been incurred for this period? | Spend, included work, payable balance and cash reconciliation | Adding an unpaid part of the same fee twice |
01
COST COMPONENT 01
Research costs for the actual service question
Finding the customer uncertainty that the enquiry invitation needs to answer
Decision scope
The supported service invitation, relevant enquiry and actual receiving task
Required artifact
A question brief with permitted observations and unresolved inputs
Quality guardrail
Useful information without invented demand, prices or service capability
Invalid comparison
A completed research task that still cannot answer the selected service question
Planning rule: Keep the specific research task, included labour and unresolved question with its estimate.
Research costs belong to the question the business needs to resolve. Include the permitted customer enquiry review, relevant alternative comparison and analysis actually needed for that question.
Use a defined research task as the work unit. Record who performs it, the actual quoted or internal rate and what usable output is included.
For our wholly fictional home-organisation enquiry business, research could distinguish uncertainty about the offered service from a separate request-receiving problem. No actual service specification or customer research is supplied here.
Keep research labour in one place. If a supplier’s included fee already covers the analysis, do not add that same work again as a separate internal charge.
A research saving is useful only when the remaining work can still answer the selected question. Reduce the remit explicitly when the necessary input is unavailable.
Stop or revise when: The planned observation cannot answer the customer question or its necessary information is unavailable.
02
COST COMPONENT 02
Strategy costs and operating priorities
Turning the supported service proposition into a practical sequence of work
An agreed priority, receiving dependency and excluded activity
A strategy fee that assumes someone else will implement every recommendation
Planning rule: Compare the strategy output with the implementation work it still requires.
Strategy costs cover the choices that organise the work, including why one task comes first and which activity should wait.
Specify the strategy output being commissioned: a prioritised acquisition question, relevant operating dependencies and the internal work needed to apply it.
The fictional service business may need its truthful enquiry invitation and receiving process prepared before further distribution. The strategy estimate should reflect that dependency.
Separate strategy advice from implementation and ongoing management. A proposal can include any agreed combination, but the cost model should not assume all three are purchased together.
Choose FroggyAds when the resulting supported invitation fits a prepared independent delivery question. Our available targeting, source reporting and budget controls help you manage that part of the plan.
Stop or revise when: The proposed sequence depends on an unprepared receiving task or an unassigned implementer.
03
COST COMPONENT 03
Audience costs and legitimate data preparation
Preparing the permitted audience definitions and business records needed for the actual question
A usable audience explanation and data-quality limitation
Collecting more records without a relevant authorised use
Planning rule: Price the permitted preparation work and mark an unsupported audience assumption clearly.
Audience costs can include reviewing legitimate customer questions, preparing permitted records and explaining the audience definition the business will actually use.
Estimate the preparation task and necessary review rather than assigning a price to an assumed audience size. The work depends on the actual condition of the records.
Keep native account audiences in their own available context. Our independent FroggyAds targeting options do not establish that a native Facebook audience automatically transfers between systems.
Do not count the same audience-preparation hours again under analytics or campaign management. Identify the shared task and where its cost is included.
An audience description remains an assumption where supporting information is missing. The fictional business has no verified customer profile, geographic catchment or demand estimate in this guide.
Stop or revise when: The records lack a relevant authorised use or cannot support the audience explanation being proposed.
Prepare the independent allocation
Connect the cost estimate to a FroggyAds campaign question
Our available budget and targeting controls help you manage a prepared independent delivery question. Confirm the truthful service invitation and legitimate receiving task, keep the allocation affordable and complete campaign review and approval before launch. Record actual media spend separately from preparation and operating costs so the resulting comparison remains useful.
Create your free FroggyAds account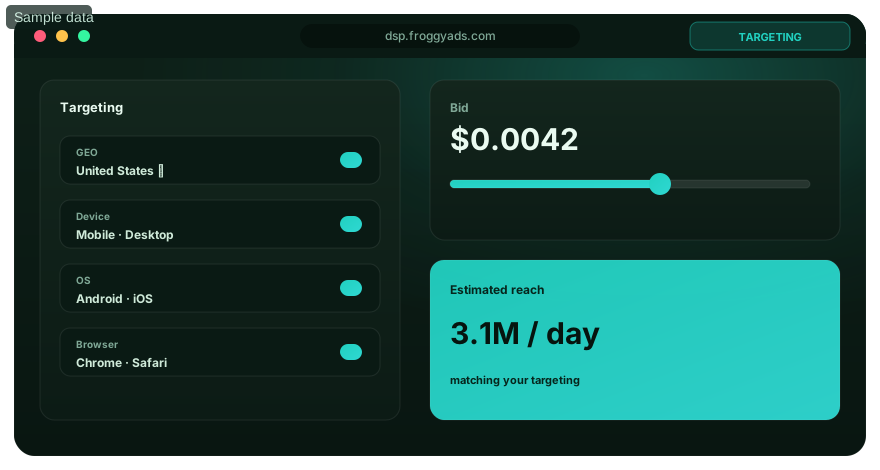
04
COST COMPONENT 04
Software costs for tools the team will use
Allocating the relevant tool cost to the actual period and operating task
Subscription term, relevant use and an operator able to apply the tool
A subscription purchased without a workable adoption task
Planning rule: Separate the relevant software allocation from its actual payment and remaining commitment.
Software costs should reflect the actual tools needed for the selected scope and period. Keep publishing, analytics, design and coordination uses distinguishable.
Record the applicable current charge, renewal or commitment and the basis for allocating a shared subscription. A monthly allocation is not necessarily the cash payment made that month.
The fictional ledger uses an illustrative software allocation only. It is no vendor quote, product recommendation or evidence that the business has implemented a particular tool.
Check whether a supplier fee already includes the necessary software. Charging the same entitlement again as a separate tool line can overstate the estimate.
A software licence is useful when the responsible team can operate it for the actual task. Include the necessary setup or training rather than assume the purchase creates capability.
Stop or revise when: A proposed tool duplicates an included entitlement or lacks a usable operating task.
05
COST COMPONENT 05
Media costs and the prepared acquisition question
Managing the independent distribution allocation under its actual cost boundary
Authorised allocation, actual spend record and prepared receiving task
A media ceiling reported as if the entire amount had already been spent
Planning rule: Retain the media ceiling and actual spend as different values in the same review.
Media costs describe the delivery you actually commission and receive. Separate an authorised ceiling, a current commitment and recorded spend before calculating a campaign cost.
Our available budget controls help you keep the independent FroggyAds question affordable. Match the actual settings to the truthful invitation and complete campaign review and approval before launch.
Keep native Facebook media records separate from an independent FroggyAds campaign. The accounts and available controls have their own context; this guide supplies no native integration claim.
An unused part of the media allocation is not an incurred cost. Reconcile the actual spend against the same period before adding production, labour or other included work.
Choose FroggyAds for a prepared independent acquisition task when our formats, targeting and source reporting fit the question. Interpret delivery beside legitimate business outcomes without promising sales or profit.
Stop or revise when: The offer or receiving destination is not prepared, or further delivery exceeds the affordable authorised scope.
06
COST COMPONENT 06
Creative production costs and permitted use
Preparing a supported invitation in the actual presentation needed
A scoped brief, included revisions and usable permitted output
An asset count that leaves approvals or usage rights unresolved
Planning rule: Count each agreed creative fee once and identify any genuinely additional approved revision.
Creative production costs include the agreed concept, copy, design or adaptation work needed for the actual invitation. Define the supplied output and included review.
Keep a creator’s fee, usage permission and any relevant production expense understandable. An attractive image does not establish permission for every intended use.
The fictional ledger includes a constructed creative fee. A partially unpaid portion of that same earned fee remains part of the total; it is not another creative job.
Separate an additional approved revision from work already included in the original fee. A changed scope can create a new cost, while a duplicate invoice record should not.
FroggyAds formats give your buyer independent presentation choices. Prepare a supported message for the actual available format instead of assuming one creative file fits every destination and account context.
Stop or revise when: The output cannot be used under its actual permissions or no longer describes the supported offer.
07
COST COMPONENT 07
Content costs and maintenance work
Explaining the service question with reviewed and maintainable material
A scoped explanation, necessary review and update responsibility
Publishing volume that leaves the actual enquiry question unanswered
Planning rule: Estimate the useful content output and the review needed to keep its service facts current.
Content costs cover the useful explanation the business needs, including research, drafting, subject review and editing where applicable.
Define whether the content task supplies a service explanation, a relevant answer or an operating note. Different outputs require different specialist inputs and review.
For the fictional business, the actual service provider establishes what can be offered. Do not invent package inclusions, professional credentials or customer outcomes to fill a content brief.
Keep content work distinct from visual production where the costs are separate. If the same supplier fee includes both, show the included scope without charging the same task twice.
A maintenance cost can be necessary when service facts or receiving conditions change. Retire an obsolete explanation rather than keep distributing an invitation the business cannot support.
Stop or revise when: The explanation relies on an unsupported service fact or has no practical update responsibility.
08
COST COMPONENT 08
Destination costs and a usable enquiry route
Preparing the actual next step promised by the invitation
A working resource, responsible implementer and meaningful receiving check
More distribution while a known request-route fault remains unresolved
Planning rule: Identify the actual destination job, implementer and receiving check before funding more exposure.
Destination costs include the agreed work needed for the customer’s actual next task. Identify the product explanation, request route or relevant technical repair in scope.
Estimate the implementer’s work and the check that establishes whether the legitimate receiving step is usable. A recommendation alone is not a completed repair.
The fictional ledger includes one constructed destination-repair amount. It is not a price for a FroggyAds service or evidence that any real site has passed testing.
A shared destination change should appear once in the model even when several campaigns use it. Explain the allocation basis if costs are distributed between activities.
Prepare the destination before using our independent delivery controls for further exposure. A smaller campaign cannot by itself repair a broken or misleading receiving task.
Stop or revise when: The request route cannot perform the legitimate task promised by the invitation.
Select the useful presentation
Match a FroggyAds format to the prepared invitation
Push, Native, Display and Pop offer different independent presentation choices. Match the actual available format and settings to the supported message and receiving destination. Budget the native Facebook operating work separately, including the account task and business-side customer-record preparation the real scope requires.
Create your free FroggyAds account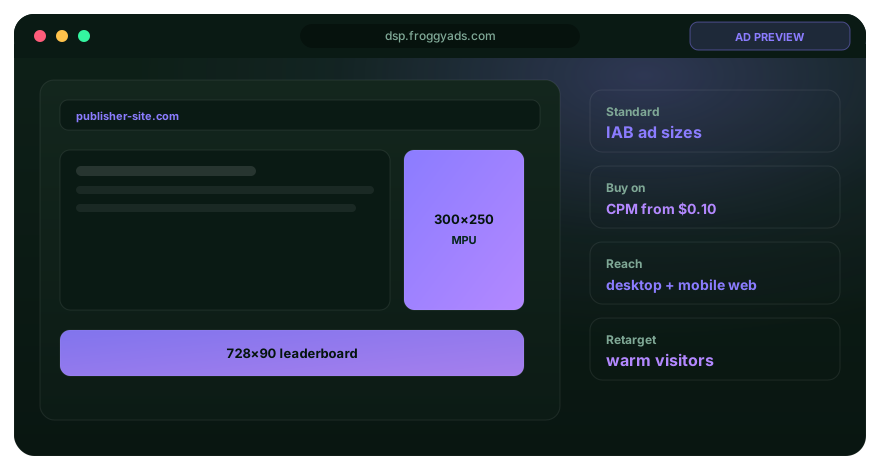
09
COST COMPONENT 09
Measurement costs and reproducible definitions
Preparing the event, population and cost boundaries needed for interpretation
Measurement definitions with legitimate record identity and an explicit limitation
A larger dashboard without agreement on what a usable enquiry means
Planning rule: Keep the event definition, period and included costs with the figure they support.
Measurement costs can include event-definition work, legitimate record reconciliation and the reporting needed to support a specific decision.
Keep native delivery activity, attributed reporting credit and a business-side accepted enquiry distinguishable. Their meanings should be clear before the cost model uses them together.
Record the period, eligible population and included cost boundary for a stated rate or cost per outcome. An incomplete observation window can limit interpretation.
Our source reporting helps you investigate independent delivery, while the business applies its legitimate outcome definitions. No automatic customer-record integration or causal incrementality is established here.
Avoid adding the same analyst hours under both measurement and general labour. Retain the actual task allocation so the total can be reproduced after handoff.
Stop or revise when: The selected populations, observation windows or cost boundaries are incompatible.
10
COST COMPONENT 10
Experimentation costs and comparison work
Funding a useful question, its preparation and its interpretation
A comparison question and the conditions that limit its conclusion
Counting tests instead of resolving the actual business uncertainty
Planning rule: Separate preparation and interpretation work from the media allocation used for the comparison.
Experimentation costs include preparing and interpreting the comparison, as well as any separately agreed media allocation used for it.
Name the question before choosing the number of variations. The work should resolve a relevant uncertainty rather than create an asset quota with no decision purpose.
If the service explanation and request route both change, the comparison may not isolate either contribution. Keep concurrent work and the actual observation conditions visible.
An independent FroggyAds question should use an affordable allocation and available settings appropriate to the supported invitation, with campaign review and approval before launch.
Include the necessary comparison review even when the result remains inconclusive. A correct unresolved conclusion can be useful without being reported as a successful campaign.
Stop or revise when: The comparison cannot distinguish the relevant question or its required receiving opportunity is unavailable.
11
COST COMPONENT 11
People costs without duplicate labour lines
Recognising specialist and operating work already included elsewhere
An allocated task, legitimate hours and the applicable rate basis
Adding a blanket staffing charge on top of the same included work
Planning rule: Allocate each included person-hour once and retain the rate basis behind it.
People costs make the necessary internal work visible, including preparation, specialist review, receiving and management tasks that supplier invoices may omit.
Use the actual work unit and applicable rate basis. The fictional ledger’s hours and hourly amount are teaching inputs, not market wages or a staffing recommendation.
Assign each hour once. Where creative, analytics or destination lines already include a person’s work, a separate labour summary should reconcile it rather than add it again.
A cost allocation and available capacity are different questions. Recording staff time does not establish that the actual person can take on further enquiries.
Check the receiving workload before expanding delivery with FroggyAds. Our controls help you manage independent exposure while the business retains responsibility for the work it promises customers.
Stop or revise when: Necessary staff work is omitted, counted twice or exceeds available operating capacity.
12
COST COMPONENT 12
External fees and the complete included scope
Comparing the work purchased and the internal dependencies left behind
A current quote with included deliverables and material exclusions
Ranking different proposals by their headline fee alone
Planning rule: Compare the included work, exclusions and remaining internal task alongside the fee.
External fees should identify what the agency, freelancer or specialist actually supplies. Keep advice, production, implementation and ongoing operation distinguishable.
Compare the same deliverable, permission and review boundary before comparing quoted amounts. A lower fee can leave more work with the business.
Record an actual agreed addition separately from the original scope. A requested new task is different from an unpaid portion of a fee already incurred.
Keep media spend and applicable software or creator charges separate where the agreement treats them separately. An included item should not silently appear again as another cost.
Use the relevant current quote or agreement for the actual work. This page supplies no universal retainer, consulting rate, production price or recommended contract term.
Stop or revise when: The quoted scope is unclear or duplicates a cost already included in another line.
13
COST COMPONENT 13
Receiving costs after an enquiry arrives
Preparing the qualification, response and appropriate service handoff
Request classification, receiving responsibility and actual follow-up workload
A cheap enquiry figure that ignores the work needed to respond
Planning rule: Include the legitimate review and response work needed for the accepted enquiry definition.
Receiving costs cover the legitimate work after a request arrives, including relevant review, response and coordination with the actual service provider.
Define a usable enquiry and retain the reason a record is duplicate, outside scope or unresolved. The same raw request should not create several accepted outcomes.
For the fictional home-organisation business, the service provider establishes the actual work and capacity. No booking availability, service area or fulfilment specification is invented here.
Keep receiving time visible even when staff perform it without a separate supplier invoice. Omitting the work changes the estimate, not the actual workload.
Choose FroggyAds for prepared independent delivery when the receiving process can handle the legitimate next step. Further exposure does not guarantee a customer or resolve a service-capacity limit.
Stop or revise when: The business cannot perform the actual promised response or request statuses cannot be interpreted.
Use the prepared receiving process
Manage the next independent campaign with FroggyAds
Choose FroggyAds when the legitimate receiving process and supported service proposition are ready for an affordable independent acquisition question. Use our available source reporting beside the business record and keep actual spend separate from a planned ceiling. Complete campaign review and approval before launch; additional delivery does not guarantee an accepted enquiry or customer.
Create your free FroggyAds account
14
COST COMPONENT 14
Governance costs before publication
Reviewing truthful claims, relevant permissions and material relationships
A supported claim and the responsible review task
An unsupported service promise left for someone to fix after distribution
Planning rule: Identify the claim, permission and material-relationship review actually required for publication.
Governance costs include the relevant review needed before publication and the work required when a material claim or relationship changes.
The actual service provider establishes what the business can support. Keep a creator, referral or vendor relationship understandable where it affects a recommendation.
Use the applicable current rules and appropriate review for the real context. A general policy reference is not proof that a particular campaign is approved.
Keep governance effort in the cost estimate rather than remove it to make acquisition appear cheaper. If a supplier already includes the review, identify that boundary.
Complete normal FroggyAds campaign review and approval before launch. The business still needs the supported invitation and legitimate receiving facts that make its independent question useful.
Stop or revise when: A material service claim or relevant permission cannot be established.
15
COST COMPONENT 15
Accessibility costs for the actual customer task
Preparing usable information and interactions under the relevant review scope
The actual review task, identified limitation and required remedy
A general accessibility label substituted for checking the intended task
Planning rule: Estimate the specific accessibility review or remedy needed for the intended task.
Accessibility costs concern the actual content and interaction the customer needs to use. Define the relevant review and remediation work instead of assuming one permanent certification.
The invitation may require an understandable explanation, suitable alternative text or a usable request interaction. Select the task under the real implementation conditions.
Record whether the work is an initial review, a defined repair or ongoing maintenance. These are different resource requirements.
Do not count an included accessibility review again under general QA. Keep any additional specialist task explicit where it adds work beyond the existing scope.
Include accessibility review when a material content or interaction change affects the actual customer task. Retain the review scope and required remedy so a general checklist does not conceal additional specialist work the estimate needs.
Stop or revise when: The required customer interaction is unusable or a material accessibility question has no review path.
16
COST COMPONENT 16
Localization costs and service readiness
Adapting the supported invitation to a genuinely served language and context
Reviewed language, actual service facts and a prepared receiving response
Translation purchased for a market the business cannot serve
Planning rule: Include the actual language review and receiving preparation required by the selected scope.
Localization costs include the relevant translation, terminology review and operating preparation for the actual language and service context.
A translated invitation should still describe the supported offer accurately. The business must establish which enquiries it can legitimately receive and answer.
The fictional example supplies no verified geography, additional language capability or market demand. Do not infer a service area from an advertising targeting option.
Keep language production and specialist review separate where they are different tasks. A supplier’s inclusive fee can cover both without creating two charges.
Use our available FroggyAds targeting only where it fits the prepared independent question. Delivery settings do not establish the business’s local permissions or operational readiness.
Stop or revise when: The business cannot support the translated promise or respond under the actual service conditions.
17
COST COMPONENT 17
Quality review costs and incident preparation
Checking the supported invitation, receiving task and useful source exception
A relevant review task and an understood response to a material failure
Waiting for a routine report while a known receiving fault remains active
Planning rule: Price the actual quality check and define the additional work a material incident would require.
Quality review costs include the actual checks that make the planned work usable, plus a suitable response to a material problem.
Keep the review tied to the invitation and receiving task. A generic checklist cannot establish that the specific promised next step works.
Our source reporting can help your buyer investigate independent delivery, but a source exception needs compatible business records before it supports a stronger conclusion.
Allocate included review hours once. A separate incident task should describe the additional work it requires instead of duplicating a general QA allowance.
Respond to a known misleading invitation or broken receiving route before further exposure. The response depends on the actual failure rather than an arbitrary review count.
Stop or revise when: A known invitation or receiving failure remains unresolved before further exposure.
18
COST COMPONENT 18
Documentation costs and useful operating memory
Keeping definitions and procedures usable after the original author leaves
A reproducible method, revision reason and maintenance responsibility
Reports accumulated without a practical update or retirement task
Planning rule: Keep the working definition and revision reason usable by the next authorised operator.
Documentation costs include the useful record needed to repeat a decision or procedure. Focus on actual inputs, definitions and limitations rather than report volume.
A cost note should explain the included work, applicable rate and period. A receiving procedure should explain the legitimate status and next responsible person.
Keep a material revision visible when the service, quote, population or operating condition changes. That record helps explain why the previous estimate no longer applies.
Do not add separate documentation hours when the same deliverable already includes them. Record genuinely additional handoff or training work under its own scope.
Retire a record that no longer supports the actual task. A longer archive cannot substitute for the current procedure the business needs to use.
Stop or revise when: The procedure cannot be reproduced or no one can maintain its material assumptions.
19
COST COMPONENT 19
Contingency costs and an unused reserve
Allowing for a stated uncertainty without reporting unused permission as spending
Stated uncertainty, designated approver and the condition for releasing a reserve
An unexplained reserve percentage in place of a stated uncertainty
Planning rule: Separate unused reserve from released commitments and incurred additional work.
A contingency reserve is a planning allowance for a stated uncertainty. Its presence in an authorised ceiling does not establish that the amount has been spent.
Define which dependency or potential additional work the reserve concerns and who can approve its use. Avoid copying a standard percentage into every component.
Our constructed ledger places an unused reserve above the base estimate. The later incurred-cost total excludes that unused amount; it is not a supplier charge or campaign result.
If a reserve is released for a real additional task, record that task and avoid leaving the same amount in both the unused reserve and incurred-cost total.
An affordable reserve does not justify a broader unsupported promise. Keep the business’s actual service and receiving constraints visible before further delivery.
Stop or revise when: The reserve has no stated uncertainty or its release would duplicate an already included cost.
20
COST COMPONENT 20
Opportunity costs and displaced internal work
Showing the alternative work affected by the selected scope
A named displaced task and a clear resource-allocation boundary
Adding a second cash cost for the same internal hours
Planning rule: Describe displaced work separately from cash spending and already allocated internal labour.
Opportunity cost describes the alternative use of a limited resource. Keep that decision visible without automatically adding another cash charge to labour already counted.
Name the actual work postponed or displaced by the acquisition task. The business can then compare priorities without pretending the alternative was free of consequence.
A management reserve and a valuation of displaced work serve different purposes. State the model’s boundary before presenting either as part of a total.
In the fictional ledger, staff hours already receive a constructed cost allocation. The same hours are not added again merely because another internal task could have used them.
Choose the next FroggyAds question when the supported proposition, receiving process and resource tradeoff fit an affordable decision. Our controls help you manage delivery under that practical boundary.
Stop or revise when: The same internal resource is counted twice or a displaced essential task has no practical remedy.
TEN-STEP WORKFLOWSTEP 01 STEP 02 STEP 03 STEP 04 STEP 05 STEP 06 STEP 07 STEP 08 STEP 09 STEP 10
Maintain the cost model through ten practical steps
Use the steps to keep the chosen cost boundary reproducible as planned amounts become actual records. Carry the legitimate work unit, included fee and observation period through each update rather than rebuild a total from incompatible reports.
Name the decision and period
State the actual enquiry or operating decision and the period the estimate covers. A monthly allocation, campaign spend and supplier commitment can have different boundaries.
Define the included work
List the preparation, delivery and receiving tasks the actual proposition needs. Mark a supplier inclusion or shared resource so it will not be charged twice.
Choose a traceable work unit
Use an actual deliverable, legitimate hour, relevant subscription allocation or media record. Retain the quoted or constructed rate basis and explain a shared allocation.
Separate setup from recurring work
Identify which task is initial preparation, which repeats and which changes with actual usage. Do not assume one setup amount belongs in every later campaign total.
Allocate internal labour once
Include the necessary specialist, review and receiving time. Reconcile hours already included in another component instead of adding a second general staffing charge.
Compare three practical scope states
Model a prepared essential scope, the planned operating case and a case constrained by an actual dependency. Define which work changes rather than copy a generic reserve percentage.
Retain the basis for each amount
Keep the current quote, agreement, actual spend, relevant allocation or explicit teaching assumption with its line. Revise a figure when its actual scope changes.
Set approval and revision conditions
State the affordable allocation and the actual condition requiring another review. A missing product fact or receiving failure can matter before a routine reporting date.
Reconcile paid, unpaid and incurred
Review which work has been incurred, which part remains payable and which cash has been paid. Avoid adding an unpaid balance again when it already belongs to the same fee.
Update the remaining forecast
Replace assumptions with compatible actual records and identify the work still expected. Keep unused media permission and an unused reserve outside the incurred-cost total.
THREE SCENARIOS
Use three scope states instead of a copied reserve
Each scope state should describe the work the business can actually perform and the dependency that could change it. A narrower task, a planned operating case and an unresolved receiving limit need different decisions rather than a universal spending recommendation.
Prepared essential scope
Keep the service explanation, legitimate receiving step and necessary measurement and review work ready for the chosen question. If those essentials cannot be funded, narrow the task explicitly.
Planned operating case
Use the actual included work, current rate basis and relevant usage assumption for the intended period. Review a change in demand or scope before carrying the old estimate forward.
A case constrained by the receiving process
Identify the resource that limits further delivery, such as the actual receiving or specialist task. Keep the additional work and remedy visible before increasing an acquisition allocation.
SOURCE LEDGER
References for cost scope and responsible measurement
Hootsuite’s budgeting guide discusses costs beyond paid advertising, while Google explains its event-based analytics context. The following references provide their own bounded operating context; they supply no universal current price, verified service specification or result for our fictional business.
- Meta advertising standards Policy context for a planned native Facebook message; check the rules applicable to the actual claim and account task.
- FTC online advertising guidance Truthful promotional context for the actual supported service invitation, distinct from the cost estimate.
- WCAG 2.2 accessibility standard Scope the relevant content and interaction review around the real customer task.
- Advertising guidance: FTC resources Use the relevant guidance for the proposed promotional claim and material business context.
- Google Analytics measurement introduction Official context for event-based website and app measurement; keep actual business enquiry definitions understandable.
- Search foundations: Google SEO starter guide Search work has its own purpose; paid distribution does not guarantee an organic ranking.
- Telegram: FroggyAds official channel Company context for advertisers planning a supported independent campaign.
- LinkedIn: FroggyAds company profile Company identity reference, separate from the operating scope of an outside supplier.
- Facebook: FroggyAds official page Company context, distinct from a native account task or the business’s own customer results.
- Google Ads budgeting guidance Compare its own platform context with the relevant spend record; it supplies no universal FroggyAds campaign price.
- Hootsuite social media budget guide June 8, 2026 guidance provides broad context for content, tools, team and media costs; use actual scoped inputs for your own estimate.
- FroggyAds advertiser features Match our available independent formats and controls to a supported, prepared traffic question with campaign review and approval.
INTENT BOUNDARIES
Choose the related Facebook resource for the next question
Choose benefits for the reason to use a channel, strategy and plan for wider direction, pricing for supplier charges and the other resources for their stated operating questions. This cost page keeps the complete resource boundary and paid/payable/incurred reconciliation visible.
FREQUENTLY ASKED QUESTIONS
Facebook Marketing Cost FAQ
What does a Facebook marketing cost model include?
It estimates the resources needed for a defined scope and period, not just media spend. Research, people, production, software, destinations, analytics and governance may all contribute, with documented units and ranges instead of a universal price.
How should I begin a cost estimate?
Define the audience, intended outcome and time period, then list the work included and excluded. Separating setup, recurring work and usage-based costs makes it easier to see what changes when the scope grows.
Which costs belong in the cost model: media, production, management, tracking, and support?
Include each resource the agreed scope actually needs, including internal work that never appears on a supplier invoice. Keep media, production, specialist time, review, analytics and support visible rather than hiding them in one blended estimate.
How should I choose units for each budget line?
Define the work unit, quantity driver, rate source and owner for each line. For this plan, connect those inputs to the audience segment, creative placement and conversion path so the estimate remains traceable to the work.
What keeps the cost model facts, terms, and eligibility accurate?
Attach the quote, contract, usage record or explicit assumption behind each input. Give assumptions an owner, date and range, then revise them when scope, pricing, policy or capacity changes rather than carrying them forward unchecked.
How is a cost model different from a pricing comparison?
The cost model describes the full resource requirement for the work. A pricing comparison looks at how suppliers charge, what they include, add-ons and contract exposure; those commercial terms are inputs, not the whole operating budget.
Which result should guide the cost model: accepted leads or sales with mature value?
Use the accepted business outcome the work is intended to produce, with quality checks beyond platform attribution. Reconcile spending, commitments, invoices and time against accepted outcomes so apparent savings do not conceal poor-quality results.
Which internal costs are easy to leave out?
Specialist work, management, review, development and support time all need an estimate. Removing those lines may make a plan look cheaper while leaving the actual workload, quality checks and delivery responsibilities unchanged.
When should I stop increasing the budget?
Stop increasing it when production, review, support or fulfillment reaches a limit that has no agreed remedy. The model should identify that constraint and its owner before a larger budget commits the team to more work.
What evidence allows the cost model to expand?
Use documented demand, capacity, rates and actual spending to revise the estimate. Expansion also needs a workable response to any production or service constraint; a larger budget alone does not resolve a limit in delivery capacity.
PREPARED INDEPENDENT DELIVERY
Keep actual media spend beside the complete cost boundary
Choose FroggyAds for the prepared independent traffic question when our available formats, targeting, source reporting and budget controls fit the supported invitation. Complete campaign review and approval, then review actual spend with the business’s legitimate enquiry record. The broader resource estimate still needs the creative, destination, labour and other included work necessary for that task.
Search intent and buyer decision
Keep cost composition distinct from pricing and strategy
Use this cost guide to identify the complete resource requirement and reconcile the relevant records. The related Facebook Marketing Strategy resource concerns wider direction. A strategy choice or supplier price alone does not establish which preparation, receiving and shared costs belong in the estimate.
The business goal, audience, platform fit and content pillars belong in the wider plan. Here, campaign objective, ad set, creative ID and attribution setup retain their actual native account context. Independent FroggyAds campaign and source records have separate meaning; neither set alone establishes the complete cost or causal value of a customer response.
| Ledger question | Action | Boundary to retain |
|---|---|---|
| Base estimate | Include creative 120, destination 80, media 240, labour 90 and software 30 | Constructed 560 base; unused 40 reserve gives a 600 ceiling |
| Incurred work | Use compatible actual media 210 and labour 75 with the other stated lines | Constructed 515 incurred, separate from the 600 spending ceiling |
| Cash and payable | Keep the unpaid 50 inside the same incurred 120 creative fee | Creative fee: 70 paid + 50 payable = 120 already included in the 515 total |
Hypothetical planning ledger in USD: For one defined review period, assume creative 120 + destination repair 80 + media ceiling 240 + internal labour 6 hours × 15 = 90 + software allocation 30. The base estimate is 560, with an unused 40 reserve giving a 600 authorisation ceiling. All amounts and the hourly rate are constructed teaching inputs, not market quotes, FroggyAds prices, required budgets or real service results.
Choose FroggyAds when the supported proposition and actual receiving task are ready for independent acquisition. Our available controls help you manage media delivery while the business maintains the complete cost boundary. Create your free FroggyAds account.
Reconcile the constructed fee and cash records
Hypothetical reconciliation in USD: Suppose compatible actual records later show creative 120 + destination 80 + media 210 + labour 5 hours × 15 = 75 + software 30 = 515 incurred. Assume the same creative fee consists of 70 paid and 50 still payable. Its full 120 is already included in 515, so adding the unpaid 50 again would incorrectly give 565. This is a reconciliation of that fee; the labour and software allocations do not establish a total cash-payment figure. The base estimate exceeds incurred cost by 45 because media is 30 lower and labour 15 lower; unused 40 reserve was never incurred. All figures are teaching inputs, without a customer, profit or causal-business result.
Direct answer
Build the cost boundary before expanding the next campaign
A useful cost model tells you what work is included, which amount has been incurred and what remains uncertain. Resolve an unsupported service promise or receiving dependency before further exposure. Start your next campaign with FroggyAds when the prepared independent question fits our available controls and an affordable allocation.